Family-owned aviation insurance since 1977
Best Airplane Insurance FAQ
Answers to your airplane insurance questions, backed by a real aviation insurance team. Explore coverage, quotes and the details that matter to you.

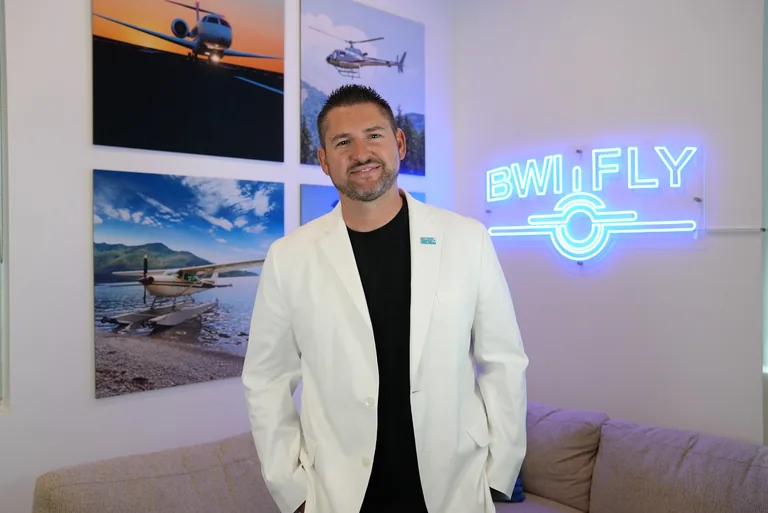
 Matt and the BWI teamReal aviation insurance professionals. Meet us →
Real people. Real experiences.
What BWI customers say
Reviews of BWI’s aviation insurance service.
Great service great follow-up by Katie 11 years as customer
Emily is a fantastic agent. She's very knowledgeable and helpful. I would definitely recommend her for your aviation insurance needs!
If you are shopping for aviation insurance, you MUST speak with Katie! Helpful, knowledgeable and ready to go the extra Nautical Mile for you!
Answers for the way you fly
Find the answers you need.
Understand your options
Find answers about the coverage questions you want to discuss.
Explore the guideYour next quote
Get ready with your aircraft, pilot and operation details.
Explore the guideA real aviation team
Contact BWI to talk through the next steps.
Explore the guideOur team can help you review your aircraft, operation and the next steps for a quote.
Choose a question to read the answer. For coverage specific to your aircraft or operation, talk with BWI and review your policy terms.
Questions 1–20
1. How much is airplane insurance?
An airplane insurance quote depends on the airplane's insured value, pilots, use, location and coverage limits. Compare proposals using the same hull value and liability terms. A broad average can hide important differences between a student-owned trainer, a high-performance piston aircraft and a business jet.
2. Does airplanes have insurance?
Yes. Airplane owners can buy liability insurance for covered injury or property-damage claims and physical damage insurance for the aircraft. Renters need a different form of protection. Whether a particular airplane is insured can only be established from its current insurance documents, not its registration.
3. How much does airplane insurance cost?
The cost depends on the aircraft, pilots and selected protection. Request a written quote with the hull value, liability limits and deductibles shown separately so you can compare like-for-like options.
A student pilot can also apply for life insurance. Disclose flight training and review any aviation exclusion; aircraft insurance does not replace personal life insurance.
5. Are airplanes insured?
Many airplanes are insured, but not every airplane carries the same protection or any coverage at all. An owner's policy may include liability, aircraft damage or both. Verify the insured aircraft, policy dates and covered operations before relying on a certificate or assuming a rental airplane's policy protects you.
6. Do airplanes have insurance?
Many airplanes have insurance, but the policy must fit the owner, pilots and use. Lenders, rental agreements and other contracts may require it. Ask what rules apply to your operation and read the offered terms before relying on cover.
7. How much does airplane renters insurance cost?
Airplane renter insurance is priced according to the liability limit, aircraft-damage limit, eligible aircraft and activities. Ask your school or FBO what its agreement requires, then obtain a current quote. Compare responsibility for deductibles, loss of use and damage to the rented aircraft, not just the annual premium.
8. How much does it cost to insure an airplane?
Provide the make, model, year, agreed hull value, base airport, intended use and pilot histories for a useful airplane insurance estimate. Different liability limits and pilot requirements can change the proposal substantially. A percentage of the purchase price alone is not a reliable estimate of the complete premium.
9. Is airplane insurance required?
Ordinary private general aviation does not have a blanket U.S. federal insurance requirement. Requirements can still arise from state rules, a lender, an airport agreement or a rental contract. Air carriers have separate federal obligations. Check the requirements for your specific aircraft, operation and location before flying.
10. What does airplane insurance cover?
An airplane policy can combine liability protection and aircraft physical damage coverage. Review whether damage protection applies in flight, while taxiing and while parked. Passenger sublimits, approved pilots, use restrictions, deductibles and exclusions matter as much as the headline limit. Medical payments and other extensions depend on the policy.
11. Do airplanes need insurance?
Consider what you would have to pay after an aircraft accident, a passenger injury or damage to someone else's property. Insurance can transfer covered losses within purchased limits, while you retain deductibles and excluded exposures. A lender, airport, flying club or rental agreement may also require specific protection.
12. Are insurance payments to victims of airplane crashes taxable?
The tax treatment of a crash settlement depends on what the payment compensates. Compensatory damages for physical injury or sickness are generally excluded from federal income, but interest, punitive damages and other components can be taxable. Ask a tax professional to review the settlement allocation rather than assuming the entire payment is tax-free.
13. Are model airplanes considered aircraft in an insurance policy?
Check the policy’s definition of aircraft and model aircraft. Cover for claims made by other people and cover for damage to your model are separate questions. Read any membership benefits, flight rules and exclusions. Ask about paid work separately.
14. Are model airplanes covered in homeowners insurance?
Some homeowners policies treat recreational model aircraft differently from full-size aircraft, but protection varies by policy and by the kind of loss. Property coverage for a model does not necessarily mean liability while flying it is covered. Give your insurer the model's use and value and request a clear coverage explanation.
15. Can a student pilot buy an airplane and get insurance?
A student pilot can own and apply to insure an airplane. The insurer will review the aircraft, instruction plan, instructor qualifications and proposed solo flying. Arrange approval before purchase or flight, and make sure the policy's pilot conditions allow the training you intend to undertake.
16. Do aviation insurance companies subrogate against airplane renters?
Subrogation allows an insurer that has paid a covered loss to pursue another responsible party when it has that right. An aircraft owner's insurer may pursue a renter. Renter insurance can respond to covered legal liability within its terms; it does not automatically prohibit the owner or insurer from making a claim.
17. Do I have to insure my airplane?
Whether you must insure an airplane depends on the operation and applicable agreements or law. Private U.S. general aviation is different from air-carrier operations. Review airport, financing and state requirements, and decide how you would fund a loss even if insurance is not mandatory for your flight.
18. Do you buy airplane insurance?
You can buy an airplane policy through an aviation insurance agency or, for some products, directly from an insurer. Provide accurate aircraft and pilot details and compare written coverage terms. Applying or receiving a quote does not itself activate insurance; obtain confirmation of the effective date before relying on it.
19. Do you have to get airplane insurance?
There is no single insurance rule covering every airplane operation. State and contractual requirements may apply to private owners, while air carriers have federal insurance obligations. Ask about the exact rules and agreements affecting your operation rather than assuming either that every aircraft must be insured or that none must be.
20. Do you have to insure an airplane?
Check your lender, airport, lease and relevant rules. Some agreements and operations require insurance. Private flying and air-carrier work have different requirements. Read the exact limits, parties and evidence requested before deciding what policy meets your needs.
21. Do you need airplane insurance?
Airplane insurance is worth evaluating whenever an aircraft loss or liability claim would create a financial burden. Owners and renters have different exposures, and the owner's policy may not protect a renter personally. Start with your actual responsibilities and compare coverage options that address them.
Questions 21–40
22. Does airplane have insurance?
Airplanes can carry aviation insurance, but coverage belongs to a particular policy and insured parties. Confirm the aircraft, use, pilots and effective dates on the documents. Aircraft registration alone does not establish insurance, and a policy covering the owner does not automatically make every person who flies it an insured.
23. Does life insurance cover airplane crashes?
Life insurance may cover a death in an airplane accident, but the answer depends on the contract and any aviation exclusion. Passenger travel, private piloting and professional flying may be treated differently. Disclose flying activities accurately and have the insurer explain any exclusion or endorsement before purchase.
24. Does USAA insure airplanes?
USAA lists aircraft insurance through Acrisure Aerospace. Ask who will issue the policy, whether you qualify and what terms are offered now. Membership or car insurance does not establish cover for an airplane. Get the actual quote for your aircraft and use.
25. How do club airplane insurance work?
A club policy should name the right owner and describe the aircraft, members and uses. Ask which members are insured, what deductibles apply and how claims against members are handled. Review any personal renter policy alongside the club policy rather than assuming it fills every gap.
26. How does airplane insurance work?
The insurer evaluates the aircraft, pilots and operations, then offers terms if it accepts the risk. Once coverage is bound for the agreed period, covered claims are handled under the policy. Keep aircraft values, pilots and uses current, and seek approval for changes that need an endorsement.
27. How does airplane renters insurance work?
Renter insurance is intended for eligible non-owned aircraft operations. Liability and damage-to-non-owned-aircraft protection can have separate limits and conditions. Compare the policy with your rental agreement, including deductibles and loss of use. It supplements your personal protection rather than replacing the aircraft owner's insurance.
28. How much airplane insurance?
Choose liability limits by considering passengers, possible third-party damage, contractual obligations and the limits available for your aircraft and pilots. Review passenger sublimits separately. For physical damage, discuss a supportable aircraft value with the insurer. There is no single amount that is sufficient for every owner.
29. How much airplane renter’s insurance do I need?
Start with the rental agreement and the aircraft value, then compare available liability and aircraft-damage limits. A school-required minimum may not cover all of your exposure. Ask how defense costs, deductibles, loss of use and contractual obligations are treated before selecting a limit.
30. How much commission do airplane insurance agents make?
Pay varies by employer and business agreement. An agency’s commission is not the same as one employee’s income. Ask about salary, commission, benefits, expenses and renewal pay when discussing a job. There is no single rate that describes every agency.
31. How much do airplane insurance cost?
The useful price is a quote for your aircraft and flying profile. Include current hull value, pilot experience, base airport and intended use, then compare equivalent protection. Low premiums can reflect lower limits, larger deductibles or narrower pilot and operating conditions.
32. How much does airplane rental insurance cost?
Rental airplane insurance pricing depends on the renter policy's liability and aircraft-damage limits and eligibility rules. Read the rental agreement first and tell the insurer about instruction, business use or unusual aircraft. The school or FBO's insurance charge may not provide the same protection as a policy issued to you.
33. How much does insurance cost for an airplane?
Aircraft value, repair characteristics, pilot experience and use all influence an airplane insurance quote. Have each proposal identify the same aircraft value and liability limits. Ask which training or storage changes the particular insurer would recognize, without assuming any change guarantees a discount.
34. How much is airplane rental insurance?
For a current rental insurance cost, request quotes with the same liability and non-owned aircraft-damage limits. Check whether the aircraft you fly and your activities are eligible. An inexpensive liability-only option may leave a substantial exposure for damage to the rented airplane.
35. How much is airplane renters insurance?
Renter premiums vary with the protection selected. Liability and aircraft-damage coverage are separate decisions, and the rental agreement can create responsibilities beyond a school's minimum requirement. Compare current written proposals and exclusions rather than treating a sample annual price as your quote.
36. How much is small airplane insurance?
A small airplane is not automatically inexpensive to insure. Its value, configuration, repair costs, pilot experience, use and location all matter. A student-owned trainer and a high-performance single-engine airplane can have very different terms. Supply those details for a meaningful estimate.
37. How to lower airplane insurance?
Ask your insurer which training, storage arrangements or deductible options could improve your proposal. Keep pilot hours and aircraft values accurate and compare equivalent coverage at renewal. Do not reduce a liability limit or understate aircraft value simply to lower the premium; understand the protection you would give up.
38. Is my rental airplane insured by the FBO?
Ask the FBO for the current policy details and rental agreement. Find out whether you are insured and what damage or costs you may owe. The owner’s cover and your renter cover can protect different interests. Review both before flying.
39. Is there a day insurance for renting a private airplane?
Short-term airplane insurance availability varies by product and insurer. Ask about the exact dates, permitted aircraft and activities, minimum premium and cancellation terms. Do not assume an advertised annual renter policy can be purchased by the hour or that a particular insurer offers a daily product.
40. Is your own airplane covered under renter’s insurance?
A personal non-owned policy may exclude aircraft you own or in which you hold an ownership interest. Check the definition of non-owned aircraft and any partnership or club exception. If you own the airplane, an owner's policy is generally the appropriate starting point; disclose the ownership arrangement before purchase.
41. What airplane insurance covers?
Depending on what you buy, it can cover aircraft damage and claims by other people. Check approved pilots, use, places, limits and exclusions. Ask about passenger limits and medical payments separately. Your own injury or lost income may need different cover.
Questions 41–60
42. What does airplane insurance cost?
An airplane insurance estimate needs the aircraft and pilot details as well as the requested limits. Ask for a written breakdown of the hull coverage, liability terms, deductibles and required training. A current proposal is more dependable than an undated average for unrelated aircraft.
43. What is airplane insurance?
Airplane insurance can help pay for covered damage to the aircraft or claims by other people. Read who is insured and what uses are accepted. An owner, renter and flight school can have different duties, so they may need different cover.
44. What is the average cost of airplane insurance?
There is no dependable universal average for all airplane insurance. Aircraft values, uses, pilots and coverage choices vary too widely. For budgeting, obtain a quote using the airplane you intend to buy and the pilots who will fly it, then compare that proposal with equivalent alternatives.
45. What is the average cost to insure an airplane?
An average premium without its aircraft type, insured value, pilot qualifications, coverage and date can be misleading. Ask for a current estimate matched to your situation. A change in liability limits or pilot conditions may matter more than a small difference in the quoted annual price.
46. Where to buy airplanes from insurance companies?
Insurers or appointed salvage sellers may sell damaged airplanes after a claim. Before bidding, examine the sale terms, records, liens, damage and airworthiness implications with qualified professionals. An insurance total loss does not by itself make an aircraft experimental, nor does a purchase establish that it can legally return to flight.
47. Which came first: life insurance, airplane, or parachute?
Life insurance schemes came before the modern powered airplane. Aviva records a policy from 1706. A notable parachute descent followed in 1797, then the Wright brothers’ powered flight in 1903. Earlier parachute designs make a simple claim about the first invention harder to support.
48. Who insure airplanes?
Specialist aviation insurers and underwriting organizations offer airplane coverage through agencies, brokers and some direct channels. The available options depend on the aircraft, pilots and use. Ask who will actually underwrite the policy and compare coverage and service, rather than choosing from a provider list alone.
49. Who insures airplanes?
You can ask an aviation agency about insurers for your aircraft. Some products are also sold directly. The available firms and terms depend on the airplane, pilots and use. Get a current written offer rather than relying on a list of company names.
50. Who insures commercial airplanes?
Look for an insurer willing to cover your actual work, such as charter, training or aerial services. BWI can review the submission with relevant markets. Compare the written offer, including limits, territory, pilots and added terms. A carrier ranking does not establish acceptance.
51. Why don’t airplanes insure on an actual cash value basis?
Some insurance forms use actual cash value, but that is not the basis for every airplane policy. Actual cash value and agreed value can produce different loss settlements. Check the declarations and valuation clause before buying, especially how depreciation, deductibles, partial losses and total losses are handled.
52. Why are airplanes insured on an agreed value basis?
Agreed-value hull insurance establishes an insured aircraft value in advance, subject to the contract's loss-settlement terms. It can reduce valuation uncertainty after a covered total loss. Keep the value realistic and updated for market changes or upgrades; agreed value does not remove exclusions, deductibles or other policy conditions.
53. What happens if an airplane is totaled?
An insurer determines whether an airplane is a total loss under the policy and the facts, including repair feasibility, cost and salvage. There is no universal percentage threshold for every aviation policy. Discuss the settlement basis and salvage rights with the adjuster before accepting an offer or authorizing repairs.
54. Why do airplanes need insurance?
Airplane insurance helps address aircraft damage and liability exposures that may be difficult to fund personally. It can also satisfy financing or operating agreements. The right protection depends on whether you own, rent, teach or operate commercially, so match the policy to those activities.
55. How do airplane insurance claims work?
Put safety first and make required accident reports. Contact the insurer promptly and keep photos, logs and other records. Follow applicable NTSB rules for preserving wreckage. Ask before authorizing work that needs approval. The policy and facts determine the settlement.
56. Are airplane insurance payouts taxable?
An insurance payout is not automatically tax-free. Property proceeds can create a gain when they exceed the relevant tax basis, and different rules apply to physical-injury damages, interest and punitive damages. Keep settlement and cost records and have a tax professional review the particular payment.
57. Why do airplane insurance rates go up?
Premium changes can reflect aircraft values, repair and liability costs, insurer capacity, loss experience and your own risk details. They do not rise by the same amount for every owner. Ask the broker to explain changes in both price and coverage at renewal and compare current like-for-like terms.
58. How long does it take to get airplane insurance?
Binding time depends on the insurer, completeness of the application and any outstanding approvals, training or payment requirements. Some risks can be handled quickly; others need more review. Arrange coverage before the purchase or flight and obtain written confirmation of the effective date and any conditions.
59. Why do airplane insurance companies require pilot training?
An insurer may require training for the aircraft or use you propose. Ask which courses and instructors it accepts before booking. Its conditions can differ from FAA currency rules. Training can support a review but does not guarantee a lower price.
60. What happens if my airplane insurance lapses?
After expiration or cancellation, new losses may fall outside the policy period. Do not assume a grace period or retroactive reinstatement. Contact the insurer promptly, disclose any incidents and obtain written confirmation of renewed coverage before relying on it. A lapse does not automatically erase coverage for a loss during the earlier covered period.
61. Why do airplane insurance companies use brokers?
An aviation broker helps assemble aircraft and pilot information, approach available markets and compare policy terms. Ask which insurers were approached, how compensation works and what support is provided for changes and claims. Access to multiple markets does not guarantee the lowest price or acceptance by every insurer.
Questions 61–63
62. Why are airplane insurance companies specialized?
Aircraft types, pilot experience and flight uses vary widely. An insurer needs to assess those facts. A policy for private flying may have different terms for instruction, rental or paid work. Read the accepted use and conditions for your own aircraft.
63. What is the future of airplane insurance costs?
Future premiums cannot be predicted reliably for every airplane. Repair costs, liability losses, insurer capacity, aircraft values and your own flying profile can change the renewal terms. Plan ahead, keep current risk information and compare actual renewal proposals rather than budgeting around a guaranteed industry-wide price trend.
64. Why is airplane insurance important?
Airplane insurance can protect against covered financial losses and support contractual obligations, but it is not a substitute for safe operations. Choose coverage around the airplane, pilots and activities, understand retained risks, and review the policy when ownership, aircraft value or use changes.
Your next step
Make your next conversation count.
- Aircraft or operation details and intended use.
- The coverage questions you want to discuss.
- Current arrangements and preferred timing.
- Your contact information and next-step questions.
A real team behind you.
Meet Matt White and the people who help BWI customers every day.
Airplane Insurance questions