Family-owned aviation insurance since 1977
The Top 5 Vision Jet Insurance Mistakes, and How to Avoid Them
A more informed insurance conversation starts before your next flight. Know which details to review for your Vision Jet.

 Matt and the BWI teamReal aviation insurance professionals. Meet us →

Real people. Real experiences.
What BWI customers say
Reviews of BWI’s aviation insurance service.
Great service great follow-up by Katie 11 years as customer
Emily is a fantastic agent. She's very knowledgeable and helpful. I would definitely recommend her for your aviation insurance needs!
If you are shopping for aviation insurance, you MUST speak with Katie! Helpful, knowledgeable and ready to go the extra Nautical Mile for you!
A conversation built around your aircraft
Start with what matters to you.
Your operation
Describe your aircraft, equipment and intended work.
Explore the guideYour people
Share pilot experience, training and who will fly.
Explore the guideYour coverage
Review the limits, conditions and next steps with BWI.
Explore the guideCoverage varies by policy. Discuss the proposed terms, conditions and exclusions with BWI.
Vision Jet insurance guide
Use the actual proposal and policy documents when deciding. Insurance terms, availability and premiums depend on the submission; coverage is not effective until binding is confirmed. Request a quote for your aircraft; terms, availability and premiums depend on the insurer and your details.
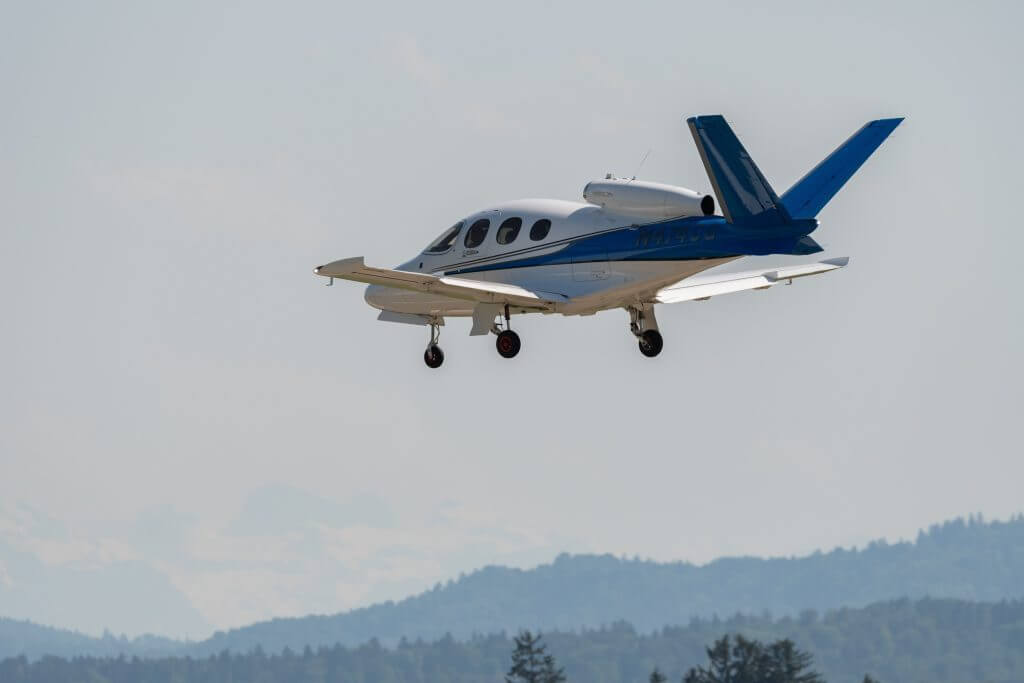
If you’ve bought, flown, or even researched the Cirrus Vision Jet, you already know it’s unlike anything else in general aviation.
It is a pressurized, turbine-powered personal jet with CAPS. Its insurance submission should reflect the aircraft and the pilot’s training.
But when it comes to insuring the SF50, we still see new (and even experienced) owners make the same avoidable mistakes.
And those mistakes?
They can cost you time, limit your coverage, and lead to frustrating back-and-forths with underwriters.
BWI can help you prepare a Vision Jet submission and review the proposed insurance terms.
Here are the top 5 Vision Jet insurance mistakes we see, and how to avoid them.
Mistake 1: Submitting Incomplete Pilot History
Underwriters don’t just want to know that you have a type rating; they want the full picture.
If your broker only sends over “1,500 TT + SF50 Type,” you’re leaving out critical data.
Here's what to submit:
- Total time
- Time in Cirrus (SR22, SR20, SF50)
- Turbine time (if any)
- Recurrent training
- Simulator experience
- Any history of claims or violations
Accurate, complete information gives the insurer a clearer submission to review.
Mistake 2: Requesting a Quote Too Late
We get it. Life is busy. Aircraft closings move fast.
SF50 insurance requires an aircraft-specific underwriting review. Ask about timing early; a fixed turnaround cannot be promised for every submission.
Waiting until the day before delivery could mean:
- No coverage
- Delays in meeting a lender’s or delivery agreement’s insurance requirements
- A last-minute scramble with no time to compare options
What to do instead: Start the insurance discussion before delivery. Allow time to provide the required records, compare terms, meet conditions and arrange the effective date.
Mistake 3: Working With a Generalist Broker
Most aviation brokers are great at quoting Cessnas and Pipers. But turbine-class aircraft, especially a unique one like the Vision Jet, require specialized knowledge.
Topics to check before binding include:
- Liability limits and passenger sublimits
- Required endorsements and policy exclusions
- Whether a liability option without a passenger sublimit is available
What to do: Work with a broker who’s actually written Vision Jet policies and knows the underwriters personally.
Mistake 4: Overlooking Smooth Liability
Read the actual liability schedule.
A combined liability limit may also have a passenger bodily-injury sublimit. Ask how both apply rather than assuming the headline limit is available to every passenger claim.
That’s a big exposure, especially if you fly with family or business partners.
Fix: Ask about a liability option without a passenger bodily-injury sublimit, often called a smooth limit. Review the available amount together with all other policy terms and exclusions.
Pricing and availability depend on the offer. Compare the actual terms rather than assuming a fixed premium difference.
Mistake 5: Submitting to Multiple Brokers
We understand the instinct. You want the best rate. So you ask 2–3 brokers to shop it for you.
But here’s the truth:
Broker access and insurer appetite can differ. Ask which markets will be approached and how the submission will be coordinated.
Before authorizing submissions, discuss who will approach each insurer, what has already been sent and how duplicate submissions will be handled.
Best practice: Agree on a clear submission plan with your chosen broker. BWI can explain which markets were approached and the responses received.
Final Thoughts: The Right Aircraft Deserves the Right Insurance Process
You didn’t choose the SF50 because it was average.
So don’t accept average insurance.
At BWI, we’ve built our turbine quoting flow around the Vision Jet.
We understand the process. We have the relationships. And we’ll help you avoid these mistakes before they cost you.
Call (800) 666-4359 or click below to request your custom Vision Jet quote.
Your next step
A few details help us get started.
- Exact aircraft model, registration and equipment.
- Requested insured value and planned operation.
- Pilot experience, training and relevant approvals.
- Current insurance and preferred effective date.
A real team behind you.
Meet Matt White and the people who help BWI customers every day.
Let’s talk about your next flight