Continue Reading

When a named pilot changes medical qualification, review the aircraft insurance before that pilot's next operation. Explain the current qualification, the proposed flight role and the relevant dates. Being listed by name does not resolve every medical or pilot condition in the policy.
A planned move to BasicMed, a temporary period away from flying and a return after a medical interruption are different situations. Treat them separately. The owner needs an accurate operating plan, while the pilot needs the appropriate medical and regulatory guidance for the intended flight.
At BWI, we can discuss the insurance side of the change and the information needed for an underwriting review. Request an aircraft insurance quote from BWI or contact us before changing the pilot arrangement. We can help present the facts without making a medical determination or promising that one insurer's rules apply to another.
Identify What Has Actually Changed
Start with a plain description of the status rather than a broad label such as medical issue. Is the pilot planning to use BasicMed, holding a different class of certificate, awaiting a decision, or not currently available to operate? If you do not know the correct regulatory description, obtain it from the appropriate qualified source.
Give the relevant dates and the proposed next activity. An owner's plan to resume flying next summer creates a different immediate question from a flight scheduled tomorrow. The policy review should address the facts that exist now, not the status everyone hopes will exist later.
Avoid diagnosing the pilot in the insurance submission. Ask what information the insurer actually requires and how it should be delivered securely. An initial conversation may establish the review process without circulating a complete medical file among coowners, instructors or facility personnel.
Where an application asks a direct question, answer accurately and obtain clarification if the wording is unclear. Omitting a requested fact because it feels unrelated is different from limiting an unnecessary disclosure to the appropriate recipient.
Keep Medical Eligibility and Insurance Acceptance Separate
The FAA describes BasicMed as an alternative to holding a medical certificate for qualifying pilots and operations. That is a regulatory framework, not an endorsement to a particular aircraft insurance contract.
For the intended flight, have the pilot's eligibility evaluated through the appropriate aviation medical and regulatory channels. For insurance, review the actual pilot requirements and any individual endorsements. Do not substitute an old brochure, another owner's experience or a general online statement for the current documents.
The distinction also works in the other direction. A response from an insurer does not establish medical fitness or legal authority to fly. The pilot still needs to satisfy the rules applicable to the role and operation.
This article focuses on coordinating those decisions. It does not provide a diagnosis, decide whether a particular condition permits flight, or supply a universal BasicMed eligibility checklist. Use current official guidance and qualified advice for those questions.
Use a Pilot Status Decision Record
A concise record helps the aircraft owner avoid scheduling someone under an old assumption. Keep sensitive health information out of an ordinary reservation calendar. Record the operational status and the accepted insurance response in a place accessible to those who need them.
The following categories are prompts for review, not coverage conclusions. Use the insurer's actual response to complete the insurance column.
| Situation | Operational question | Insurance review |
|---|---|---|
| Planned BasicMed transition | Is the intended operation permitted | Does current wording accept the proposed qualification |
| Temporary interruption | Who may operate while the pilot is unavailable | What arrangement applies to substitute pilots |
| Return after time away | What preparation and qualification are needed | Do current conditions or training requirements apply |
| Different flight role | Will the person act as PIC crew instructor or passenger | Does the policy review match that role |
| New insurer at renewal | What qualification will be used during the new term | Are the new documents consistent with the submitted facts |
Read Beyond the Named Pilot List
Find the provisions about pilot qualifications, medical requirements and any training or recurrent conditions. A name on the declarations is useful, but it should not be read in isolation from endorsements or limitations applying to that person.
If the wording uses a term you do not understand, ask for its application to the specific proposal. For example, describe the planned medical qualification and role rather than asking only whether BasicMed is covered in general. The response should address your actual aircraft and policy.
Check which document is current. A renewal may replace an earlier arrangement, and a midterm endorsement may change one person's conditions. Keep the accepted response with the documents it concerns so an email about last year's policy does not become the basis for this year's flight.
BWI's aircraft insurance overview is a starting point for the owner discussion. A pilot status change requires the details of the individual arrangement rather than a general description of owner coverage.
If Another Pilot Will Fly During the Interruption
Identify who will operate the airplane while the usual pilot is unavailable. It might be a coowner, instructor or hired pilot, and the proposed activity may be a local proficiency flight, repositioning trip or delivery to maintenance. State the actual plan.
Review the substitute's qualifications and the policy's relevant requirements before operation. Do not assume that the unavailable owner's continued presence in the aircraft resolves the substitute pilot's status. The person acting in the operating role should be evaluated for that role.
If the owner will ride along, explain the arrangement accurately. Avoid calling a person a passenger solely to simplify paperwork when the planned duties are different. Have the operational roles established by appropriately qualified people, then match the insurance review to those roles.
A substitute's request for personal liability protection should also be considered separately from permission to fly. Obtain the actual request and review the policy definitions and endorsements instead of treating acceptance as an approved pilot as the entire answer.
Do Not Change the Aircraft Coverage by Assumption
An interruption in one pilot's flying does not mean the airplane has no remaining exposure. It may still be stored, towed, maintained or flown by someone else. List the activities that will continue before requesting any reduced or restricted arrangement.
If you want to consider a ground or storage option, ask exactly which activities the proposed wording permits. A plan that includes engine operation or a maintenance flight should not be described simply as not flying. Review lender and facility requirements before reducing coverage as well.
Obtain the proposed terms, effective date and cost before making a decision. There is no universal premium outcome when a pilot changes medical qualification or temporarily stops flying. The insurer needs the whole arrangement to respond.
Also record how the aircraft will return to its intended operating coverage. Do not assume a doctor's appointment, training completion or maintenance release automatically changes insurance status on the same day.
Build a Return to Flying Plan With Separate Confirmations
For a return after time away, identify the planned medical qualification, flight role, aircraft and preparation. Qualified aviation professionals should guide the training and operational decisions. The insurance submission should describe that plan accurately without inventing a universal number of required hours.
Ask what the insurer needs before the pilot resumes. If a condition requires training or another document, understand how completion is demonstrated and when the accepted arrangement takes effect. Do not wait until the first solo reservation to discover that someone expected a completion record.
Keep the medical or regulatory confirmation in its appropriate file and the insurance response with the policy. An operational scheduling note can simply state whether the person is currently authorized under the established plan, without reproducing private medical details.
If the return plan changes, update both sides as needed. A different aircraft, instructor or proposed role may mean the previous response no longer describes the first flight back.
A Planned Transition Before Renewal
Consider a hypothetical owner who expects to use BasicMed when the current medical certificate is no longer the basis for future flying. The policy renews shortly before the intended transition. The owner tells BWI about the planned status and the aircraft operation during the new term.
The review addresses the proposed qualification in the new policy rather than relying on the old insurer's general acceptance. Any individual conditions are clarified before the owner chooses and accepts the arrangement. The owner also independently confirms that the intended operations fit the applicable regulatory requirements.
If the owner later postpones the transition or changes the mission, the file is updated. The useful result is a policy review tied to the expected operating facts, with enough time to correct a mismatch before the next flight.
This sequence does not predict acceptance or price. It shows why describing an anticipated change during the quote process can be more useful than discovering the issue after renewal documents arrive.
Remember That a Current Document Is Not the Whole Fitness Decision
The FAA's medical deficiency rule addresses restrictions on operations when a person knows or has reason to know of a disqualifying medical issue. Use qualified medical and aviation guidance for the specific circumstances.
For the owner, the practical task is to avoid treating a calendar date or a scanned document as a substitute for the pilot's current status. Encourage accurate communication about availability and operational roles. Do not pressure a pilot to accept a flight because the aircraft is insured or a trip is already paid for.
Frequently Asked Questions About Pilot Medical Changes
Does BasicMed Automatically Satisfy My Aircraft Policy?
Obtain an answer from the actual insurer and wording for your aircraft and pilot. Regulatory eligibility and insurance acceptance are separate reviews. Avoid relying on a statement about a different company's product or an earlier policy year.
Must I Remove a Pilot Who Temporarily Stops Flying?
Ask what change, if any, is appropriate for the actual situation. Explain whether the person will resume, ride along or perform another role. Removing a name without reviewing the remaining arrangement may create a different problem.
Can My Instructor Fly the Airplane While I Am Unavailable?
Identify the instructor and intended activity, then review the relevant pilot and use requirements. Being a qualified instructor does not by itself settle the owner's insurance conditions or the instructor's own protection.
Will a Medical Change Automatically Increase the Premium?
There is no universal price result. Request the actual terms using accurate pilot and aircraft information. Compare coverage and conditions as well as price before accepting a revised arrangement.
Should I Send My Full Medical File With the First Email?
Ask what information is required and how to submit it securely. Supply requested information accurately, but avoid broadly distributing sensitive documents when the recipient or need has not been established.
Get a Quote From BWI for Your Updated Pilot Arrangement
We can help present the aircraft, pilot status and intended operating plan for insurance review. Tell us about a planned transition or interruption early enough to discuss the available options before the next operation.
Get an aircraft insurance quote from BWI or call 866 788 6291. Include the proposed qualification, role and dates so the request addresses your actual situation.
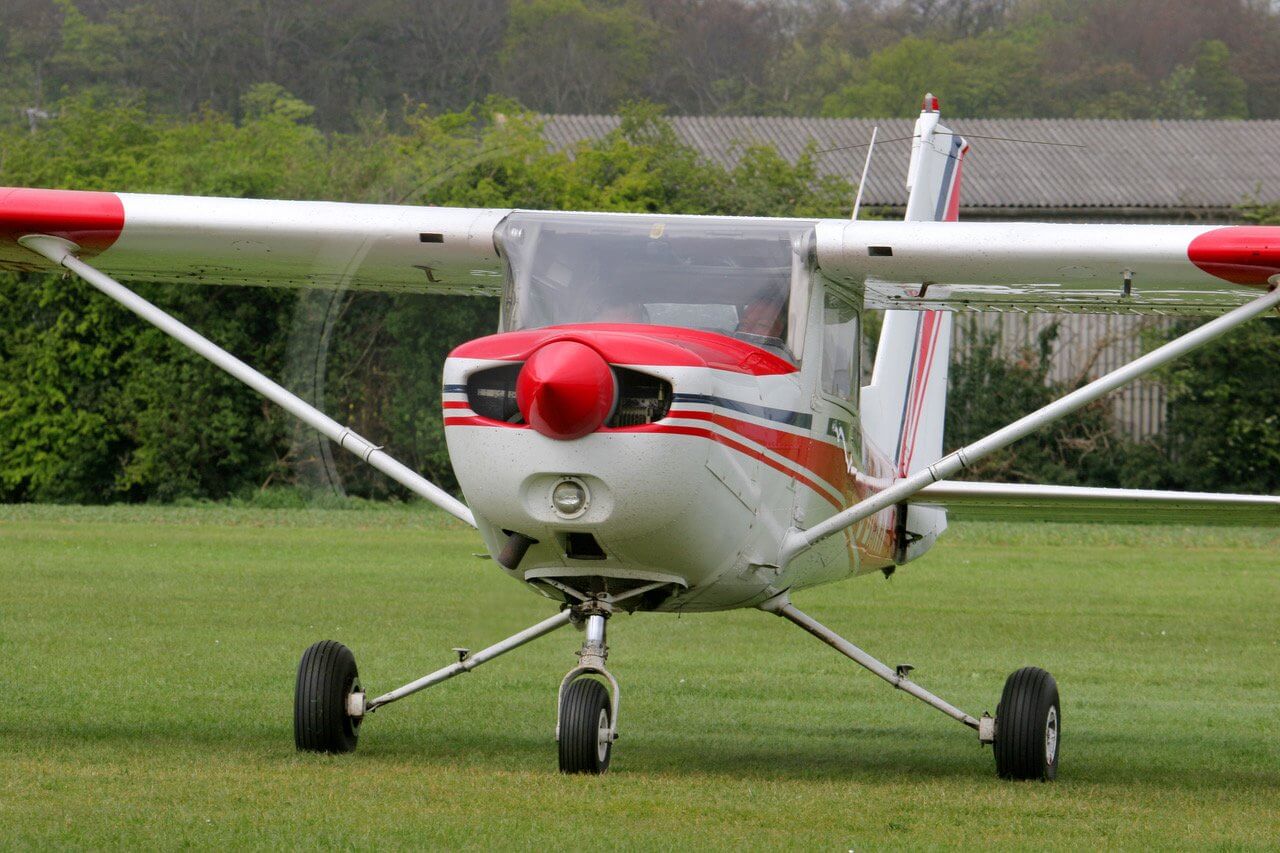
Before using an aircraft for a practical test, confirm that the insurance arrangement has been reviewed for the applicant, examiner and actual flight activity. Include any trip to the test location and the return flight. The examiner's appointment and the applicant's test eligibility do not explain every condition in the aircraft policy.
The checkride may last only part of a day, but the insurance questions can begin much earlier. A borrowed airplane may require owner permission and a separate personal insurance review. A test in your own airplane may involve an examiner's request for documentation. A weather delay may introduce a new date, aircraft or examiner.
At BWI, we can help present that complete plan. Request an aircraft insurance quote from BWI before the practical test with the aircraft, proposed examiner, applicant status and travel arrangements. Send any requested insurance wording while there is still time to review it.
Review the Test Rather Than Just the Applicant’s Name
State which certificate or rating the practical test concerns and who owns the aircraft. Explain whether the applicant has trained in this particular airplane and whether another person will operate it before or after the test. Those details make the request more useful than simply adding checkride to an email subject.
Provide the proposed date and location. If the examiner will meet you at another airport, include the repositioning flight and intended pilot. A policy review for the test does not automatically answer a different solo or ferry operation needed to get there.
If the airplane is rented, obtain the rental agreement and insurance requirements. If borrowed, obtain the owner's permission and relevant insurance review. A friendly arrangement still needs an accurate description of who may operate and what responsibilities the applicant has accepted.
BWI's aircraft insurance overview is the broader starting point for an owner. For a practical test, the application and policy should be considered against the actual activity and people involved.
Map the Whole Checkride Day
Use a short activity plan to identify decisions outside the test flight itself. The table is a preparation tool, not a statement that a given insurer automatically includes or excludes each activity.
Have the appropriate aviation professionals resolve operational roles and qualifications. Then use those facts in the insurance discussion rather than trying to settle them by selecting a convenient insurance label.
| Activity | People and facts to identify | Question to resolve |
|---|---|---|
| Travel to the test | Actual pilot aircraft and purpose | Does the accepted arrangement address this flight |
| Preparation flight | Instructor applicant and activity | Is this instruction different from the test plan |
| Practical test | Applicant examiner and aircraft | Have use roles and any requests been reviewed |
| Discontinued test | Storage new date and possible changes | What must be updated before continuing |
| Return flight | Pilot and current qualification | Does the return plan meet current conditions |
| Later passenger flight | New privileges and proposed passengers | Has the changed operating plan been reviewed |
Do Not Assume the Examiner Is Simply Another Instructor
The FAA identifies a designated pilot examiner as an appointed individual performing an authorized examination role. Describe the practical test as such instead of assuming that a general instruction provision answers every examiner question.
Ask whether the policy has relevant wording about examination, evaluation, instruction or other persons operating the aircraft. Review definitions and exclusions as well as any pilot list. The actual policy may distinguish activities that pilots discuss casually using the same word.
If the examiner requests particular protection, obtain the request in its exact form. Permission to conduct the test, acceptance as a pilot and the person's own liability coverage should not be collapsed into one statement that the examiner is covered.
Avoid making a universal legal conclusion about who will be responsible if something goes wrong. PIC arrangements, the facts of an incident and liability are questions that require appropriate guidance. The insurance review should accurately describe the agreed roles without promising a predetermined outcome.
For an Owner Taking the Test in Their Own Aircraft
Start with the current policy and any individual pilot conditions. A student owner, private pilot adding a rating and experienced pilot completing another qualification may have different accepted arrangements. Submit the actual status instead of treating every practical test as the same risk.
Identify how the airplane will be operated before the test begins. If another pilot delivers it, have that operation reviewed. If the applicant flies to the examiner, confirm the separate regulatory and insurance requirements for that flight through the appropriate channels.
Review any training conditions that remain in effect. Do not assume the checkride replaces an insurance checkout unless that is the accepted arrangement. Ask what evidence the insurer needs and whether there is a separate step before a different operating privilege is recognized in the policy.
Where ownership is through an entity or shared arrangement, keep the owner and applicant identities clear. A person being tested in an LLC owned aircraft is not the same fact as that person individually owning the policy.
For a Test in a Rented or Borrowed Airplane
Ask the owner or operator to confirm that the proposed use and people have been reviewed under its insurance arrangement. Then review your own responsibilities under the rental or borrowing agreement. Those responsibilities may raise questions beyond the owner's physical damage coverage.
Consider a personal nonowned insurance review using the actual test and travel plan. Explain whether you will operate alone, with an instructor or with an examiner. Ask about relevant aircraft damage liability and personal liability terms rather than choosing a limit based only on the cheapest available premium.
Do not assume the owner's policy protects you simply because it protects the owner. Likewise, do not assume buying a nonowned policy erases every contractual obligation in the rental agreement. Send the relevant documents and ask how the actual arrangement responds.
If the aircraft changes, update the review. A replacement airplane may have a different value, configuration or agreement. The fact that it is available for the examiner does not establish that the earlier insurance discussion applies unchanged.
Handle Examiner Documentation Requests Early
Ask what the examiner needs before the appointment. A request for evidence of aircraft insurance differs from a request for a specific endorsement or insured status. Clarify the distinction while the documents can still be reviewed and issued if available.
Send exact legal names and the complete requested wording. Do not edit a certificate yourself or promise that a person can be added in a particular capacity without review. The request should identify the role and interest the proposed insurance is meant to address.
Ask whether the examiner has a document submission deadline and who should receive the response. Keep the issued documents with the test planning file and check for errors in aircraft identity or dates.
If a requested term cannot be provided, resolve that before the test day. Appropriate next steps may involve clarification, another available arrangement or rescheduling. A certificate handed over at the last minute cannot resolve a requirement the insurer never accepted.
Plan for Weather Delays and Substitutions
A practical test can move to another date for weather, aircraft availability or examiner scheduling. Report changes that affect the reviewed insurance facts. The most consequential may be a substitute examiner, replacement aircraft or a different pilot delivering the airplane.
If the current policy renews between the original and new dates, review the new documents rather than relying solely on an old confirmation. Keep the practical test request tied to the policy term and conditions that will actually be in effect.
A discontinued test can also leave the airplane away from home. Describe any extended storage, maintenance or return flight instead of treating the pause as an administrative matter only.
Avoid letting scheduling pressure turn an unresolved question into an assumption. The effort already invested in arranging the test does not determine whether a changed insurance arrangement is accepted.
The Return Flight After Passing Needs Its Own Plan
Consider a student owner who plans to take a practical test away from the home airport. An instructor flies the airplane there with the applicant, and the applicant hopes to return as a newly certificated pilot after passing.
Before the trip, the owner reviews the outbound operation, test and proposed return. The discussion identifies any insurance condition that must be completed or documented before the return plan changes. The owner also establishes the appropriate operational requirements with the instructor and examiner.
Suppose the test is postponed or not completed. The return plan should already account for that possibility. It is unhelpful to discover at sunset that everyone assumed a different person would fly home.
After a successful test, the applicant does not assume that taking passengers or using a different aircraft is automatically addressed by the earlier arrangement. New privileges and current insurance conditions are reviewed together for the next intended operation.
Keep a Compact Insurance File for the Appointment
Retain the current insurance documents, relevant confirmation, rental or borrowing terms and any examiner request. Keep them distinct from the aircraft maintenance and applicant qualification records, although all may be needed during preparation.
Use a short checklist showing which items are complete and who is responsible for each unresolved item. The applicant should know whom to contact if a different aircraft or examiner becomes necessary.
After the practical test, preserve any completion information requested by the insurer and update future operating plans. A clear file helps the owner move from test preparation to the next activity without relying on an outdated student or training description.
Frequently Asked Questions About Checkride Insurance
Is a Practical Test Automatically Included as Flight Instruction?
Review the actual policy and describe the activity as a practical test. Do not assume an instruction provision answers every examination or evaluation question. The applicant and examiner roles should be clear in the request.
Does the Examiner Need to Be Added to the Policy?
The actual wording and requested protection determine the review. Obtain the examiner's precise request and ask how the insurer addresses it. There is no universal naming instruction that fits every owner or nonowner arrangement.
Does the Flight School’s Policy Protect Me Personally?
Ask about your own position separately from the school's insurance. Review the rental agreement and consider an appropriate nonowned insurance discussion. A school's policy number alone is not a complete explanation of your protection or obligations.
Can I Use a Different Airplane at the Last Minute?
Update the insurance review with the replacement aircraft and agreement before relying on the change. Also resolve the separate operational and examiner requirements. Availability does not establish that every earlier approval transfers.
Can I Fly Home Alone Immediately After Passing?
Plan that possibility beforehand. Confirm the applicable operational requirements and any insurance conditions or completion evidence. A successful test does not automatically explain every term of the aircraft policy.
Get a Quote From BWI Before Your Practical Test
We can help present the whole checkride plan, including the test aircraft, examiner request and travel before and after the appointment. Start with the actual operation so the insurance review addresses more than a date on the calendar.
Get an aircraft insurance quote from BWI or call 866 788 6291 before the practical test. Send any rental terms or requested insurance wording while there is time to review the available options.