

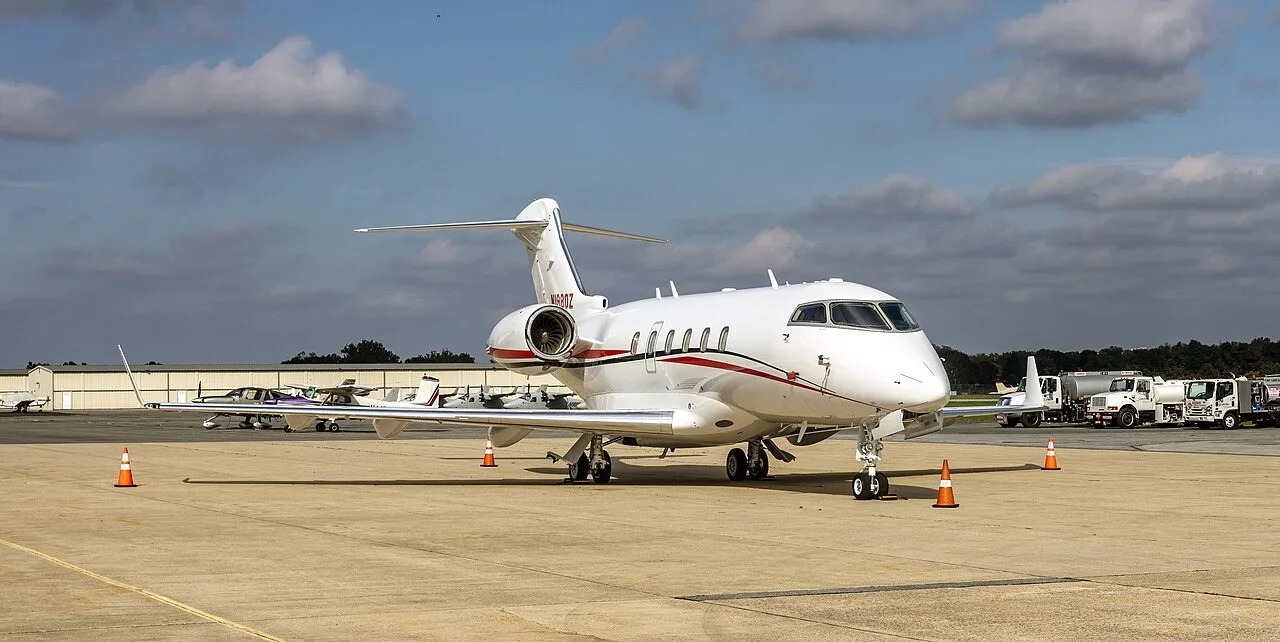
Adding charter use to a Challenger changes the insurance discussion from protecting an existing aircraft operation to reviewing a new arrangement among an owner, an operator and paying customers. The aircraft may keep the same registration and hangar, yet its use, pilots, contractual duties and evidence requirements can change substantially. Those facts should be reviewed before a first charter flight is promised.
A commercial quotation is only one part of that preparation. The owner also needs to understand who will operate the aircraft, how owner trips and charter trips will be handled, and which policy is intended to address each interest. A management agreement, operating approval and insurance certificate serve different purposes. None should be used as a shortcut for reviewing the others.
This guide focuses on adding charter to an existing Challenger ownership plan. It supports BWI’s Bombardier jet insurance page and the broader commercial aviation insurance resource. It is a preparation guide for the insurance review, not approval of a proposed charter business.
Define the charter arrangement before seeking terms
Identify the legal owner, proposed charter operator and management provider. State whether one company will perform several roles or whether separate businesses are involved. Describe who will schedule trips, supply pilots, arrange maintenance and communicate with customers. A label such as “managed aircraft” does not explain the operating structure an underwriter is being asked to evaluate.
Provide the relevant agreements and identify provisions still under negotiation. An unsigned draft can be useful if it is clearly labeled and later changes are reported. Avoid presenting a planned arrangement as final because the insurance quote is needed quickly. The selected terms must eventually be matched to the agreement and operation that actually proceed.
Explain what the owner wants to retain. The owner may expect regular personal or company trips, may want a particular crew, or may set scheduling restrictions. Give the insurance team those facts instead of describing every flight as charter. The review needs to account for the distinct uses and parties without assuming that one broad description answers all of them.
Keep operating authority separate from insurance
The FAA’s resource for pilots, owners and operators discusses charter arrangements and operational control. Have qualified aviation advisers assess the proposed structure and applicable approvals. A private-use policy amendment does not certify an operator, and an insurer’s willingness to consider a submission does not determine whether a flight may legally be conducted.
Ask the proposed operator to identify its role and the aircraft onboarding process. The FAA publishes Part 135 certification requirements and guidance on placing aircraft into service. The responsible operator and advisers should establish what applies to this Challenger. Do not treat a generic checklist as a substitute for that determination.
Track regulatory and insurance milestones separately. One can remain incomplete after progress on the other. The useful status report identifies what has actually been accepted, what remains pending and who must resolve it. Only then can the owner and operator make a supported decision about the proposed start date.
Identify the Challenger and its planned configuration
Submit the model, serial number, registration, year and documented equipment. Distinguish a Challenger 300 or 350-series aircraft from a 600-series model and identify the specific airplane. The underwriter needs a supported aircraft description, not merely the family name used in a management proposal or charter marketing sheet.
Provide the current seating and equipment information requested for underwriting, with changes identified separately. Ask qualified technical advisers to address suitability and aircraft records for the proposed operation. Cabin refurbishment, additional equipment or work required during onboarding can affect the timetable and information needed in the insurance submission.
Keep purchase, valuation and maintenance records consistent. If work is planned before charter begins, distinguish the aircraft today from the completed configuration. Ask when the value and equipment schedule need to be updated. An insurer should not have to infer an installed modification from an estimate attached to an unrelated email.
Map ownership and operator interests in the policy
Ask which policy is proposed to address the aircraft and whose interests it is intended to protect. The owner may be reviewing a policy arranged through the operator, a separate owner arrangement or another structure. Do not assume that the operator’s name on evidence establishes the owner’s full protection or that a separate owner policy automatically fills every gap.
Provide the exact ownership entity, lender information and requested related-party interests. Review named insured and additional insured wording in the capacity intended. A lender’s property interest and a company’s liability interest are different questions. The parties should be represented accurately rather than added to a certificate simply because their names appear in the transaction documents.
Have counsel and BWI review the relevant contractual and insurance responsibilities together. Contractual promises can be broader than the protection available under an offered policy. Identify any unresolved differences before the owner relies on them. The objective is a documented arrangement, not an assurance that two policies must collectively cover everything because both exist.
Explain the owner flight and charter flight handoffs
Describe how the aircraft will be used when the owner requests a trip and when the operator arranges charter. Identify the expected crew, scheduling process and responsible parties for each. Have the operational professionals determine the proper structure, then ask BWI to review the insurance implications of those supported facts.
Keep the permitted-use wording visible. A quotation that addresses one activity should not be described as acceptance of every later variation. Ask how the policy applies to proposed owner flights, positioning, maintenance movements and training associated with the arrangement. The answer must come from the actual terms and relevant acceptance, not a general statement that the aircraft is “commercially insured.”
Changes need a defined reporting path. If a different entity will use the jet, another manager takes over or the owner wants an activity not previously described, contact the insurance team before relying on the earlier review. A continuing registration number does not mean the underlying arrangement has remained unchanged.
Review the pilots who will actually operate the jet
Obtain the requested information for regular, relief and contract pilots. Explain who supplies them and who maintains their training records. A charter operator’s wider pilot roster may include people with different aircraft experience and qualifications. Ask how the offered insurance addresses individual acceptance or any applicable pilot qualification provisions.
Do not assume the owner remains accepted as a pilot merely because the owner flew the Challenger before charter was added. Describe any intended owner flying and the proposed role on those flights. Have qualified operational advisers resolve the arrangement and submit the pilot information for insurance review. Ownership and approval to operate are separate issues.
Keep training evidence current throughout onboarding. A pilot may finish a course while another is still scheduled. Mark the actual status of each and ask which conditions remain under the offer. A general statement that the operator trains its pilots does not answer the model, course, timing and record questions associated with the particular aircraft submission.
Revisit hull value and physical damage responsibilities
Review the requested insured value using the aircraft’s configuration and reliable valuation information. Identify lender requirements and planned improvements. Ask how the policy’s settlement terms, deductibles and relevant conditions apply. A value copied from an earlier private-use schedule may need attention even when the aircraft has not changed hands.
Read the management agreement’s treatment of deductibles and uninsured expenses. It may allocate costs between owner and operator, but that allocation does not create insurance coverage. Ask the appropriate advisers to explain who bears each contractual responsibility and compare the agreement with the protection actually offered.
Discuss custody during maintenance or onboarding work. The aircraft may remain with a service facility before the first charter trip, with different parties authorized to move it. Tell BWI the location, work and proposed pilots. Insurance for a future charter operation should not be assumed to answer every question about the interim ground period.
Compare liability structure with customer requirements
Request a comparison of available liability limits, applicable sublimits and the parties covered under the proposed wording. Describe expected passengers, routes and contractual requirements. The limit requested by one customer or management provider is an input for review, not a universal measure of the protection appropriate for every Challenger operation.
Customer agreements can request specific insurance evidence or additional wording. Establish a process for sending those requests to the responsible insurance contact. Avoid having sales or dispatch personnel promise policy changes before review. A routine certificate request and a new contractual insurance obligation should not be treated as the same administrative task.
Ask about any separate regulatory insurance evidence relevant to the operator. The FAA’s requirements resource discusses liability insurance filings for certain air-carrier operations. Have the responsible operator and insurance professionals determine the applicable evidence. A customer certificate, an accepted policy and a regulatory filing should each be checked for their particular purpose.
Make territory and utilization assumptions explicit
Give BWI an outline of expected charter activity, owner use and geographical scope. Mark projections as projections. The first year’s actual use may develop gradually, but the initial proposal should still describe the business plan accurately enough for underwriting. A blanket statement that the aircraft will fly “wherever customers want” is not a useful territory submission.
Before accepting a trip outside the reviewed operation, ask whether additional insurance or documentation review is needed. Aircraft range, operator capability and policy territory are different subjects. A long-range Challenger does not automatically carry insurance acceptance for every destination, routing or activity that a customer might request.
Report meaningful changes during the term. More flying, a new base, different customer work or another operational arrangement should be reviewed when it develops, rather than hidden until renewal. Ask BWI what information the insurer needs and preserve the response. Accurate updates help keep the policy record connected to the operation being conducted.
Plan the first commercial flight through a shared checklist
Create a checklist with separate entries for operational readiness, insurance acceptance, pilot records, contracts and evidence. Give each item a responsible person and a supported completion record. The operator’s progress on one item should not be mistaken for completion of every item needed by the owner and other parties.
Ask BWI to identify outstanding insurance conditions and the requested effective date. If the aircraft is moving from a prior policy, coordinate the handoff so neither arrangement is cancelled or relied on based solely on an expected date. Obtain the evidence appropriate to the accepted coverage and review any remaining conditions before the new operation begins.
Build in a way to handle postponement. Maintenance findings, training availability or onboarding requirements can move the start date. Update the facts and ask which documents need revision. Avoid making a commercial commitment on the assumption that an insurance proposal will automatically adapt to the schedule the sales team prefers.
Understand what interruption protection has been offered
The owner may expect charter revenue to offset aircraft costs. That financial expectation should not be confused with insurance for revenue lost while the jet is unavailable. Ask what, if any, interruption-related protection is offered, what events trigger it and what limitations apply. Do not assume that hull coverage includes every consequence of downtime.
Read the operator agreement’s treatment of maintenance, substitution and lost trips separately. A contractual promise to arrange alternative transportation does not establish that its cost is covered by the owner’s aircraft policy. Similarly, a maintenance support program has its own scope and conditions. Keep each agreement available for the professionals responsible for reviewing it.
Use realistic figures in the business plan and avoid presenting insurance as a guarantee of charter profitability. BWI can review the requested coverage and explain available terms. The owner’s financial advisers should assess the commercial assumptions. A complete decision recognizes which expenses are contractually allocated, which are insured and which remain an accepted business risk.
An example of a postponed charter start
Consider an illustrative Challenger owner who expects charter onboarding to finish on the first of the month. A required aircraft item takes longer than planned, while the owner still wants a private trip during the delay. The correct response is not to mark every flight cancelled or assume every planned use remains accepted. The parties need to review the revised facts.
Ask the operator and qualified advisers to establish the proposed flight structure and technical status. Tell BWI which policy is expected to be in effect, who will fly and whether the insurance handoff date has changed. If another pilot or facility is involved, include that information. Keep the owner trip distinct from a charter start that has not yet occurred.
Resolve the revised coverage dates and conditions before relying on either the old or new arrangement. Update the first-charter checklist when onboarding is actually complete. This scenario is not a statement that any particular interim flight is permissible or insured. It illustrates why an owner, operator and insurance team need a shared record when commercial plans are delayed.
Review the insurance assumptions in the charter budget
Ask the owner and operator to identify which expenses the commercial proposal assigns to each party. Insurance premium, physical damage deductibles, required training and contract pilot costs may appear in different parts of the budget. Bring the relevant assumptions to the insurance discussion so the owner does not compare an all-inclusive management estimate with a quotation that addresses only a specified policy.
Separate a present offer from a possible later change. The operator may expect utilization to grow, another pilot to join or different coverage to become available after experience develops. Those expectations belong in the business plan as assumptions. They should not be counted as accepted insurance terms or guaranteed savings unless supported by the actual offer and applicable conditions.
Test a delayed start as well as the planned start. Ask what costs continue if the aircraft remains in maintenance, training moves or commercial onboarding takes longer. Have the responsible advisers interpret the agreements and ask BWI which insurance questions remain. A policy effective date, a management billing date and the first revenue flight need not be the same event.
Finally, compare the accepted arrangement with the owner’s ability to maintain it. A pilot or training condition can have practical scheduling and expense consequences even when its wording is clear. Identifying those consequences before signing helps the owner evaluate the proposal honestly. It does not establish a premium estimate, promise charter revenue or assume that insurance will pay business expenses outside its terms.
Challenger charter insurance questions
Does a management agreement automatically add charter coverage
No assumption should be made from the agreement alone. Submit the actual use, operator, aircraft and pilot plan to BWI. Review the offered policy and evidence, and have aviation advisers establish regulatory requirements. A signed management contract and an accepted insurance arrangement are different records.
Can I keep flying the aircraft myself
Describe the proposed owner flying, roles and trips rather than assuming the prior arrangement continues. Have qualified professionals review the operation and ask BWI to coordinate pilot acceptance and policy questions. The answer depends on the facts and terms, not simply ownership of the Challenger.
Is the operator’s certificate of insurance enough for my lender
Give BWI the lender’s actual instructions and the proposed policy information. A certificate may provide evidence for a purpose, but it does not replace required policy wording or create coverage. Confirm the accepted lender interest and documentation before treating the requirement as complete.
Will charter revenue be insured while the aircraft is grounded
Ask what interruption-related coverage has actually been offered and what conditions apply. Do not infer revenue protection from a hull premium or management contract. Review the relevant insurance and service agreements separately, then assess remaining business exposure with the appropriate advisers.
Request a Challenger charter insurance review from BWI
Provide BWI the Challenger details, proposed charter operator, ownership structure, agreements and intended owner use. Add pilot and training information, requested coverage, expected territories and the realistic onboarding timetable. Identify pending decisions so the insurance submission reflects the operation you are working toward.
Request a Challenger insurance review and quote from BWI. Ask the team to explain the available terms and the owner, operator and effective-date questions that need attention before charter use begins. A clear submission supports a commercial decision that can be reviewed and documented before the first trip is scheduled.
Sources
Continue Reading


