

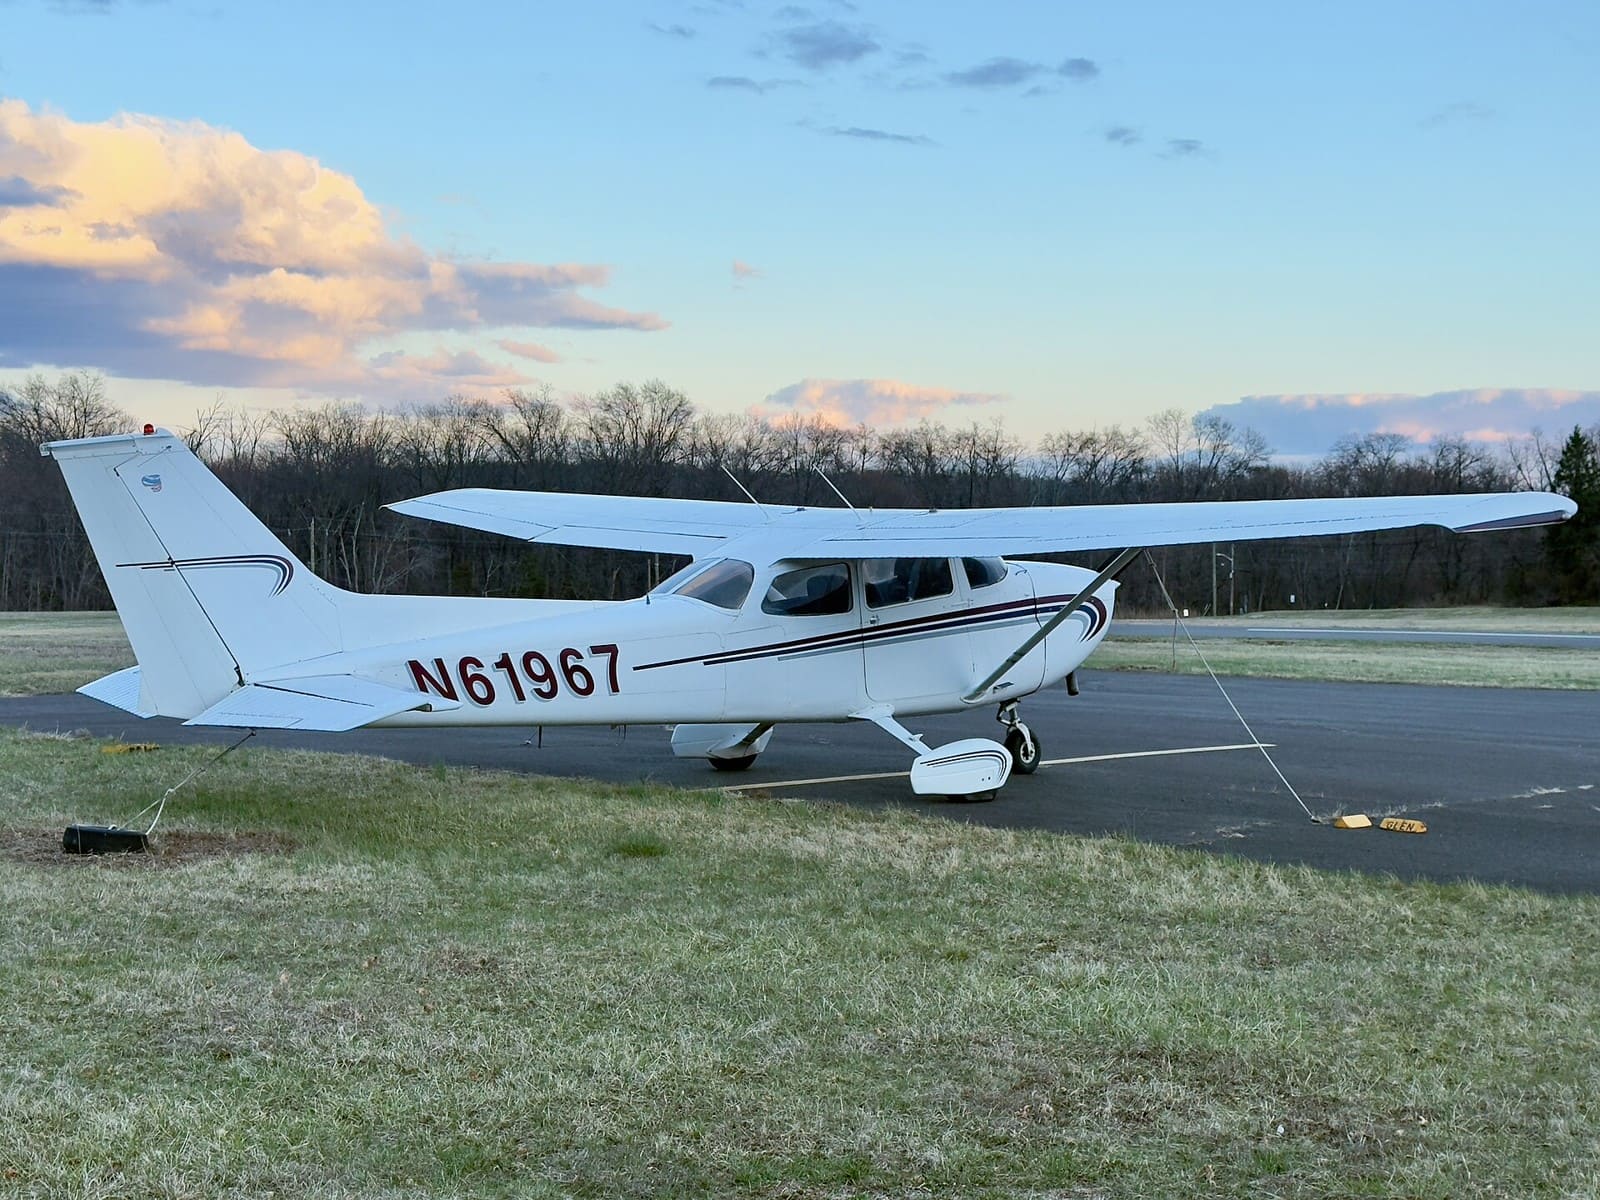
Pipeline patrol aircraft insurance should describe the inspection service the operator actually sells. Give BWI the aircraft, pilots, observers, pipeline client, operating area and reporting responsibilities before relying on an existing commercial policy. A contract to supply an airplane and pilot is different from an agreement to identify, interpret and report pipeline conditions. The submission needs to show which responsibilities your business accepts, including work performed after the flight.
This guide covers insurance preparation for manned airplane or helicopter patrol businesses. It focuses on recurring client contracts, aircraft operations, observers, equipment and the distinction between collecting information and providing an inspection opinion. It is separate from drone pipeline work and general aerial photography. Qualified aviation, pipeline and legal professionals should establish the operating and contractual framework. This article does not prescribe patrol routes, flight profiles, inspection methods or compliance procedures.
Start with BWI commercial aviation insurance and describe the specific pipeline patrol service in your inquiry.
Define the service promised to the pipeline client
Start with the actual statement of work. Describe whether the business supplies an aircraft and pilot, carries the client’s observer, collects images, produces an observation record or provides technical analysis. Those services can involve different responsibilities even when the same airplane follows the same corridor. An insurer needs the real deliverable rather than a short description that the company does aerial work for an energy customer.
Identify who decides what must be observed and who evaluates the results. A client employee interpreting conditions has a different role from an employee of your business issuing conclusions. If your sales proposal uses terms such as inspection, detection or verification, explain what those words mean in the contract. Have qualified advisers reconcile inconsistent descriptions before the business assumes a policy quotation answers every promise in its marketing material.
Identify the contracting parties and aircraft operator
List the legal aircraft owner, operating business, pipeline client and any prime contractor. Explain who pays your company and whether your business contracts directly with the pipeline operator. A brokered assignment or subcontract through an engineering firm can introduce other agreements and evidence recipients. Use legal names in the submission rather than assuming a pipeline brand identifies every organization with an interest in the project.
If the customer owns the aircraft and hires your pilots, or your company supplies an airplane to another operator, describe that arrangement explicitly. Ownership, operational responsibilities and contractual promises should remain visible as separate facts. Common ownership between companies does not make their policy status interchangeable. Give BWI the relevant leases or service agreements so the insurance inquiry follows the actual division of work and responsibility.
Describe the patrol program and its changes over time
Provide the geographic area, bases, proposed season and utilization information requested for review. Explain whether the business performs recurring patrols, occasional assignments or additional work after a specific event. A long-term contract can change as the client adds assets or shifts schedules. Give realistic estimates and identify provisional plans, rather than treating a preliminary forecast as a permanent description of the operation.
Include temporary bases, positioning and periods when aircraft or equipment are held away from the normal location. The customer’s patrol schedule may describe only one part of the aircraft’s activity. Ask what details the insurer needs to understand the complete assignment. Maintain a process for reporting material changes so a response prepared for one region or service does not become an unsupported assumption about every later client request.
Build a pipeline patrol insurance submission record
The comparison below organizes the main subjects for the insurance discussion. It is a record of the proposed business arrangement, not a pipeline inspection checklist or a flight plan. Add the real parties, aircraft and deliverable. A concise factual account helps the reviewer understand where aviation operations end, where interpretation begins and which responsibilities belong to your company rather than the client’s own personnel.
Choose one person to reconcile information from operations, sales and contract administration. These teams may hold different versions of the assignment. Keep dated revisions and actual insurance responses together, with unresolved questions identified. That allows the business to explain which proposal was reviewed without treating an unanswered email, a renewal discussion or a generic customer certificate as evidence that all contract requirements have been accepted.
| Patrol submission subject | Information for review |
|---|---|
| Service | Aircraft provision observation data collection or technical report |
| Parties | Aircraft owner operator pipeline client and prime contractor |
| Aircraft and people | Aircraft values pilots observers and their employers |
| Equipment | Sensors ownership custody and supporting property |
| Contract | Full insurance provisions and professional responsibilities |
| Changes | Additional region substitute aircraft or expanded deliverable |
Supply accurate aircraft and equipment information
Identify the aircraft make, model, registration, ownership and proposed value. Describe relevant configuration and any installed or carried equipment in the detail requested by the insurer. Qualified maintenance and aviation professionals should establish technical suitability and approval requirements. A policy review does not approve a sensor installation or establish that an airplane is appropriate for a particular patrol assignment or operating environment.
Separate the aircraft from equipment owned by the customer or another contractor. Cameras, sensors and supporting devices may have their own property and custody questions. Explain who supplies, handles, stores and returns each significant item. Do not assume the aircraft’s hull value includes every device aboard or that a client’s equipment policy resolves your company’s contractual responsibility. Ask how the actual policies address the interests you have disclosed.
Explain pilots observers and client representatives
Provide the proposed pilots and their experience information as requested, including aircraft assignments and relevant duties. Qualified aviation personnel must independently establish pilot privileges, training and operational requirements. For insurance, ask how the issued wording identifies acceptable pilots and any conditions that apply. A client’s approval of a pilot does not substitute for understanding the aircraft policy or documenting completion of insurer requirements.
Describe observers, sensor operators and client representatives who may be aboard. Explain their employers, duties and relationship to the aircraft business. Do not decide policy classifications merely by calling everyone crew or everyone a passenger in ordinary conversation. Ask how the actual definitions and liability provisions relate to the disclosed roles, particularly if the client changes who travels or asks your staff to take on additional observation responsibilities.
Keep pipeline obligations separate from aviation insurance
Pipeline owners and their qualified advisers should determine the inspection program and applicable pipeline requirements. PHMSA publishes information about pipeline patrol and inspection subjects, but an agency resource does not determine that your particular service satisfies a client’s obligations. The aircraft operator should receive a defined assignment and identify any technical or contractual questions before presenting its service as a complete compliance solution.
Aviation operating requirements also need their own professional review. Insurance acceptance does not authorize a flight, determine a permissible route or certify an inspection method. Conversely, a client’s acceptance of a deliverable does not amend a policy. Keep the different decisions connected through one accurate statement of work, while recognizing that the pipeline client, aviation professionals, legal advisers and insurer may each address a different part of the proposal.
Review aircraft damage terms for the disclosed patrol use
For physical damage, compare the requested aircraft value, deductibles, covered states and relevant limitations with the offered wording. Ask specifically how the declared patrol activity is treated. Do not assume terms arranged for personal flying, charter or another aerial service apply unchanged. A policy’s broad title does not explain every condition or exclusion that may be relevant to the aircraft and work being submitted.
Use the actual policy and endorsements when reviewing the response. BWI’s specimen policy resources can help illustrate why definitions matter, but a sample is not confirmation of the offered terms or your issued contract. Keep answers about equipment, storage and operating use with the aircraft record. That gives the owner a better basis for comparing proposals than selecting a premium solely because another operator uses a similar model.
Examine liability and professional service allegations separately
An aircraft accident involving injury or property damage raises different questions from an allegation that a patrol report omitted an important condition. A customer might make a financial demand even when no aircraft crash occurred. Explain the reporting service and the parties relying on it before asking which insurance arrangements may be relevant. Ordinary flight liability should not be presented as universal protection for every professional conclusion or missed observation.
Ask the appropriate insurance advisers to examine the actual offered definitions, exclusions and insured interests. If your company interprets imagery, provides recommendations or accepts a technical standard of performance, make those obligations explicit. This guide does not promise that a particular professional liability product is available through BWI. The task is to identify the service question early and understand the response before the business accepts an unsupported financial obligation.
Obtain full client insurance requirements before bidding
Request the insurance section of the contract, including relevant schedules and referenced attachments. Identify limits, legal names, dates, evidence recipients and requested policy changes. A procurement summary may omit provisions that matter to the actual placement. Send the wording to BWI early enough for review before the business commits to a price or tells the customer that every insurance requirement can be satisfied.
If additional insured status, waivers or another condition is requested, ask what can be addressed under the proposed arrangement and how it would be documented. A certificate reports supported information; it does not independently issue endorsements or expand coverage. Keep unresolved items visible. Do not reuse a certificate from another pipeline contract solely because it looks familiar, remains within its dates or was accepted by a previous customer.
Review indemnity and the client’s loss assumptions
Have qualified counsel explain obligations involving defense, indemnity, service interruption, property and financial loss. A contractual promise can extend beyond the benefits an insurance agreement provides. Give the relevant language to the insurance team and ask how the offered wording relates to it. Do not assume that the contract’s definition of an insured event controls what the aircraft insurer must cover.
Pay particular attention to how the agreement describes missed observations, reporting delays and reliance on your findings. This is not a suggestion to negotiate a particular clause; appropriate counsel should advise the business on the actual contract. For insurance, disclose the accepted responsibilities without reducing them to a statement that the company only flies. The submission needs to reflect the service for which the client can hold your business accountable.
Explain subcontracted analysis and substitute aircraft
If another business processes the data or issues an inspection opinion, identify its scope and relationship to your company. A subcontractor’s policy does not automatically resolve your own obligations to the pipeline client. Supply the actual agreement and describe who signs the final deliverable. Make clear whether your company simply passes along another firm’s work or accepts responsibility for the result as part of its own service.
When an aircraft becomes unavailable, identify a leased substitute or another operator’s proposed involvement as a separate change. Give the owner, pilots, aircraft and dates requested for review. A maintenance delay or client deadline does not establish automatic insurance acceptance of the replacement. Retain the actual response before treating the substitute as meeting the existing contract, and reconcile any new evidence with the correct entity and aircraft.
Include ground custody storage and employment interests
Describe where aircraft and equipment are kept during the assignment and who holds custody at each relevant stage. A temporary hangar, maintenance provider or customer facility may involve different agreements from the normal base. Ask which documents are needed to review the proposal. Avoid assuming another party’s property or liability policy answers every question simply because it has agreed to hold the airplane or equipment.
Identify employees and contractors in the detail needed by the appropriate insurance advisers. Aircraft coverage should not be assumed to replace workplace, premises or other business arrangements. If the company also provides ground inspection, vehicle services or consulting, disclose those activities separately. A complete account helps the advisers address the actual business without forcing every interest into one aircraft policy merely because flying is central to the contract.
Compare proposals with the same defined service
When reviewing prices, keep aircraft, values, pilots, locations, client contracts and deliverables consistent across submissions. A response based on carrying a client observer may not be equivalent to one prepared for your company issuing technical findings. Ask which assumptions support the proposal and which conditions remain outstanding. An attractive premium is not proof that two insurers have been asked to consider the same operation.
Compare the actual limits, deductibles, insured parties, exclusions and material conditions alongside cost. Clarify what is required before binding a new arrangement or changing an existing policy. Do not cancel current coverage or promise final evidence based solely on a preliminary estimate. Keep the final documents with the reviewed statement of work so the business can identify what was established and which responsibilities it retains.
Consider a fictional expansion of a patrol contract
Imagine a fictional airplane operator hired to carry a pipeline company’s observer along an established corridor. The client later asks the operator to supply its own observer, collect sensor information and issue a condition report. A second region and a subcontracted analyst are added. This example illustrates an evolving insurance submission; it is not a BWI customer account, an inspection recommendation or a statement that coverage is available.
The operator records each change instead of treating the request as more flying of the same kind. Qualified professionals address the operating and contract questions, while the insurance team receives the new staffing, equipment and reporting proposal. The original certificate is not offered as proof that every added service is accepted. Actual responses remain with the contract file so operations and sales can distinguish confirmed arrangements from outstanding questions.
Frequently asked questions
Is pipeline patrol insurance the same as aerial photography insurance
The actual services need to be described. Supplying images, carrying a client’s observer and issuing technical inspection findings can involve different obligations. Give BWI the statement of work rather than assuming that a general aerial photography description answers the pipeline contract’s requirements.
Will aircraft liability cover an allegation about a missed condition
Do not assume it will. Explain the deliverable, interpretation responsibilities and potential reliance on the report. Have the relevant insurance advisers review the allegation category under the actual offered or issued wording. A demand about service performance is a separate question from damage caused directly by an aircraft accident.
Does the client’s equipment insurance settle our responsibility for its sensors
Not by itself. Describe equipment ownership, custody and the relevant contract. Ask how the actual policies address your interests and obligations, including property supplied by another party. A certificate showing that the client has insurance does not independently resolve your company’s contractual promises.
Can a new region be added without an insurance review
Identify the proposed change and ask what information is required under the particular arrangement. A continuing customer relationship does not establish acceptance of every location, base or activity. Keep the response with the updated project description before relying on the earlier terms for expanded work.
What should we send for an accurate patrol insurance quote
Provide aircraft and value information, ownership and operating entities, pilots, occupants, locations, expected activity, equipment and full client requirements. Include the actual deliverable and subcontracting arrangement. Consistent facts allow the insurance team to review a defined proposal instead of guessing what pipeline patrol means for your business.
Does a recurring contract guarantee the same premium at renewal
No fixed renewal result should be assumed. Submit current aircraft, personnel, activity and contract information when terms are reviewed. Ask how the proposal reflects the actual program and compare the offered conditions as well as price. A prior season’s estimate is not a current quote for an expanded or otherwise changed service.
Bring the pipeline patrol proposal to BWI
Prepare the contract scope, aircraft details, pilot and observer roles, equipment ownership and reporting responsibilities. Include locations, seasonal plans, leases and the full insurance requirements. Identify matters still awaiting technical or legal review. A clear submission helps BWI understand the actual operation and explain which additional information is needed before the business relies on a proposed arrangement.
Request a commercial aviation insurance review and quote from BWI before committing to patrol work on a general policy description. Compare the response with the final contract and issued documents, then return material changes for review. Retain the operative statement of work with the insurance correspondence so later questions can be examined against the aircraft, people and services that were actually disclosed.
Sources and related resources
BWI commercial aviation insurance
Continue Reading


