

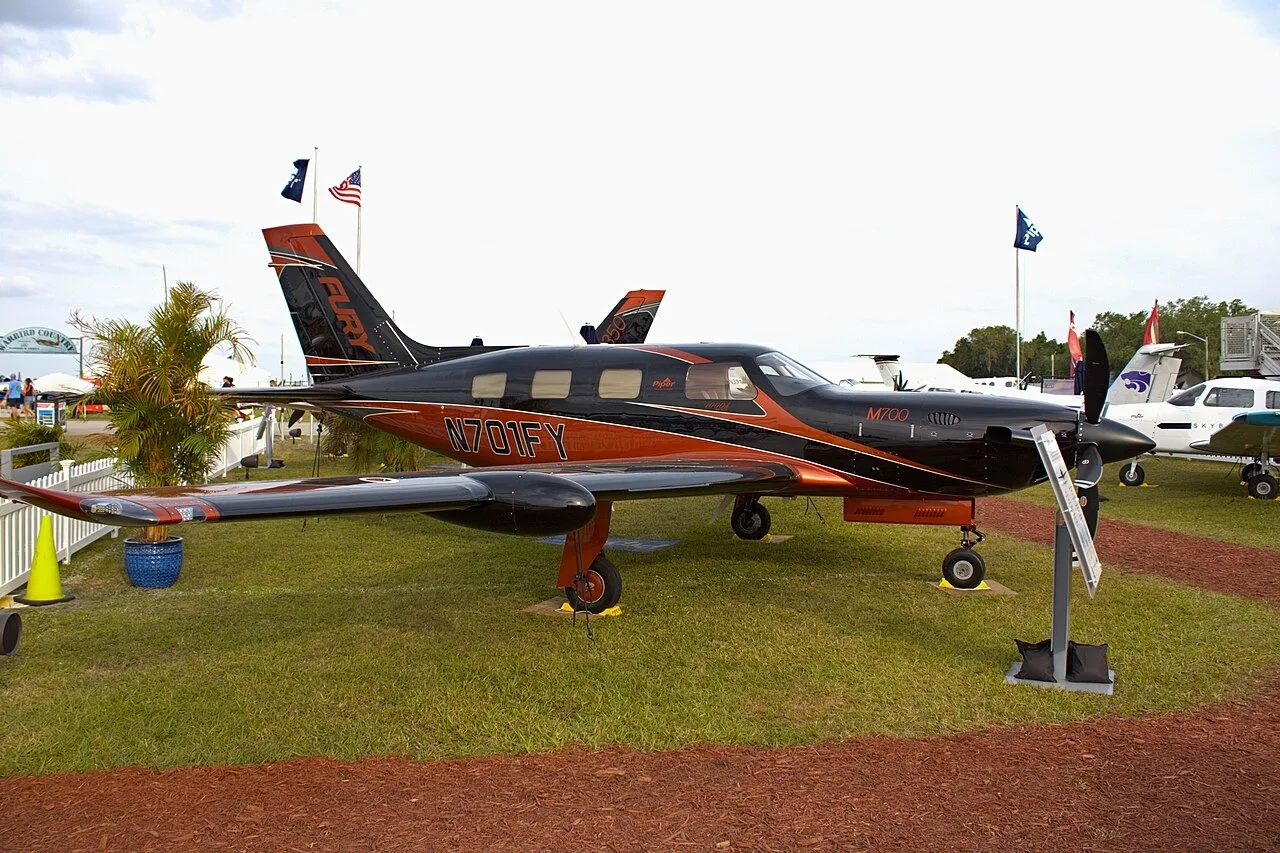
Buying an M700 Fury can change more than the aircraft on your hangar floor. A pilot moving from a piston airplane is also introducing a new training plan, a different aircraft value and a proposed turbine operation to the insurance market. Those decisions deserve attention before the purchase schedule becomes fixed.
Piper M700 Fury insurance should be reviewed around the owner who will fly, the aircraft being purchased and the trips it will make. The model name alone does not establish a premium or a standard set of pilot requirements. A detailed submission helps BWI ask the right questions and compare the terms actually available for your transition.
This guide is for an owner preparing to purchase or take delivery of an M700 as a first turbine aircraft. It focuses on practical insurance preparation rather than aircraft operating instruction. For broader turbine coverage, visit BWI’s turbine and private aircraft insurance resource, then use the model-specific questions below to prepare your own review.
Begin with your current experience and intended use
Write a short description of the flying you do today. Include the aircraft flown recently, approximate annual use, relevant instrument experience and the type of trips you expect to make in the M700. Support the formal application with accurate records. A concise explanation helps make the numbers meaningful without replacing the detailed pilot information the insurer requests.
Next, describe the intended first year. Will the airplane primarily serve personal trips, business travel or a combination? Will you be the only regular pilot? Are another owner, a hired pilot or an instructor expected to operate it? Give BWI the actual arrangement. A privately owned airplane can still involve several people whose roles need to be distinguished in the submission.
Do not treat the insurance review as a test that requires a perfect story. It is better to state a training need or uncertain date accurately than to present future qualifications as complete. If the operation is still being developed, identify the decisions that are pending. BWI can then seek terms based on a realistic plan instead of asking an insurer to reconsider an account after important facts change.
Keep the M700 distinct from other Piper models
Use the aircraft’s exact identity, equipment records and purchase documents. The M700 Fury belongs to Piper’s M-Class, but a quote prepared for a Meridian, M500 or M600 is not automatically an offer for an M700. Differences in aircraft value, configuration, pilot experience and intended use need to be reflected in the current submission.
Piper’s aircraft model directory provides a useful starting point for identifying its product families. Within the broader lineup, do not confuse a piston aircraft such as the M350 with a turbine M-Class airplane. For insurance purposes, give the reviewer the supported aircraft designation rather than relying only on a familiar family name.
For a pre-owned purchase, make records of modifications, significant maintenance and disclosed damage history available when requested. For a new purchase, identify delivery configuration and any work planned immediately afterward. The insurance file should describe the airplane you will own at the relevant time, including changes that have not yet been installed or accepted.
Present a transition plan before reserving the first solo trip
A useful transition plan identifies the training provider, course, dates and proposed follow-up flying. It also identifies the person expected to conduct any instruction or supervision. Ask the provider to explain the training product precisely, then have BWI review how it fits the insurance proposal. A reservation confirmation alone does not establish satisfaction of a policy condition.
Piper’s M700 materials describe aircraft-specific training support for qualified purchasers and pilots. Programs and purchase benefits can change, so verify the current offer with Piper or the seller. More importantly, confirm the course and pilot arrangement accepted for your particular insurance submission. A manufacturer purchase benefit does not replace an insurer’s review of the owner and proposed operation.
Plan the first unsupervised trip only after the relevant qualifications and insurance conditions are resolved. An owner may be ready to accept the aircraft financially before being ready to operate it independently. If that is your situation, describe a delivery pilot or other support arrangement and obtain the necessary acceptance. The transaction and flight plans do not have to be identical, but they must be coordinated.
Separate aviation qualifications from insurance acceptance
Your instructor and other qualified aviation professionals should confirm the regulatory qualifications required for the aircraft and proposed flights. The current 14 CFR 61.31 addresses several additional training and endorsement subjects. This article does not determine an individual pilot’s eligibility to conduct a flight.
The insurance question is related but separate. An insurer may evaluate your experience, recent activity, course and support plan under its own underwriting criteria. Ask what the offered terms require rather than assuming that a completed endorsement or a general instructor signoff resolves every condition attached to the policy.
Keep the evidence organized. A pilot summary shows experience, a training record shows what was completed, and the insurance documents show the accepted coverage arrangement. When a condition calls for further confirmation, send the relevant record and obtain the response before changing how the aircraft is operated. Maintaining these distinctions helps prevent an avoidable misunderstanding during the transition.
Make mentor pilot arrangements usable
If the proposed terms include a mentor or instructor, establish who will serve in that role and submit the requested qualifications early. Ask whether the person is accepted for instruction, delivery, supervised flying or another defined activity. A pilot can have substantial experience and still need to be specifically reviewed for the arrangement being proposed.
Clarify how any required period ends. The policy or insurer’s acceptance may identify training, experience, an evaluation or another condition. Do not assume that flying a certain number of hours ends every obligation unless that is what the applicable terms actually require. Record completion and ask BWI to coordinate the next step before removing support that formed part of the original offer.
Consider continuity. A mentor who is available for one delivery day may not be available for later training flights. Discuss likely scheduling needs and alternatives with the training team. Submit a replacement person when necessary rather than treating mentors as interchangeable. A reliable support plan is easier to maintain when both the people and the insurance conditions are understood in advance.
Describe automation without promising an insurance discount
Modern aircraft equipment belongs in the underwriting submission, but it should be described through the actual aircraft records. Give BWI accurate information about the installed systems, modifications and training relevant to their use. Equipment that is planned, optional or fitted to another airplane should not be represented as already installed on yours.
Piper describes the M700’s safety and automation features in its product materials. Those capabilities do not establish a universal insurance credit or eliminate the need to review pilot qualifications. Ask whether an insurer considers the documented configuration and training in its offer. Only the actual proposal can tell you the terms available for the particular account.
Avoid treating the presence of automation as a substitute for an operational plan. The underwriter still needs to understand who flies, how often, where the aircraft is based and what use is proposed. Aircraft capability, pilot proficiency and policy acceptance are different subjects. Presenting each accurately gives the reviewer a more useful picture than a marketing description of the panel.
Choose the insured value with the purchase team
Discuss the requested physical damage value using the purchase price, configuration and other reliable valuation information. Identify equipment included at closing and any modifications planned later. Ask BWI how the proposed policy addresses the value and settlement basis. The number on a loan agreement is not, by itself, a complete valuation method.
An owner may also be selling another airplane. Keep the existing and incoming aircraft values separate, along with their coverage dates. If both will be owned temporarily, say so. Do not cancel an existing arrangement simply because the M700 purchase is scheduled. The timing of sale, continued operation and transfer of responsibility should be reviewed on its own facts.
Review deductibles and physical damage terms alongside the insured value. Ask about the scope of the proposed coverage, relevant exclusions and any special conditions affecting the intended operation. An annual premium comparison is incomplete if one offer uses a different value, deductible or coverage basis. Make those differences visible before choosing among proposals.
Review liability around the people and activities involved
Describe who will travel in the aircraft and why. Personal travel, company trips, shared ownership and use by related businesses can raise different questions about insured interests and contractual obligations. BWI needs the actual facts to request an appropriate review. General descriptions such as “private use” should not obscure a business arrangement that also needs to be considered.
Ask for available liability limits and any applicable sublimits to be explained. Compare the structure of the offers, not just the largest number on the first page. A requested limit remains subject to underwriting and availability. No public premium example or online checklist can promise that every first-time turbine owner will be offered the same protection.
If a lender, hangar operator or another party requires evidence, submit the request with the contract or instructions that explain it. The party’s interest should be reviewed in the correct capacity under the actual terms. A certificate is useful evidence for a stated purpose; it does not replace the policy or independently broaden its coverage.
Plan the delivery and insurance handoff together
Create a delivery outline with the expected closing date, location, ownership entity, proposed pilot and first destination. Have the transaction advisers explain when the buyer assumes the relevant responsibilities. Provide BWI the coverage start date and time requested for that arrangement. Resolve uncertainty before the aircraft moves under the new ownership plan.
Ask whether any proposed demonstration, instruction, delivery or maintenance flight needs to be addressed separately. The seller, buyer, instructor and delivery pilot may each have different responsibilities. Do not assume that the seller’s policy continues for every post-sale activity or that a hired pilot’s separate policy answers the owner’s physical damage and liability questions.
Keep a practical contingency plan. If training is delayed, a pilot becomes unavailable or an inspection changes delivery timing, contact BWI before relying on the earlier arrangement. A schedule change can affect more than convenience. The useful question is whether the proposed insurance still matches the facts and which decisions must be revisited before proceeding.
Understand the difference between maintenance support and insurance
A new-aircraft purchase may include warranty or maintenance-related benefits. Obtain the actual agreements and ask the provider what they cover, their eligibility conditions and their duration. These programs should be evaluated on their own terms. A sales description should not be used as a substitute for the agreement that governs the service.
Aircraft insurance is another contract. Ask how the proposed physical damage coverage addresses a loss under its wording, including applicable exclusions or limitations. A maintenance program’s promise to perform defined work does not establish that every resulting expense is insured. Likewise, an aircraft policy should not be assumed to function as a prepaid maintenance plan.
For an event involving damage or a possible claim, follow the policy’s reporting requirements and obtain qualified technical assistance. Keep invoices, findings and communications factual. The maintenance provider determines technical work within its role; the insurer evaluates coverage under the policy. Coordination is useful, but neither decision should be invented from the fact that the aircraft has both insurance and a support program.
Prepare the first renewal from the beginning
Keep records of completed training, approved pilot changes, flying experience and material changes in operation. These records can support the next underwriting review. Do not promise yourself a specific premium reduction after the first year. Future terms can depend on several factors, including the submission, requested coverage and the market at renewal.
Before renewal, compare actual use with the original plan. Perhaps you flew less than expected, added a regular pilot, changed the base or began longer international trips. Give BWI those facts in time to review them. The objective is an accurate continuing submission, rather than repeating last year’s assumptions because they are already written on a form.
Review value and contractual requirements as well. A different lender arrangement, significant equipment work or ownership change may require attention. Ask which evidence the insurer needs and retain its response. A well-maintained file makes the first renewal more organized even when the owner’s flying has developed beyond the initial purchase plan.
Compare two ways to handle a training delay
Imagine a first-time turbine owner whose M700 delivery date is approaching while the planned transition course has been postponed. One option is to delay both closing and delivery. Another proposed option is to close on schedule and have an experienced pilot move the aircraft while the owner completes training later. These are illustrative choices for review, not arrangements this article declares acceptable.
For a delayed transaction, ask the purchase advisers what dates and obligations need to change. Notify BWI so the requested start date and any existing quote assumptions can be reconsidered. If the owner still has another airplane, review its continuing coverage and use separately. A delay in one purchase should not create an accidental gap in the operation that is still taking place.
For an earlier closing with a different pilot, provide the pilot’s qualifications, proposed route and intended duties. Explain whether that person will conduct instruction or only deliver the airplane. Ask what happens after arrival: where the aircraft will be stored, who may move it, and what must occur before the owner begins flying it. The insurer’s response should address the actual stages rather than a vague promise that an experienced friend will help.
Compare the practical consequences after the insurance and transaction questions are answered. Availability of a pilot, course scheduling and the owner’s travel needs may influence the decision. The useful result is a plan that the responsible parties understand and can document. Avoid selecting a timeline first and then assuming the coverage must adapt to it without further review.
M700 Fury insurance questions
Is there a universal minimum flight time for M700 insurance
No single number should be treated as the requirement for every insurer and owner. Submit your actual experience and intended training plan for review. Ask BWI which terms are available and which conditions attach to the offer. Online examples can provide context but cannot approve an individual pilot or replace the policy wording.
Does experience in an M350 automatically qualify me for an M700
Experience in another airplane is part of the submission, not automatic acceptance for the new aircraft. Describe the exact models, recent flying and relevant training. Ask your training professionals about the transition and BWI about insurance conditions. Keep the differences between piston experience, turbine experience and familiarity with the specific aircraft visible.
Can I bind insurance while training remains outstanding
Ask BWI to review the actual ownership and flight plan. An insurer may consider a defined arrangement with conditions or another accepted pilot, but availability cannot be assumed. Confirm what coverage has been accepted, its effective date and which activities are permitted before operating. A quote with open requirements is not a complete delivery decision.
Will factory safety systems make the premium lower
They may be relevant information for an insurer, but no universal discount should be assumed. Provide the actual equipment and training details and compare the proposals offered for your account. Keep any manufacturer description separate from the insurer’s pricing decision. A percentage advertised elsewhere is not evidence of a credit in your proposal.
What information should I send BWI first
Start with the aircraft identity, requested value, ownership entity, planned closing date and individual pilot summaries. Add the training course, provider, dates and proposed mentor or delivery pilot. Explain the intended use, base and lender requirements. Clearly mark pending information so the insurance review can proceed with accurate expectations.
Request an M700 Fury insurance quote from BWI
Before committing to the first delivery flight, ask BWI to review the aircraft, pilot transition and ownership arrangement together. Send the facts you know and identify what remains pending. The goal is to obtain an offer that can be compared and implemented, with the relevant conditions understood before the airplane becomes your responsibility.
Request a turbine aircraft insurance review and M700 Fury quote from BWI. Ask the team to explain the available hull and liability options, pilot requirements and delivery-date evidence. The issued policy and accepted terms govern coverage; a complete submission is the practical next step toward an informed purchase decision.
Sources
Continue Reading


