
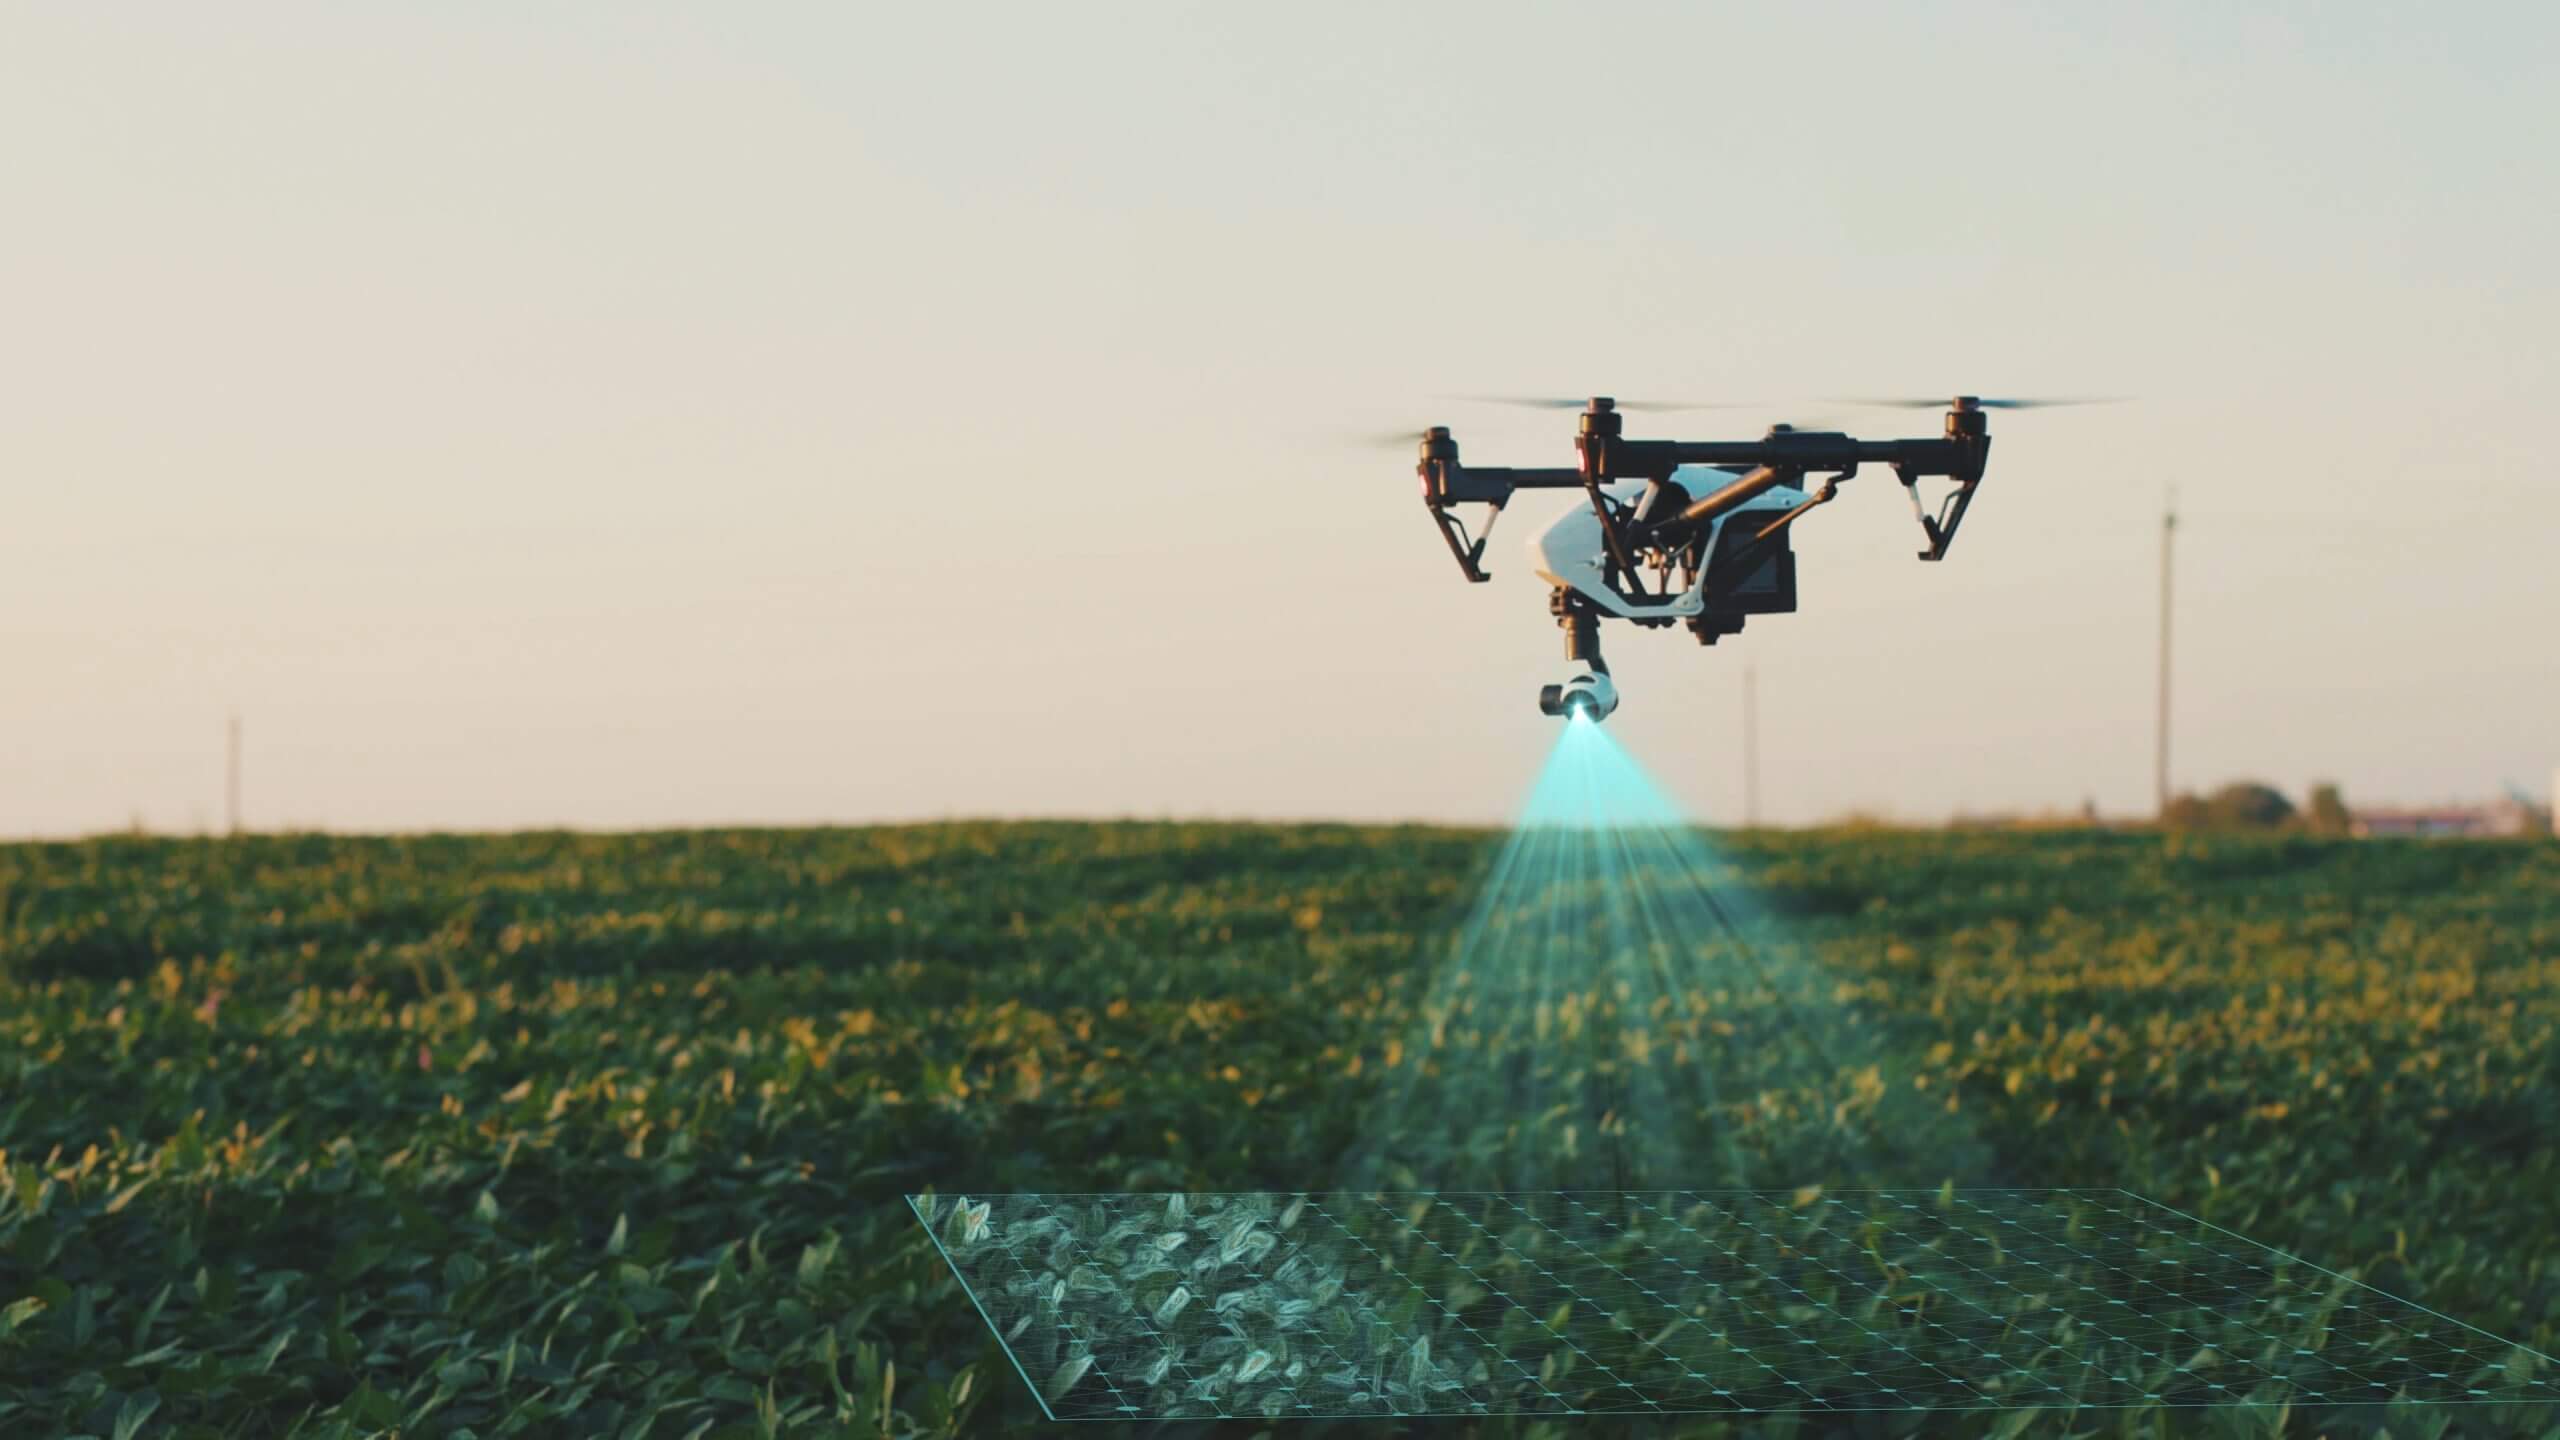
Drone water sampling insurance needs to address the collection method, specialized equipment and responsibilities after the flight. A policy accepting aerial imagery does not necessarily accept a drone lowering a sampling device into water or carrying collected material. Disclose the full process before taking the assignment, including sample custody, transport and any environmental conclusions your business supplies.
The key distinction is between operating an aircraft, collecting a physical sample and providing a professional interpretation. Each can create a different loss. A damaged payload, a collision, an allegation of contamination and an inaccurate monitoring report should not be treated as one undifferentiated drone exposure.
At BWI, we help operators present specialized work when requesting drone insurance options. Supply a clear description of your collection system and the parties responsible for handling and analysis. Get your water sampling drone insurance quote with BWI before treating a general drone certificate as approval for the project.
Explain What the Drone Actually Does
Start with the physical method. Does the aircraft carry a sealed container, lower a device on a line, land on a platform or collect measurements without touching the water? Describe what is attached to the aircraft and what happens at the sampling point. A proposal labeled environmental monitoring can conceal important differences in equipment and operation.
Identify the aircraft, payload, suspension equipment and any release mechanism. Explain the intended sample volume, supporting equipment and whether another person controls the sampling device. Give the insurer manufacturer information or a concise system description when useful. Modifications and nonstandard combinations should be disclosed accurately rather than hidden within the aircraft's original model name.
Explain where the work takes place. A contained industrial pond, open lake, flowing channel and water near operating infrastructure are different settings. Site access, recovery arrangements, nearby property and interaction with other users can change the exposure. The submission should describe these facts without claiming that a particular method is automatically safe or insurable.
Also identify what the operation does not include when that boundary matters. Collecting water is different from applying a treatment, releasing a substance or performing cleanup. If the client wants to add an activity, have it evaluated separately. An insurance explanation based on collection should not be stretched to a different mission.
Follow the Sample From Collection to the Laboratory
The flight can be a brief part of a much longer service. A sample may be sealed, labeled, stored, transported and handed to a laboratory after the aircraft has returned. Identify which of those activities your business performs. If employees carry the sample to another location, do not describe the project solely as an aerial mission.
Clarify who chooses sampling points, determines collection timing and supplies the protocol. Your company may follow a customer's instructions, design the monitoring plan or provide both collection and analysis. Those responsibilities affect what service the insurer is being asked to evaluate. Following an external protocol does not automatically remove all responsibility for your own work.
A chain of custody record helps preserve the service history. Connect the sample identifier with collection location, time, handling information and the receiving party. Use the project's applicable technical requirements and qualified guidance for the details. The insurance article cannot prescribe a universal sampling protocol for every material or environmental purpose.
Keep deviations visible. If access prevents collection at the specified location or the container cannot be delivered as planned, report the limitation through the agreed process. Substituting another sample or altering a record without clear authorization creates a different problem from simply documenting that the original task could not be completed.
Match the Insurance Question to the Possible Loss
A coverage review should distinguish physical damage, liability and professional services. The table is an exposure map rather than a coverage promise. It helps identify which contract provisions and operating facts need attention before a project begins.
The Global Aerospace drone program describes aircraft and equipment options. Its UAS specimen illustrates why equipment descriptions and policy conditions require review. Those primary materials do not establish that a particular water sampling method, pollution allegation or professional report is covered under your policy.
| Possible loss | Question to resolve | Useful supporting information |
|---|---|---|
| Drone or sampling device damaged | Which equipment and causes of loss are insured | Models, ownership, values, attachment details and recovery plan |
| Injury or damage during flight | Whether the declared operation fits liability terms | Site description, aircraft, method and people nearby |
| Contamination allegation | How pollution and related exclusions or coverage apply | Material description, handling procedure and allegations |
| Sample mishandling or inaccurate conclusion | Professional services and errors and omissions treatment | Scope, protocol, custody record and intended report use |
| Missed deadline or repeat collection | Whether specific financial expenses are addressed | Client agreement, remedy terms and actual loss facts |
Review Pollution Questions Without Assuming Environmental Coverage
The word environmental describes the work, not the protection in the insurance contract. A business monitoring water quality can still face a question about pollution exclusions or limitations. Do not assume that all contamination allegations are insured because the mission aims to measure an environmental condition.
Describe the materials involved as accurately as the project allows. Explain whether the sample is ordinary surface water, potentially contaminated material or something requiring specialized handling. Identify cleaning, storage and transport responsibilities. Unknown composition should be described as unknown, with the precautions and protocol supplied by qualified parties.
A claim could allege that a device transferred material between locations, a container leaked or handling worsened an existing condition. These are hypothetical allegations to investigate, not predictions that your business will cause a loss. The policy review needs the relevant wording and facts rather than a broad assurance that environmental monitoring is included.
Where a separate environmental liability review is appropriate, provide the whole process to the relevant insurance professional. Do not try to solve the issue by increasing an aviation liability limit alone. A larger limit cannot remove an exclusion or make an undeclared professional activity fit a different coverage grant.
Over Water Equipment Damage Is a Separate Decision
Insurance for your aircraft and sampling payload should be reviewed independently of liability to others. Confirm how the actual physical damage form treats the mission, attached equipment, water exposure and recovery circumstances. A program summary mentioning hull coverage does not settle every cause of loss or condition.
Provide supported values for removable devices and identify borrowed equipment. A sampling assembly can be essential to the operation while remaining outside an aircraft schedule's definition unless appropriately addressed. If the device belongs to a client or research partner, disclose the agreement allocating damage responsibility.
Recovery planning also deserves a practical discussion. Identify who would decide whether recovery can be attempted and which qualified resources would be used. Do not promise a recovery effort regardless of personal safety or environmental restrictions. Coverage for equipment loss, recovery expense and replacement hire must each be evaluated under the applicable contract.
Keep records of the equipment configuration used on the day of work. If the crew changes a sensor, line or collection assembly, the business should know whether that change affects the accepted description. A photograph and updated equipment record can help connect the mission file with the actual system.
A Hypothetical Expansion From Collection to Certification
Imagine a hypothetical contractor engaged to collect samples at customer selected points and deliver them to an independent laboratory. The initial agreement does not ask the contractor to interpret results. Midway through the project, the customer asks the contractor to issue a statement that the water meets a particular compliance requirement.
The flight equipment may be unchanged, but the professional service has expanded. The business would now be asked to provide a conclusion with potential third party reliance. That should trigger a review of qualifications, contractual responsibility and professional liability protection before the statement is supplied.
A useful response separates what the contractor can document from what requires another professional. The company may be able to confirm when and where samples were collected and who received them, while the laboratory or qualified environmental adviser handles interpretation. The appropriate division depends on the actual service and applicable requirements, not an insurance label.
The example shows why a sample delivery receipt and a compliance certification should not be merged casually. Keep the accepted scope and any later request in the project file. Insurance should be requested for the service you actually undertake, including changes in who is expected to rely on your work.
Coordinate Aviation Requirements, Site Permission and Contract Terms
The FAA's commercial operator information provides the small drone regulatory starting point. Aviation authority, site access and insurance acceptance remain separate decisions. A customer permission letter does not establish compliance with every applicable operational requirement, and an aviation authorization does not amend your policy.
Provide the actual operating method and any relevant approvals when requesting insurance. If the project adds dispensing or another specialized activity, obtain an appropriate regulatory assessment rather than assuming a collection approval carries over. Local access, environmental and property requirements can also need qualified review for the specific site.
Read the client agreement for the service standard, sample handling responsibilities, remedies and indemnity. A contractual promise to pay every cost of repeat testing or a delayed project may be broader than the insurance. Legal counsel can address interpretation while the coverage review identifies the obligations the proposed terms actually support.
If the customer requests insurance evidence, use the correct legal names and actual requirements. A certificate cannot create environmental liability protection or professional services coverage merely by describing the project. Keep any supported endorsements with the scope and project dates.
Prepare a Complete Sampling Project Submission
The best request follows both the aircraft and the sample. Assemble the details below and identify any decision still pending. This makes it easier to compare the real service with the proposed insurance instead of relying on a generic environmental monitoring description.
- Aircraft, payload, sampling attachment, ownership and supported equipment values.
- Collection method, site locations, operating environment and relevant permissions.
- Material description including uncertainty and qualified handling instructions.
- Responsibilities for protocol selection, cleaning, sealing, storage, transport and laboratory handoff.
- Report scope, professional conclusions and any intended third party reliance.
- Client agreement, insurance requirements, project dates and the procedure for scope changes.
Questions About Drone Water Sampling Insurance
Does Environmental Monitoring Automatically Include Water Collection?
No universal conclusion follows from that description. Monitoring can mean remote imagery or measurements without physical contact, while sampling introduces collection equipment and material handling. Explain the actual process and obtain the applicable insurance response. A policy accepting one method should not be assumed to accept every activity under the same project label.
Is the Sampling Container Part of the Drone?
That depends on the policy's property definitions and schedule. Supply the attachment details, value and ownership, including whether the device is removable or client owned. Confirm where it is insured during flight, handling and storage. Being attached for a mission does not automatically settle its treatment under every form.
What if a Laboratory Performs All the Analysis?
Identify that division in the agreement and insurance request. Your business can still have responsibilities for collection, labeling, custody and delivery even when another party interprets the results. Keep the handoff record clear and avoid adding analytical conclusions to your own report unless that expanded professional service has been appropriately evaluated.
Does Drone Liability Insurance Cover Pollution Allegations?
The actual coverage grant, exclusions, endorsements and allegations determine the answer. Do not infer pollution protection from a policy's acceptance of environmental work. Describe materials and handling so the question can be addressed directly. A separate environmental coverage review may be relevant, but availability and scope require an actual proposal.
Will Insurance Pay for Another Sampling Visit?
Do not assume that repeat work is included. A return visit could arise from equipment damage, a mishandled sample, a changed client instruction or an incomplete original service. Those facts can involve different policy provisions or no applicable protection. Compare the contractual remedy with the insurance before promising reimbursement.
Get a Water Sampling Drone Insurance Quote From BWI
At BWI, we can help you describe the aircraft, collection system and service responsibilities when requesting drone insurance options. Send the equipment list, sampling method, site information, material handling arrangements and client requirements. Explain who performs analysis and whether your business provides any environmental conclusion.
Start with our drone insurance information, then get your water sampling drone insurance quote from BWI or call 866 788 6291. Raise scope changes before the work begins. Coverage depends on the accepted terms, issued policy and endorsements; submitting a request does not bind insurance.
Continue Reading

