JetPROP insurance starts with a clear description of the converted aircraft. The original airframe model tells only part of the story. Your submission also needs the turbine conversion, installed equipment, requested insured value and experience of the pilots who will operate it.
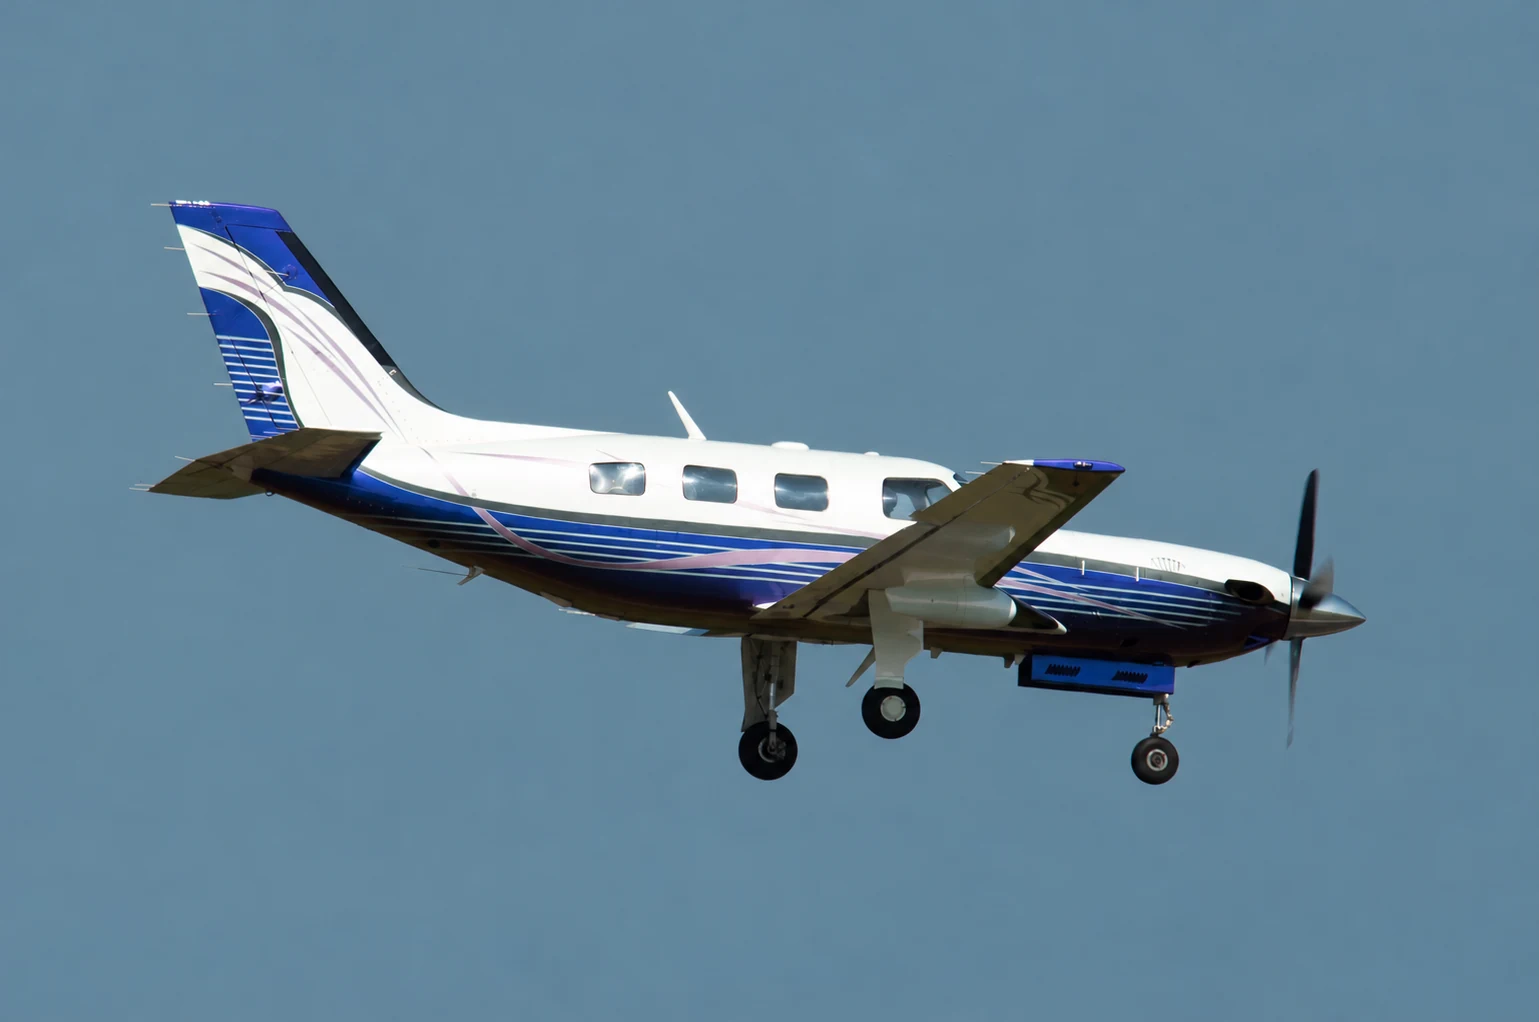
Key takeaway: Connect the aircraft’s conversion records, pilot transition plan and ownership timeline before choosing coverage. Whether you are purchasing a completed JetPROP or arranging a conversion, ask your broker to review each proposed phase and confirm the coverage and conditions that apply.
Start the conversation while you can still coordinate the purchase, shop schedule, training and delivery. BWI’s PA-46 insurance review gives you a place to discuss those facts and the questions that need answers before the aircraft changes hands or leaves the shop.
Identify the JetPROP conversion accurately
The FAA’s JetPROP supplemental type certificate covers turbine conversions of PA-46-310P and PA-46-350P aircraft. A record showing only the underlying Malibu or Mirage model can omit a material part of the configuration being insured.
Provide the original model and year, registration, conversion designation, installed engine variant and relevant conversion records. Add current avionics, propeller and other major modifications. Keep completed equipment changes separate from upgrades being considered, ordered or installed during an upcoming visit.
If an online application offers only a general PA-46 choice, provide the conversion details in its notes or separately. Avoid selecting a factory turbine model simply because that label appears closer to the installed engine. Ask the broker how the converted aircraft will be identified in the proposal and policy schedule.
Choose the right starting point for your situation
Buying a completed JetPROP and converting an airplane you already own require different preparation. Identify the situation at the start of the inquiry. The same pilot may need different arrangements before work, during shop custody and after return to service.
| Situation | Information to gather | Decision to resolve |
|---|---|---|
| Buying a completed conversion | Current aircraft specifications, conversion records, purchase terms and proposed pilots. | Coverage timing, accepted value, training and delivery arrangements. |
| Converting an owned aircraft | Existing policy, project description, shop schedule, anticipated configuration and intended flights. | How the insurance should address each phase and the completed aircraft. |
| Renewing a JetPROP policy | Current configuration, pilot updates, training, value request and changed use. | Whether renewal terms match the aircraft and operation as they now stand. |
Name one person to coordinate the information. In a purchase, that may involve the buyer and seller; during conversion, the owner and shop may hold different records. Consolidate the relevant facts without asking the broker to resolve technical discrepancies between incomplete documents.
Build a useful aircraft file beyond the listing
A sales listing can start the conversation, but the insurance submission should reflect supported aircraft facts. Gather available specifications, conversion documents, equipment records and the inspection or maintenance information requested for review. Have qualified technical professionals resolve questions about the aircraft itself.
Check that documents refer to the same registration and serial number. Note equipment differences between the listing, purchase agreement and current records. If a proposed upgrade will be completed after closing, identify that timing rather than describing the future configuration as already installed.
Give the broker a concise configuration summary with the supporting documents available. Flag unresolved information plainly. For example, if the seller is checking the exact engine designation or a modification record, record that item as pending and provide the corrected information when confirmed.
Before requesting binding, compare the final proposal with this aircraft file. An old piston description, unexplained model substitution or inconsistent value needs clarification. A correct registration alone does not settle every detail of the insured aircraft’s description.
Separate aircraft value from project expenditure
Explain the requested insured value and the information behind it. For a purchase, provide relevant transaction and configuration details. For a conversion, describe the existing aircraft, proposed work and intended completed configuration. Ask what additional valuation information underwriting needs.
Purchase price, loan balance, conversion expenditure and an agreed insurance value serve different purposes. Adding invoices to the previous hull value is not a substitute for reviewing the resulting aircraft and proposed valuation wording. Discuss significant equipment or engine changes with the broker rather than assuming they are automatically reflected.
Ask when changes in value should be reported during a project and how the requested amount is documented. Keep lender requirements visible alongside the owner’s request. When comparing offers, use the same disclosed configuration and value so a pricing difference is not simply an unrecognized difference in the aircraft being insured.
Show each pilot’s relevant experience
Prepare a current pilot summary using the application’s requested categories. Separate total flight time, recent activity, retractable-gear experience, turbine time and JetPROP experience. State the date of the figures and check prefilled entries against the pilot’s records.
Piston PA-46 experience is useful background, but report it under the aircraft actually flown. It should not be relabeled as JetPROP time. Likewise, a planned transition course or anticipated delivery flight belongs in the preparation plan until it has been completed and recorded.
Explain who will fly during the first stages of ownership. The owner, professional pilot, instructor, mentor and delivery pilot may have different responsibilities. Identify every proposed person and ask which qualifications or approvals are needed for each role under the offered terms.
Present the pilot’s actual history rather than guessing a universal minimum. If there is limited turbine experience or a gap in recent flying, describe it and the proposed preparation. The useful question is which terms, if any, are available for that pilot, aircraft and plan.
Match training to the conversion and the policy
Discuss instruction while the insurance inquiry is being prepared. Identify the provider, individual instructor, course, aircraft variant, relevant equipment and proposed dates. Ask whether the plan meets the conditions being considered before relying on it for delivery or travel.
PMOPA’s MSIP instructor framework treats JetPROP as a distinct training variant. Use that distinction when researching instruction, while confirming the proposed arrangement under your particular insurance terms. Association recognition and policy acceptance answer different questions.
If additional dual instruction or mentoring is proposed, ask who may provide it, what flying it covers and how completion is documented. Clarify when the owner may fly without the instructor or mentor and whether passenger operations have separate conditions.
Keep course completion, any supervised flying and the insurer’s response as separate records. A course reservation is not completion evidence. If the instructor or schedule changes, provide the revised plan and obtain the response before relying on the earlier arrangement.
Review a conversion project phase by phase
For an owned aircraft entering conversion, send BWI the existing policy and a written project outline. Explain the intended shop, location, expected dates, configuration changes and proposed flights. Ask how the current arrangement should be reviewed before the aircraft moves or work begins.
| Project phase | Questions for the insurance review |
|---|---|
| Arrival and shop custody | Who moves the aircraft, what activities are planned, and what coverage applies while it is at the shop? |
| Work in progress | How should value, configuration, removed components and material schedule changes be reported? |
| Ground runs and test flying | Who will perform each activity, in which aircraft configuration, and what acceptance is required? |
| Training and delivery | Which pilots and flights are accepted, and what remains required before owner operations? |
Request the relevant insurance information from the shop and other parties, then have the broker review it alongside your policy and contractual arrangements. A shop’s coverage should not be assumed to replace the owner’s insurance or answer every question about damage, custody and operations.
Give changes an explicit review point. A delay, different pilot or revised work scope can affect the assumptions behind the original inquiry. Update the facts while there is time to resolve questions rather than waiting until the airplane is scheduled to depart.
Coordinate purchase, ownership and delivery
For a completed conversion being purchased, prepare the legal owner, closing arrangements, lender requirements, proposed delivery pilot and requested coverage start. Ask transaction advisers to clarify when ownership and the relevant responsibilities transfer, then give the broker the timing needed for the insurance review.
Keep demonstration, inspection, delivery, instruction and ordinary owner flights identifiable. The people involved may differ, and an answer about one stage may not address another. Explain any period when the buyer owns the aircraft but has not completed the planned transition training.
Before relying on coverage for the handoff, obtain written confirmation of the accepted arrangement and effective date and time. Keep outstanding conditions visible. If the closing or delivery changes, contact BWI with the revised facts instead of treating the earlier proposal as an answer to every later variation.
Keep the handoff file useful after delivery
Prepare a short handoff record for the owner and anyone managing the aircraft. Identify the final configuration, accepted pilots, applicable training conditions, coverage dates and documents supporting the arrangement. Mark unresolved items separately so a delivery checklist does not imply that every owner-operating condition has been completed.
Include the people responsible for the next action. One person may be obtaining a training certificate, another confirming a pilot detail and another checking the issued policy. Record the actual response when each question is resolved. That provides continuity if a different manager or family member later helps administer the aircraft.
Store the policy, endorsements, accepted proposal and relevant written clarifications together. Ask BWI about discrepancies before assuming a brief summary replaces the contract. Keep claims-reporting instructions available as well; a future renewal inquiry is a different task from reporting an event under current coverage.
If the JetPROP replaces another airplane, describe any period when both remain owned. Identify whether the earlier aircraft will still fly, who will operate it and its expected sale date. Ask the broker to coordinate the two arrangements around the actual transactions. The arrival of the JetPROP does not, by itself, settle the coverage needed for the airplane awaiting sale.
Review the handoff record after the first planned training or operating milestone. Update the file with what actually occurred, preserving the distinction between completed activity and an earlier intention.
Compare JetPROP insurance proposals consistently
Begin with the same converted-aircraft description, requested value, policy period, pilots and intended use. Read liability limits and passenger or per-person sublimits together. Compare the physical damage basis, ordinary and special deductibles, territory, permitted activities and endorsements.
Ask how the policy addresses mechanical breakdown, wear, maintenance and any resulting damage. Insurance wording should be reviewed on its own terms; it should not be treated as an engine maintenance agreement. Put an unanswered coverage question beside the relevant provision rather than filling the gap with an aircraft sales description.
Compare the practical requirements too. Course tuition, mentor time, travel and delivery arrangements may affect which proposal is workable. Keep those expenses separate from the premium. Check selected options, disclosed fees, payment costs and the final payable amount before making the coverage decision.
Use BWI’s quote comparison worksheet to record the differences. Ask whether the response is an indication or firm terms, when it expires and what remains required. A quotation is not confirmation that coverage is in force.
A hypothetical delay that changes the insurance questions
Imagine an owner converting a piston PA-46 who has booked instruction shortly after the expected completion date. The shop schedule then changes, and the original instructor is unavailable when the aircraft will be ready. The owner is considering using another pilot to deliver it.
The useful update identifies the revised configuration, completion estimate, delivery pilot, route and training plan. The broker can ask whether the proposed arrangement is acceptable and what conditions apply after arrival. The owner also needs to decide where the aircraft will remain and who may operate it while training is pending.
If the owner instead postpones delivery, the inquiry should address continuing shop custody and the new timetable. Neither option can be evaluated solely by reusing an earlier acceptance. This hypothetical illustrates a planning process, not a customer outcome or a promise that either arrangement will be available.
Keep a concise JetPROP insurance checklist
- Identity: Original model, registration, year, conversion designation, engine and installed equipment.
- Value: Requested amount, supporting information, project changes and lender requirements.
- People: Owner, operating entity, pilot roster, instructor, mentor and delivery arrangements.
- Preparation: Accurate pilot records, completed instruction and clearly labeled future training.
- Operation: Use, home base, storage, destinations and any unusual or project-related activity.
- Timing: Purchase or project dates, requested coverage start and unresolved conditions.
Keep one dated version of the summary and explain corrections when sending updates. Ask BWI to review your JetPROP insurance needs using the aircraft and operating plan you actually expect to have.
Frequently asked questions about JetPROP insurance
Can I use the Malibu or Mirage model from the registration?
Provide the documented original model along with the turbine conversion and installed engine details. If a form cannot capture the conversion, add an explanation or contact the broker. The aircraft description should communicate the current configuration rather than leave underwriting to infer it.
Does piston PA-46 time count as JetPROP time?
Report experience in the aircraft actually flown. Piston PA-46 time belongs in the background submitted for review, but should not be relabeled as converted-aircraft time. Ask how the application wants each category reported if the requested wording is unclear.
Can I discuss coverage before signing a purchase agreement?
Yes. Share your experience, candidate aircraft and expected use. Identify tentative facts and ask what further information is needed. Confirm final terms against the actual aircraft, ownership, requested coverage and training plan before relying on them for a purchase or delivery.
Does the conversion shop’s insurance protect everything?
Request the relevant evidence and contractual information for review. Ask how the owner’s and shop’s arrangements address the proposed work and activities. A certificate or statement that the shop is insured does not independently answer every coverage question for your aircraft.
Should I increase hull value by the conversion invoice?
Discuss the resulting aircraft and requested value with supporting information. Expenditure, market information and the policy’s valuation wording address different issues. Ask what value should be presented and when changes need to be reported rather than simply adding invoices to the prior limit.
Can a delivery pilot fly while my training is incomplete?
Submit the proposed pilot, duties, flight and post-delivery plan for review. Ask what arrangement, if any, can be accepted and what conditions remain for your own flying. Another pilot’s experience does not automatically establish coverage for every stage of the handoff.
Is a conversion approval also insurance approval?
The aircraft’s technical records and its insurance arrangement serve different purposes. Provide the conversion details to the broker and confirm the offered terms for the completed configuration, pilots and use. Keep technical signoffs with qualified aviation professionals and insurance acceptance with the applicable documents.
What should I update at the first renewal?
Provide actual configuration, completed training, current pilot experience, changes in use and the requested value. Compare the new terms with the expiring policy. A year of ownership supplies updated facts for review; it does not guarantee a particular change in premium or conditions.
Bring the conversion and insurance plans together
Send BWI the aircraft specifications, conversion details, pilot history and training plans. Include the current policy when available and the purchase, project or renewal date driving the decision. Identify open items so the next conversation can resolve them.
Request a JetPROP insurance review through BWI’s PMOPA page.
Continue Reading