

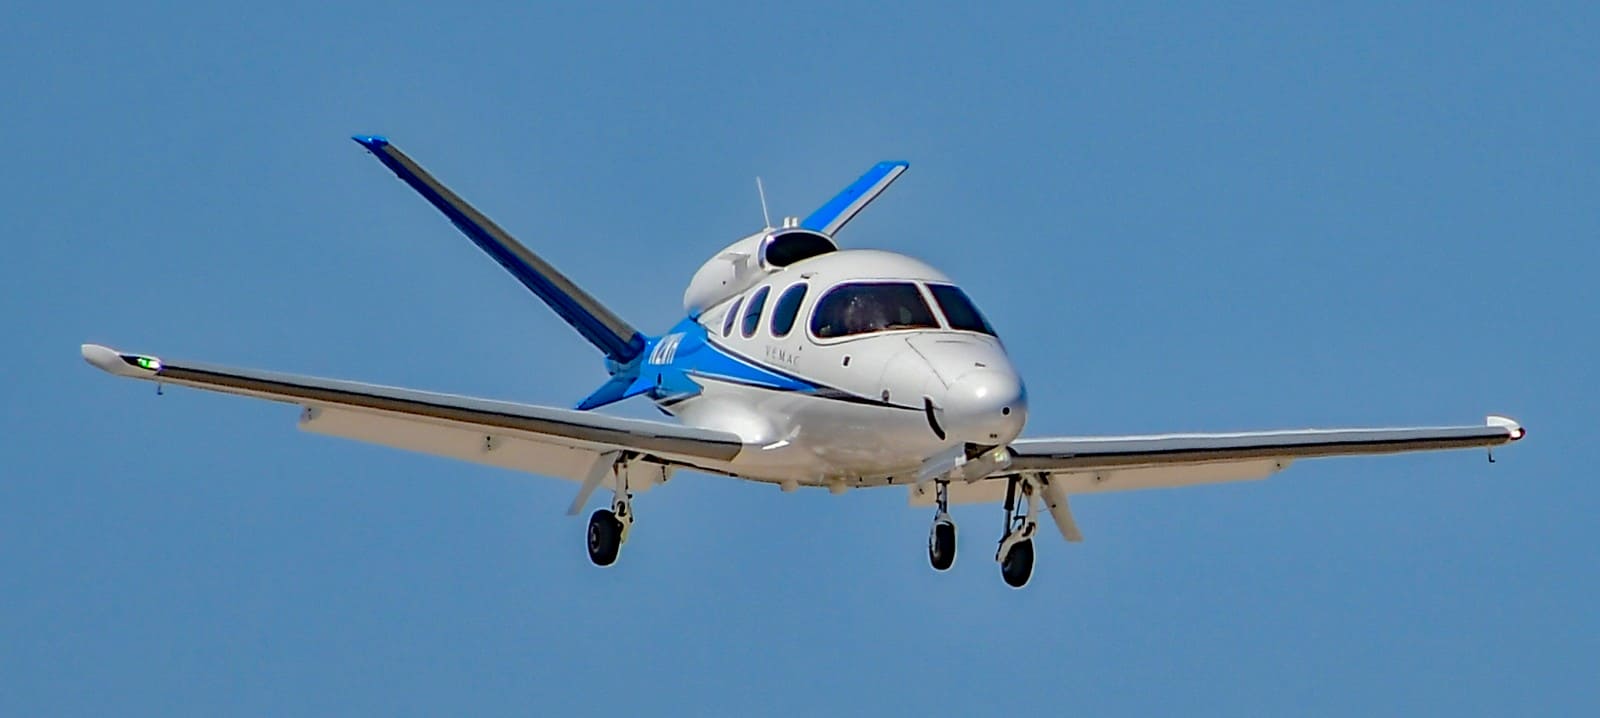
Cirrus SF50 G2 Vision Jet N2WH at North Las Vegas Airport in June 2025. Aircraft context only; pilot employment, owner identity and BWI customer status are not represented. Photo Tomás Del Coro, CC BY-SA 4.0. Resized without cropping; derivative under the same license. Photo source License
You can plan Vision Jet ownership around a professional pilot without planning to fly the aircraft yourself. The insurance submission should explain that arrangement from the beginning. The owner, operating entity, employed captain, relief pilot and aircraft manager can have different roles, and a quote prepared for an owner-pilot may not accurately describe them.
For a nonflying SF50 owner, the useful starting point is a clear account of who owns the jet, who operates it, who flies it and how it will be used. BWI can discuss that information alongside the aircraft value, liability limits and proposed policy conditions. Hiring an experienced pilot is relevant to the submission, but it does not by itself establish coverage or a particular premium.
This guide focuses on owners using employed or contracted professional pilots for their Vision Jet. It explains how to organize the insurance conversation before purchase, at renewal and when a pilot changes. Owners who intend to fly should also review BWI’s separate Vision Jet training guide; a passenger-only ownership plan requires different application details from a pilot transitioning into the cockpit.
Start with ownership and actual aircraft use
Identify the legal entity buying the aircraft and the people or organizations that will use it. A family-owned LLC, an operating company and an individual owner may all describe their travel as private, but their documents and relationships can differ. Give BWI the actual proposed ownership name instead of only the family surname or a familiar business name.
Explain the trip pattern in ordinary language. Describe family travel, employee transportation, customer or guest travel, typical destinations and expected annual flying. Identify any proposed leasing, sharing, reimbursement or third-party use. These details help the insurance team ask the right questions; a broad label such as business and pleasure should not substitute for an accurate description of the operation.
If the arrangement includes aircraft management, provide the agreement or a draft. Explain who hires pilots, schedules flights, arranges maintenance and communicates with the insurer. The management company’s involvement should be visible in the submission. Ownership structure, operating responsibility and insured status should be reviewed together before the owner assumes a proposal reflects the entire arrangement.
Explain that the owner will not act as a pilot
An application may request information about both ownership and pilots. Answer those sections according to the actual roles. A nonflying owner should not be presented as the pilot merely because the owner signs the application. Conversely, if an owner expects to begin training later, disclose that intention rather than treating it as an unrelated future decision.
Keep the initial operating plan precise. For example, an owner might propose that a named professional captain conduct all flights, with a separately identified relief pilot available for scheduling conflicts. That is a hypothetical structure, not an insurer-approved arrangement. It gives BWI a more useful starting point than a statement that any qualified pilot may fly the jet.
Ask how the policy describes permitted pilots and whether any limitations apply to the nonflying owner’s involvement. The owner should also understand who is authorized to request changes. A busy family office may delegate administration, but the insurer still needs accurate information and appropriate instructions. Record the agreed communication process with the policy documents.
Build a complete submission for the primary captain
Prepare the pilot information requested by BWI and the proposed insurer. This may include certificates and ratings, SF50 experience, other turbine experience, recent flying, training records and relevant loss history. Use records that can be supported. A professional resume is helpful context, but it may not contain every figure or declaration the underwriting application requires.
Separate total flight time from experience in the aircraft being insured. A long professional career does not describe how recently the pilot has flown a Vision Jet or completed relevant training. If records need clarification, identify that uncertainty early. Avoid converting an estimate into an exact number simply to complete a form quickly.
Send updated information when the pilot completes additional training or gains relevant experience during the quote process. Ask whether the update changes any outstanding conditions. Training booked for next month is different from training already completed and documented. The final proposal should make clear which conditions have been met and which must be satisfied before a particular flight or policy period.
Review training requirements without assuming a universal rule
Cirrus describes a dedicated Vision Jet type-rating program at its Vision Center. Manufacturer training information helps an owner understand the aircraft’s training ecosystem. It does not replace the insurer’s written pilot conditions or establish that every training provider, course or completion date will be accepted for a particular proposal.
Ask BWI to obtain the actual training requirement for each proposed pilot. The review should address the accepted course or provider, timing, recurrent expectations and any additional conditions. If a captain already holds the relevant rating, ask what evidence the insurer wants now. A rating and an insurance training requirement answer related but different questions.
Do not budget around an assumed training discount or an internet minimum-hours figure. Underwriting decisions depend on the submitted risk and available terms. Instead, build the acquisition timeline around confirmed requirements. If training cannot be completed before closing or delivery, resolve the proposed ground and flight arrangements before relying on a hoped-for exception.
Arrange relief pilots before the primary captain is unavailable
The first scheduling problem often reveals a weakness in an otherwise carefully organized ownership plan. A captain can be ill, on leave or committed elsewhere when a trip arises. Ask about backup pilots during the initial insurance review. Waiting until the day before departure can leave too little time to obtain a considered underwriting response.
A relief pilot should be reviewed against the actual policy wording. Ask whether the person must be individually named or can qualify under another permitted-pilot provision, and confirm any training or experience conditions. Permission from the owner, a manager’s recommendation and a pilot’s certificate do not independently establish acceptance under the owner’s insurance.
Keep a current roster showing each pilot’s approved role and relevant conditions. If the policy distinguishes pilot in command from other crew roles, record that distinction rather than labeling everyone approved. This administrative record supports scheduling; it does not override the policy. Any uncertain or expired item should be referred for review before assigning the pilot.
Understand the difference between a named pilot and an insured party
A person can be permitted to operate an aircraft without having the same insured status as its owner. Review the policy definitions and endorsements rather than assuming a named-pilot entry resolves every liability question. Ask how the employed captain, independent contractor and management company are treated under the proposed coverage.
The same distinction matters when a pilot supplies evidence of separate insurance. A contractor’s policy may serve a different purpose and contain its own exclusions or limitations. Ask how the arrangements interact, including any relevant subrogation or contractual provisions. A certificate showing that a policy exists is not a substitute for reviewing the requested protection.
Provide any pilot-services agreement before promises are made about additional insured status, indemnity or waivers. BWI can discuss the insurance implications, while qualified counsel should review the legal obligations. The owner should know which requests have been accepted by an insurer and which remain unresolved. Contract language cannot be assumed to amend an aircraft policy.
Compare the principal ownership arrangements
| Proposed arrangement | Information to include |
|---|---|
| Owner with employed captain | Owning and operating entities, captain records and employee exposures |
| Owner with contracted pilot | Service agreement, pilot records and replacement arrangements |
| Professionally managed aircraft | Management contract, responsibilities and requested insured parties |
| Relief or delivery pilot | Specific role, experience, training and approval process |
| Owner begins flight training | Revised operating plan and insurer conditions before participation |
An employed captain, a contracted pilot and a management company can each be part of an ownership plan. The insurance submission needs the details of the arrangement actually selected. The label alone does not determine coverage. Identify the contracting parties, the services provided and the authority each party exercises over aircraft use and administration.
For an employed captain, discuss employee-related insurance questions separately from the aircraft policy. For a contractor, provide the service agreement and describe backup arrangements. For a managed aircraft, include the management responsibilities and proposed insured entities. These are starting points for review, not a statement that one structure is automatically safer, less expensive or fully covered.
If the arrangement changes after binding, notify BWI before assuming the existing terms continue to fit. Moving from an employed captain to a management company can change more than the pilot’s name. New entities, contracts, locations or uses may become involved. Treat the revised operating description as a submission update rather than an informal administrative note.
Choose liability limits around the people and operation
Discuss who normally travels in the aircraft and what liability limits are being requested. Family members, employees, guests and customers may raise different practical questions for the owner. Review the quoted liability wording, passenger limitations, exclusions and defense provisions. The headline limit should not be read in isolation from the conditions that govern it.
Ask whether the proposed limit is subject to a per-passenger limitation and how any aggregate or other restriction applies. If higher limits or different structures are important, request a specific discussion of availability. Do not assume a professional captain makes a particular limit available or that another owner’s policy can be replicated for your aircraft.
Coordinate the aviation review with the owner’s other advisers. Personal umbrella, business liability and employment-related policies may address different interests or exclude aviation exposures. Ask the relevant insurance professionals to explain the interaction. Avoid treating a substantial general insurance portfolio as evidence that all aviation liabilities have already been addressed.
Set the hull value using the actual aircraft
Provide the aircraft’s registration or identifying details, model year, configuration, purchase information and proposed insured value. Explain significant avionics, interior or other equipment changes. Current Cirrus marketing describes the G3 Vision Jet, but a submission for an earlier SF50 should accurately reflect that individual aircraft. A generation nickname should not replace the aircraft records.
Ask how the proposal values a total loss and handles a partial loss, including deductibles and applicable conditions. Financing documents may contain insurance requirements that need separate attention. Discuss the lender’s exact name and requested status early enough to resolve discrepancies before closing. A purchase contract value and the policy’s valuation provisions should be compared rather than assumed identical.
Review the value again at renewal and after material changes. The appropriate discussion is not limited to whether the aircraft’s asking price has moved. Equipment, ownership, financing and available policy terms can change as well. Keep the final agreed description and endorsements with the aircraft’s insurance records so later administrators can see what was actually bound.
Coordinate closing delivery and the first professional flight
Create a timeline identifying closing, transfer of risk, insurance effective time, delivery arrangements and the first planned flight. Give BWI the purchase and lender requirements that affect that sequence. The owner should receive written confirmation of the coverage being arranged before relying on it. A quote request or an indication of interest is not evidence that coverage is in force.
Identify the delivery pilot and the purpose of any movement before closing. A seller’s demonstration flight, a ferry after purchase and an owner’s first trip can involve different parties and responsibilities. Do not assume that acceptance of the long-term captain settles the insurance position for every earlier movement. Describe each arrangement that needs review.
If the jet will remain on the ground while training, maintenance or paperwork is completed, explain that plan. Ask what coverage is proposed during that period and what must happen before flight. A ground-only arrangement should never be treated as permission to fly. Keep the release from any insurance restriction separate from the aircraft’s maintenance and operational approvals.
Keep private ownership and charter proposals distinct
Tell BWI about any plan to make the aircraft available to others or receive payment connected with its use. The FAA publishes guidance for owners, pilots and operators about air charter and operational responsibility. The legality of an arrangement and the policy’s permitted use require their own review; neither is settled by calling the aircraft privately owned.
Hiring a professional pilot should not be used as the sole basis for classifying the operation. Describe the actual travel, agreements and financial arrangements to qualified aviation advisers. If charter or other commercial activity is contemplated, have the appropriate specialists assess it before flights begin. An insurance discussion does not grant operating authority.
Ask for a coverage review when the use changes, even if the aircraft and captain remain the same. A plan developed for one owner’s travel may not describe a later arrangement involving third parties. Written confirmation of a change is more useful than assuming a broad business-use phrase covers every future activity.
Manage maintenance and trips without confusing separate protections
The pilot or manager may arrange service visits, but the owner should still know how insurance questions are handled during maintenance. Identify extended storage, trips to another location and any post-maintenance flight that requires a different pilot. Ask whether those details affect the current policy rather than assuming ordinary trip approval answers them.
Cirrus describes JetStream as a service and support program with specified maintenance-related benefits. Review the actual program agreement separately from aircraft insurance. Program participation is not a substitute for reading the insurance proposal, and this guide does not establish what a particular enrollment includes. Keep warranties, service programs and insurance documents available to the people administering the aircraft.
If a loss or allegation occurs, contact BWI and follow the applicable policy’s reporting instructions. Preserve relevant information and seek advice before making commitments about payment or responsibility. A manager can assist with administration, but the owner should understand who is responsible for reporting and following up. Do not assume a maintenance notification also notifies an insurer.
Build an annual insurance review for a professionally flown SF50
Before renewal, update the aircraft description, insured value, use, locations and pilot roster. Confirm that the records include the most recent training and any changes in contracts or management. Use the prior year’s submission as a checklist, not as proof that every fact remains correct. Ask administrators to identify changes explicitly rather than answering no changes by habit.
Compare renewal proposals using the same facts and requested limits. Record differences in deductibles, pilot requirements, passenger limitations, exclusions and endorsements. A lower premium may reflect different terms, while a higher premium alone does not explain the reason for the change. Ask BWI to discuss the available proposals in the context of the complete operating arrangement.
Maintain a short list of unresolved items with an owner for each follow-up. A pending relief-pilot request, lender endorsement or contract review should stay visible until confirmed. This process helps a family office or company administrator coordinate the work without claiming expertise in every policy provision. The final decision should rely on the actual terms being offered.
Frequently asked questions
Can I request Vision Jet insurance if I am not a pilot
Yes, explain that you will be a nonflying owner and provide the proposed professional-pilot arrangement for underwriting review. The owner does not need to be described as the pilot simply to complete the submission. Availability, price and conditions depend on the actual risk and insurer response. Ask BWI what information is needed for your ownership structure and intended use.
Will hiring a high time pilot guarantee a lower premium
No particular premium follows automatically from the pilot’s total time. The insurer reviews the submission and proposed terms, including the aircraft, use, pilot experience and training information requested. Ask for a current quote based on the actual captain. Avoid treating a price quoted for another owner or a different pilot as a budget commitment for your jet.
Can my captain choose a replacement pilot without telling BWI
Check the policy’s permitted-pilot provisions and any required approval process first. An experienced replacement may still need individual review or documentation. Ask who can request changes and how acceptance will be confirmed. Do not let a scheduling decision stand in for the insurance review required by the proposed policy.
Does the management company policy automatically protect the aircraft owner
Do not assume that it does. Ask which policy addresses the aircraft and how the owner, operating entity, pilots and manager are treated. Review the actual contract, policy definitions and endorsements. A management agreement or certificate can identify a relationship without establishing the full protection the owner expects.
Request a Vision Jet insurance review from BWI
Bring BWI the proposed ownership name, aircraft details, intended use, pilot records and any management or pilot-services agreements. Explain that you are a nonflying owner if that is the plan. Include the primary captain and relief-pilot arrangements so the discussion reflects the way your Vision Jet will actually operate.
Start with BWI’s Vision Jet insurance page or call 800-666-4359. Ask the team to review available terms, pilot conditions, liability limits and the insurance timing for closing or renewal. Obtain written confirmation of coverage and effective dates before relying on an arrangement. Your aircraft deserves a submission as carefully organized as the people and services supporting it.
Sources and related resources
Official Cirrus Vision Jet and training information
Continue Reading


