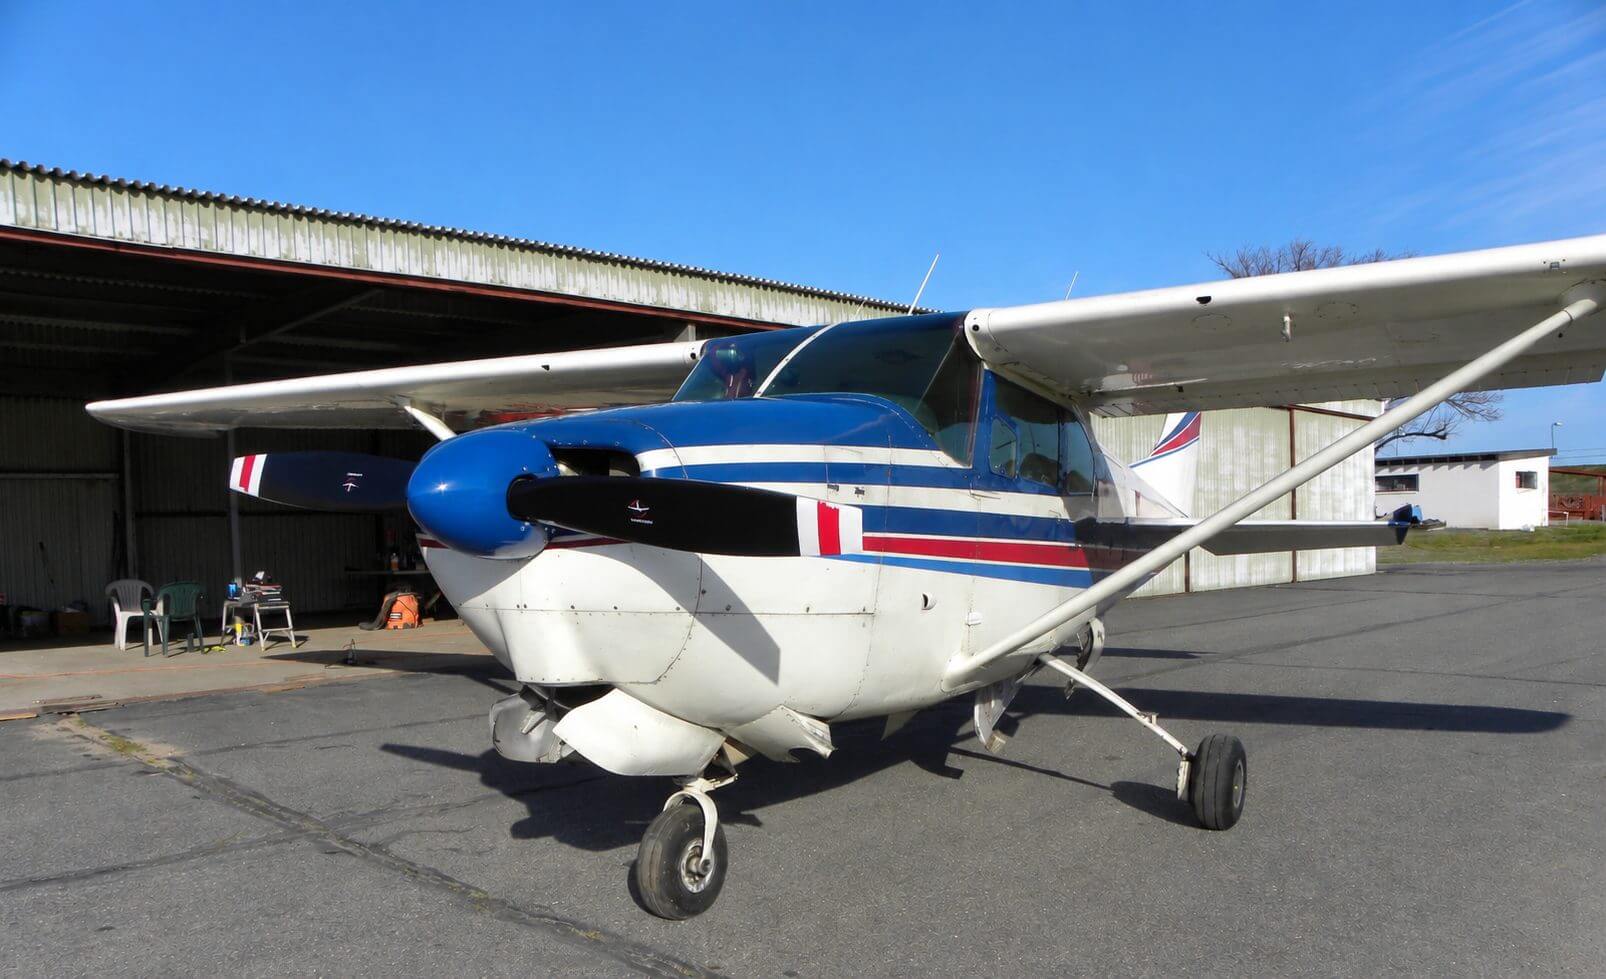
The Cessna 210 is one of the most capable owner-flown transportation aircraft ever built.
It is also one of the aircraft categories that receives significantly more underwriting scrutiny than the average fixed-gear aircraft.
Many aircraft owners are surprised to learn that insurance companies often spend far more time evaluating the pilot than evaluating the aircraft itself.
Why can one Cessna 210 owner receive multiple competitive insurance quotes while another owner struggles to obtain favorable terms?
The answer is simple.
Insurance companies are not just evaluating the aircraft.
They are evaluating the entire risk.
At BWI Aviation Insurance, we work with aircraft owners across the country and help pilots compare coverage through leading aviation insurance carriers.
After reviewing thousands of aviation insurance submissions over the years, one thing becomes very clear:
For complex, high-performance aircraft, pilot qualifications often matter more than the aircraft itself.
Understanding how underwriters evaluate risk can help position you for stronger coverage options, increased carrier competition, and potentially lower insurance costs.
Get Your Aircraft Insurance Quote With BWI Today>>
The First Thing Underwriters Evaluate Is The Pilot
Many aircraft owners assume insurance companies spend most of their time evaluating the aircraft.
In reality, underwriters often spend significantly more time evaluating the pilot.
Consider these two examples.
Pilot A owns a P210.
He has:
- 3,000 hours total time
- Instrument rating
- 1,000 hours retractable gear
- 500 hours in Cessna 210 aircraft
- Annual recurrent training
- No claims
- 150 hours flown last year
Pilot B owns the same aircraft.
He has:
- 500 hours total time
- No instrument rating
- 25 hours retractable gear
- 10 hours in a Cessna 210
- No recurrent training
- Limited recent flight activity
Those pilots represent very different risks.
The aircraft didn’t change.
The pilot did.
That difference often has a greater impact on insurance pricing than the aircraft itself.
Retractable Gear Experience Is One Of The Most Important Factors
Few underwriting factors carry more weight than retractable gear experience.
Insurance companies understand that complex aircraft require:
- Additional cockpit management
- Different emergency procedures
- Greater systems knowledge
- Higher workload operations
As a result, underwriters carefully review:
- Total retractable gear time
- Recent retractable gear activity
- Complex aircraft experience
- Training history
A pilot with substantial retractable gear experience often receives significantly stronger underwriting consideration.
Time In A Cessna 210 Matters
After reviewing retractable gear experience, underwriters often focus on time in make and model.
For Cessna 210 owners, this can be a major factor.
Insurance companies know aircraft-specific experience matters.
A pilot with hundreds of hours in a 210 generally presents a different risk than someone transitioning into the aircraft for the first time.
Even highly experienced pilots often receive additional underwriting review when moving into a new aircraft type.
Instrument Ratings Carry Significant Weight
One of the most valuable qualifications a 210 owner can possess is an instrument rating.
Insurance companies consistently favor instrument-rated pilots.
Why?
Because the rating demonstrates:
- Additional training
- Better weather decision making
- Greater proficiency
- Stronger commitment to aviation safety
The 210 has become one of the most popular owner-flown transportation aircraft in general aviation.
Many owners routinely fly:
- Business trips
- Family vacations
- Long cross-country flights
- Multi-state travel
- Weather-sensitive missions
Insurance companies know this.
Instrument-rated pilots often receive stronger underwriting consideration because they are viewed as better prepared for those missions.
Recent Flight Activity Matters More Than Many Owners Realize
One of the biggest surprises for pilots is how much underwriters care about recent activity.
Insurance companies understand that proficiency is perishable.
A pilot who has:
- 4,000 total hours
but only flew:
- 10 hours last year
may create more concern than a pilot with:
- 1,200 total hours
who flew:
- 120 hours recently
Underwriters often review:
- Hours flown in the past 12 months
- Recent instrument experience
- Recent 210 experience
- Overall recency of activity
Consistent flying creates confidence.
And confidence creates competition among insurance carriers.
Turbocharged Aircraft Receive Additional Attention
Models such as:
- T210
- Turbo Centurion
introduce additional underwriting considerations.
Insurance companies often evaluate:
- Turbocharged aircraft experience
- High-altitude operations
- IFR proficiency
- Mountain flying experience
Because of this, underwriters often pay closer attention to:
- Aircraft-specific training
- Turbocharged experience
- Operational history
Qualified pilots generally continue to find strong carrier interest.
Get Your Cessna 210 Insurance Quote With BWI>>
Pressurized Aircraft Receive Even More Scrutiny
The P210 occupies a unique position in general aviation.
Insurance companies may evaluate:
- Pressurized aircraft experience
- High-altitude operations
- Oxygen systems knowledge
- IFR operational history
- Advanced systems training
Pressurized aircraft create additional complexity.
As a result, underwriters frequently require stronger pilot qualifications.
Claims History Is Still King
Nothing influences underwriting decisions more consistently than claims history.
Insurance companies carefully review:
- Previous claims
- Loss frequency
- Loss severity
- Recency of losses
Pilots with clean records often benefit from:
- Better pricing
- More carrier options
- Greater underwriting flexibility
A claim does not automatically make insurance difficult.
However, it frequently generates additional questions and underwriting scrutiny.
Insurance companies view prior losses as one of the strongest predictors of future outcomes.
Aircraft Value Has Become Increasingly Important
One of the biggest trends affecting Cessna 210 owners today is rising aircraft values.
Consider the range of values currently seen within the market.
A standard Centurion may be insured for:
- $125,000
- $250,000
A turbocharged aircraft may be insured for:
- $400,000
- $600,000
A highly upgraded pressurized aircraft may be insured for:
- $800,000
- $1,000,000+
The insurance company’s exposure changes dramatically as aircraft value increases.
As a result, premiums often increase even when the pilot remains exactly the same.
Modern Avionics Can Influence Underwriting
Today’s Cessna 210 aircraft frequently include sophisticated avionics systems.
Popular upgrades include:
- Garmin GTN navigators
- Garmin G500 TXi displays
- Garmin GI 275 instruments
- Garmin autopilots
- ADS-B systems
- Engine monitoring equipment
These upgrades often improve both safety and aircraft value.
Many underwriters view modern avionics favorably because they improve situational awareness and reduce operational risk.
However, increased hull value may also increase premium.
Training Creates Confidence
Few things create underwriting confidence like training.
Insurance companies consistently reward pilots who participate in:
- Flight reviews
- Recurrent training
- FAAST programs
- Safety seminars
- Transition training
- Cessna 210-specific training
Training reduces uncertainty.
And underwriters dislike uncertainty.
Pilots who actively invest in proficiency often receive stronger underwriting consideration than those who simply meet minimum FAA requirements.
Aircraft Usage Matters
Insurance companies also evaluate how the aircraft is used.
Common underwriting questions include:
- Personal use?
- Business use?
- IFR operations?
- Long cross-country travel?
- Family transportation?
- Mountain flying?
Different missions create different risk profiles.
Understanding how the aircraft is operated helps underwriters evaluate exposure more accurately.
What The Best Cessna 210 Risks Have In Common
After reviewing thousands of Centurion insurance applications, certain patterns consistently emerge.
The strongest insurance risks often have:
- Instrument ratings
- Significant Cessna 210 experience
- Significant retractable gear experience
- Clean claims histories
- Annual recurrent training
- Strong recent flight activity
- Accurate logbooks
These characteristics create confidence among insurance companies.
And confidence often leads to better insurance outcomes.
Why The Cessna 210 Remains Attractive To Insurance Companies
Insurance companies generally like experienced Cessna 210 operators.
The aircraft offers:
- Extensive operating history
- Strong transportation capability
- Proven reliability
- Large owner community
- Broad maintenance support
Combined with qualified pilots, those characteristics create attractive insurance risks.
This is one reason the Centurion remains one of the most respected owner-flown aircraft ever built.
Why Thousands Of Aircraft Owners Trust BWI
BWI Aviation Insurance has helped thousands of aircraft owners secure coverage for their aircraft.
Whether you fly a 210, T210, or P210, our team understands the underwriting factors that influence pricing and carrier appetite.
We work with leading aviation insurance carriers and help aircraft owners compare options based on their specific aircraft, experience level, and mission profile.
Final Thoughts
Many Cessna 210 owners assume insurance pricing is based primarily on the aircraft.
The reality is very different.
Underwriters spend much of their time evaluating the pilot.
Retractable gear experience, Cessna 210 experience, instrument proficiency, recent flight activity, training history, claims history, aircraft value, and operational discipline all play major roles.
The good news is that many of those factors are within your control.
Understanding how insurance companies evaluate risk can help you become a stronger insurance prospect, improve your long-term insurability, and potentially secure better coverage and pricing for years to come.
bwifly.com / 800-666-4359
Continue Reading