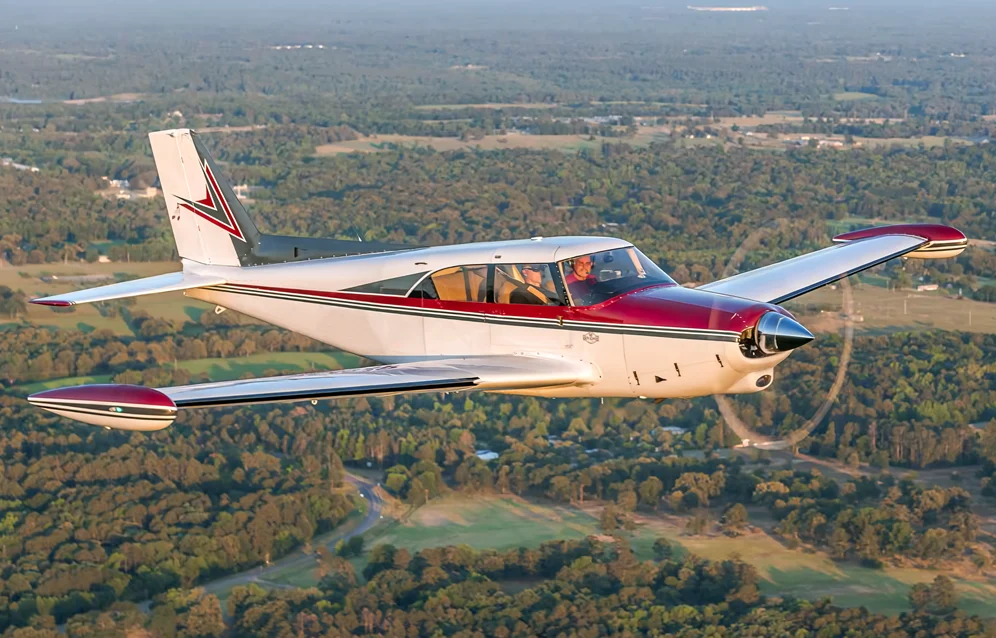
The Piper PA-24 Comanche is one of the most respected high-performance piston singles ever built.
It is also an aircraft that receives a different level of underwriting scrutiny than many basic training and recreational aircraft.
Many owners are surprised to learn that insurance companies often spend far more time evaluating the pilot than evaluating the aircraft itself.
Why can one Comanche owner receive multiple competitive insurance quotes while another owner struggles to obtain favorable terms?
The answer is simple.
Insurance companies are not just evaluating the aircraft.
They are evaluating the entire risk.
At BWI Aviation Insurance, we work with aircraft owners across the country and help pilots compare coverage through leading aviation insurance carriers.
After reviewing thousands of aviation insurance submissions over the years, one thing becomes very clear:
For high-performance retractable-gear aircraft, pilot qualifications often matter more than the aircraft itself.
Understanding how underwriters evaluate risk can help position you for stronger coverage options, increased carrier competition, and potentially lower insurance costs.
Get Your Aircraft Insurance Quote With BWI Today>>
The First Thing Underwriters Evaluate Is The Pilot
Many aircraft owners assume insurance companies spend most of their time evaluating the aircraft.
In reality, underwriters often spend significantly more time evaluating the pilot.
Consider these two examples.
Pilot A owns a PA-24-260C.
He has:
- 2,500 hours total time
- Instrument rating
- 700 hours in Comanches
- Annual recurrent training
- No claims
- 120 hours flown last year
Pilot B owns the same aircraft.
He has:
- 350 hours total time
- No instrument rating
- 15 hours in type
- No recurrent training
- Limited recent flight activity
Those pilots represent very different risks.
The aircraft didn’t change.
The pilot did.
That difference often has a greater impact on insurance pricing than the aircraft itself.
Total Flight Time Still Matters
One of the first numbers underwriters review is total flight time.
There is no magic number.
However, experience matters.
Insurance companies understand that experienced pilots have generally encountered:
- More weather situations
- More operational challenges
- More aircraft system issues
- More real-world decision-making opportunities
A pilot with 2,000 hours generally presents a different risk profile than a pilot with 200 hours.
This does not mean lower-time pilots cannot obtain excellent coverage.
It simply means additional underwriting scrutiny may occur.
Time In A Comanche Matters
After reviewing total flight time, underwriters often focus on time in make and model.
For Comanche owners, this can be a major factor.
Aircraft commonly evaluated include:
- PA-24-180
- PA-24-250
- PA-24-260
- PA-24-260B
- PA-24-260C
- Turbo Comanche
- PA-24-400
Insurance companies know aircraft-specific experience matters.
A pilot with hundreds of hours in a Comanche generally presents a different risk than someone transitioning into the aircraft for the first time.
Even highly experienced pilots often receive additional underwriting review when moving into a new aircraft type.
Instrument Ratings Carry Significant Weight
One of the most valuable qualifications a Comanche owner can possess is an instrument rating.
Insurance companies consistently favor instrument-rated pilots.
Why?
Because the rating demonstrates:
- Additional training
- Better weather decision making
- Greater proficiency
- Stronger commitment to aviation safety
The Comanche has become one of the most popular owner-flown transportation aircraft in general aviation.
Many owners routinely fly:
- Business trips
- Family vacations
- Long cross-country flights
- Multi-state travel
- Weather-sensitive missions
Insurance companies know this.
Instrument-rated pilots often receive stronger underwriting consideration because they are viewed as better prepared for those missions.
Retractable Gear Experience Matters
The Comanche is a retractable-gear aircraft.
Insurance companies understand that retractable-gear aircraft historically generate certain types of claims, including:
- Gear-up landings
- Gear collapse incidents
- Improper gear operation
Because of this, underwriters often pay closer attention to:
- Retractable-gear experience
- Aircraft-specific training
- Time in type
- Transition training
Qualified pilots generally continue to find strong carrier interest.
Recent Flight Activity Matters More Than Many Owners Realize
One of the biggest surprises for pilots is how much underwriters care about recent activity.
Insurance companies understand that proficiency is perishable.
A pilot who has:
- 3,000 total hours
but only flew:
- 10 hours last year
may create more concern than a pilot with:
- 1,000 total hours
who flew:
- 100 hours recently
Underwriters often review:
- Hours flown in the past 12 months
- Recent instrument experience
- Recent Comanche experience
- Overall recency of activity
Consistent flying creates confidence.
And confidence creates competition among insurance carriers.
Get Your Piper Insurance Quote With BWI>>
Claims History Is Still King
Nothing influences underwriting decisions more consistently than claims history.
Insurance companies carefully review:
- Previous claims
- Loss frequency
- Loss severity
- Recency of losses
Pilots with clean records often benefit from:
- Better pricing
- More carrier options
- Greater underwriting flexibility
A claim does not automatically make insurance difficult.
However, it frequently generates additional questions and underwriting scrutiny.
Insurance companies view prior losses as one of the strongest predictors of future outcomes.
Turbo Comanche Experience Matters
Turbocharged Comanches often receive additional underwriting attention.
Insurance companies may evaluate:
- Turbocharged aircraft experience
- High-altitude operations
- IFR proficiency
- Cross-country flying habits
Again, the issue is rarely the aircraft itself.
The issue is whether the pilot has the experience necessary to operate it safely.
Aircraft Value Has Become Increasingly Important
One of the biggest trends affecting Comanche owners today is rising aircraft values.
Consider the range of values currently seen within the market.
A basic Comanche may be insured for:
- $80,000
- $120,000
A highly upgraded Comanche may be insured for:
- $200,000
- $300,000
- $400,000+
The insurance company’s exposure changes dramatically as aircraft value increases.
As a result, premiums often increase even when the pilot remains exactly the same.
Modern Avionics Can Influence Underwriting
Today’s Comanches frequently include sophisticated avionics systems.
Popular upgrades include:
- Garmin GTN navigators
- Garmin G3X Touch displays
- Garmin GI 275 instruments
- Garmin autopilots
- ADS-B systems
- Engine monitoring equipment
These upgrades often improve both safety and aircraft value.
Many underwriters view modern avionics favorably because they improve situational awareness and reduce operational risk.
However, increased hull value may also increase premium.
Training Creates Confidence
Few things create underwriting confidence like training.
Insurance companies consistently reward pilots who participate in:
- Flight reviews
- Recurrent training
- FAAST programs
- Safety seminars
- Simulator training
- Transition training
Training reduces uncertainty.
And underwriters dislike uncertainty.
Pilots who actively invest in proficiency often receive stronger underwriting consideration than those who simply meet minimum FAA requirements.
Aircraft Usage Matters
Insurance companies also evaluate how the aircraft is used.
Common underwriting questions include:
- Personal use?
- Business use?
- IFR operations?
- Long cross-country travel?
- Family transportation?
- Frequent passenger operations?
Different missions create different risk profiles.
Understanding how the aircraft is operated helps underwriters evaluate exposure more accurately.
What The Best Comanche Risks Have In Common
After reviewing thousands of high-performance aircraft insurance applications, certain patterns consistently emerge.
The strongest insurance risks often have:
- Instrument ratings
- Significant Comanche experience
- Retractable gear experience
- Clean claims histories
- Annual recurrent training
- Strong recent flight activity
- Accurate logbooks
These characteristics create confidence among insurance companies.
And confidence often leads to better insurance outcomes.
Why The Piper PA-24 Remains Attractive To Insurance Companies
Insurance companies generally like experienced Comanche operators.
The aircraft offers:
- Extensive operating history
- Strong performance
- Loyal owner community
- Proven reliability
- Broad maintenance support
Combined with qualified pilots, those characteristics create attractive insurance risks.
This is one reason the Comanche remains one of the most respected high-performance piston singles ever built.
Why Thousands Of Aircraft Owners Trust BWI
BWI Aviation Insurance has helped thousands of aircraft owners secure coverage for their aircraft.
Whether you fly a PA-24-180, PA-24-250, PA-24-260, Turbo Comanche, or PA-24-400, our team understands the underwriting factors that influence pricing and carrier appetite.
We work with leading aviation insurance carriers and help aircraft owners compare options based on their specific aircraft, experience level, and mission profile.
Final Thoughts
Many Comanche owners assume insurance pricing is based primarily on the aircraft.
The reality is very different.
Underwriters spend much of their time evaluating the pilot.
Experience, training, instrument proficiency, recent flight activity, claims history, aircraft value, retractable gear experience, and operational discipline all play major roles.
The good news is that many of those factors are within your control.
Understanding how insurance companies evaluate risk can help you become a stronger insurance prospect, improve your long-term insurability, and potentially secure better coverage and pricing for years to come.
And in today’s competitive aviation insurance market, that knowledge can be extremely valuable.
bwifly.com / 800-666-4359
Continue Reading