Choosing aircraft insurance limits starts with the actual aircraft, people and operations at risk. Compare liability limits separately from hull value; no single coverage amount is sufficient for every owner or flight.
Identify the owners and other insured parties, intended passengers and use, pilot qualifications, aircraft value and written lender, airport or lease requirements. These details help frame the questions to ask about an actual offer.
An insurance policy responds within its insured interests, limits, exclusions and conditions. Carrying a policy does not guarantee that an unforeseen event will be covered or that every repair cost will be paid.
Review liability and physical damage protection separately. A premium, certificate or coverage label does not establish the amount available for a particular loss.
Aircraft Liability Coverage
Review the liability section for the actual insured parties and accepted operations, including:
- Bodily injury allegations involving passengers and applicable passenger sublimits.
- Bodily injury allegations involving other people and relevant exclusions.
- Third-party property damage, custody and contractual responsibilities.
Compare the total liability limit and any person or passenger sublimits in the actual proposal. Do not assume a particular limit is standard, sufficient or available for every single-engine aircraft.
Passenger sublimits are restrictions within the policy structure, not automatically reserved passenger funds. Do not subtract the number of passengers multiplied by a sublimit from a total limit and describe the remainder as a guaranteed amount for people or property outside the aircraft. The policy wording and actual claims control.
Physical Damage Coverage
Physical damage or hull coverage concerns the insured aircraft. Compare the stated value and valuation provisions with the aircraft’s actual configuration and condition. A loss is adjusted under the applicable terms, exclusions and deductibles; the insured value is not a promise that every occurrence produces a payment up to that amount.
Identify which operating phases the offered wording accepts:
- Not in motion: review the definition of motion and the causes of loss insured during storage.
- Not in flight: check how flight, taxiing and engine operation are defined.
- Ground and flight: review permitted activities, insured pilots and exclusions alongside the phase label.
Use your own aircraft and financial responsibilities to compare retained exposure. A historical accident rate does not determine the right hull value or liability limit for your operation.
Organize the following information when discussing the amount and scope of coverage:
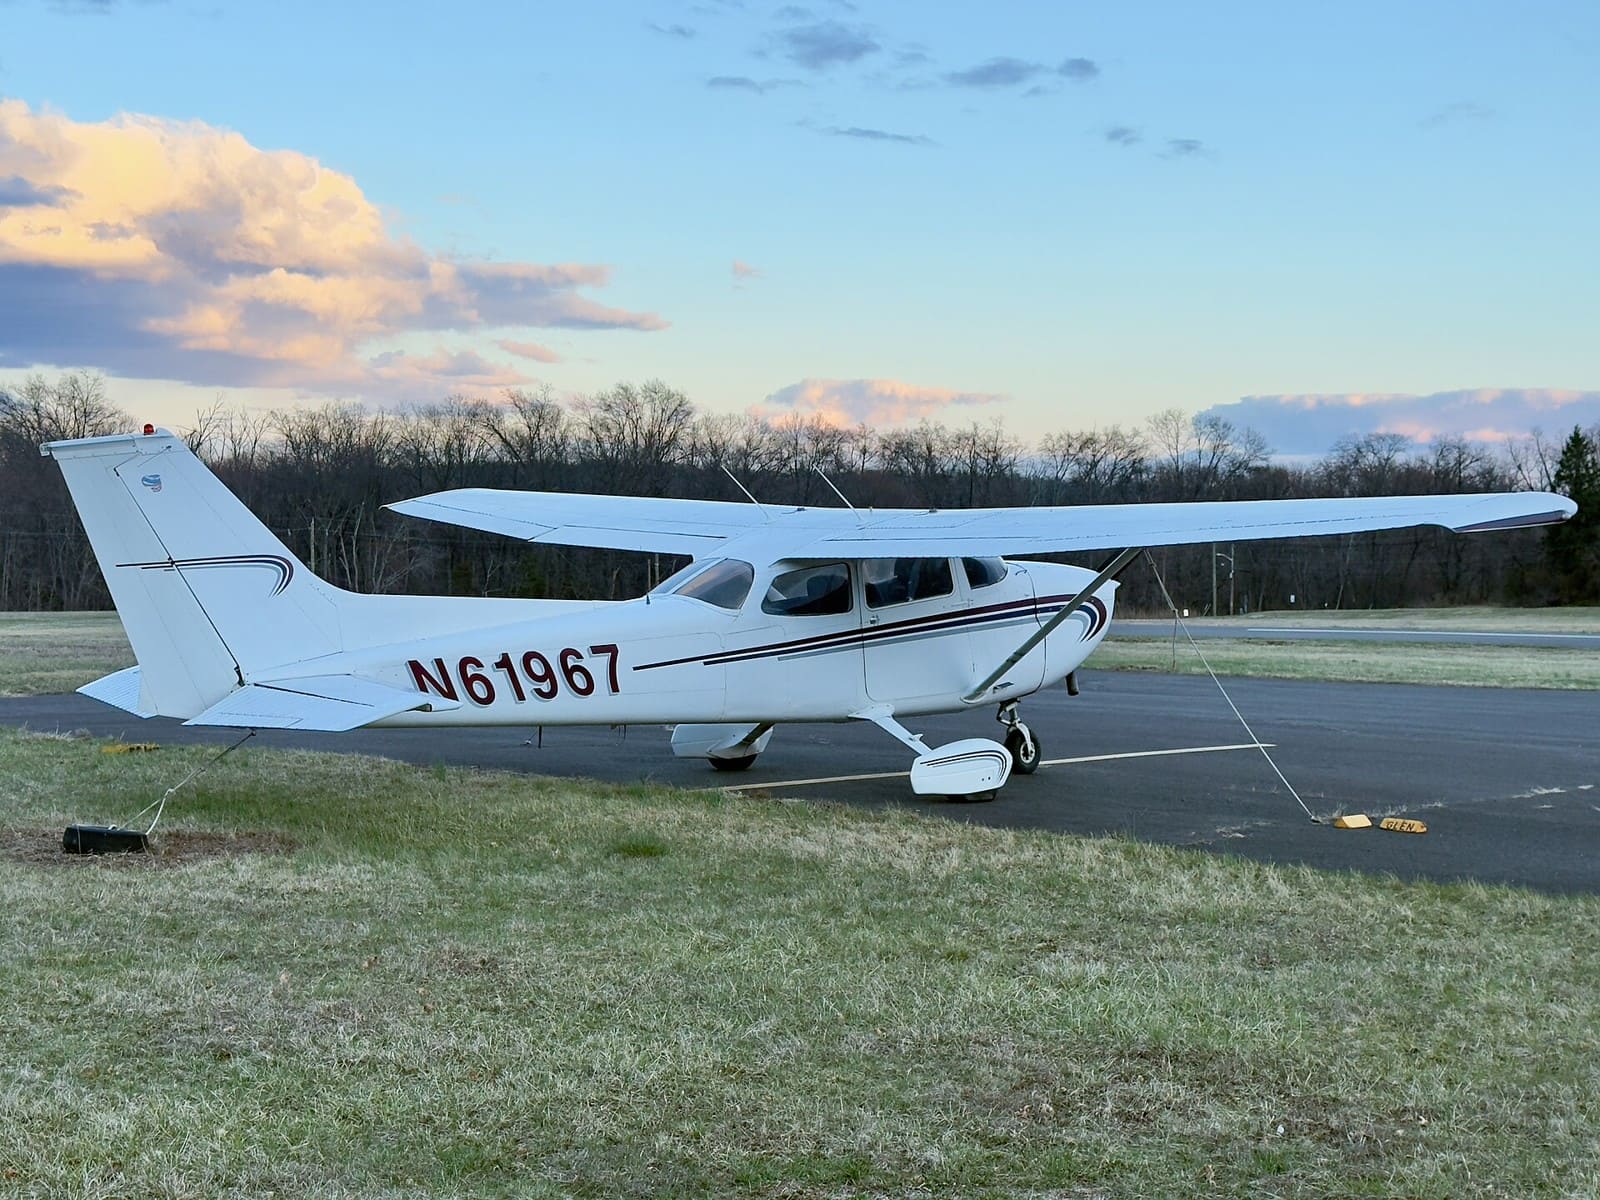
Type of Aircraft
Provide the aircraft model, serial number, configuration, equipment and requested hull value. Review valuation terms against the actual aircraft rather than assuming a model category establishes the correct value.
Repair resources, parts, modifications and intended activities are useful submission information. They do not create a universal rule that a particular aircraft needs a larger liability limit or a fixed premium.
Compare offers based on the same aircraft, value, pilots, use and policy period. Ask about any differences in limits, deductibles, exclusions and outstanding underwriting requirements.
Number of Passenger Seats and Passenger Load
Disclose seating capacity, intended passengers and use accurately. Compare how the actual proposal treats passengers and other people. Seating alone does not establish a price difference between two aircraft or a sufficient liability limit.
Review person or passenger sublimits, the total limit and defense provisions together. Typical passenger load does not establish separate reserved balances for passenger and outside-aircraft claims.
Your Flying Experience
Provide accurate total, recent and relevant aircraft experience and the qualifications of each proposed pilot. Do not treat more hours as a guarantee of acceptance, a particular price or broader protection.
Answer the application’s experience questions as requested and retain supporting records. Ask what pilot or training conditions actually apply to the offer rather than assuming a rating or flight-time category earns a credit.
When moving between aircraft models, disclose experience separately for each model and describe proposed transition training. Time in a related aircraft does not automatically satisfy the new aircraft’s policy conditions.
Why Shop for Aircraft Insurance at BWI Aviation Insurance Agency?
Bring BWI the aircraft information, proposed pilots, intended operations, requested limits and written contractual requirements. Compare the terms actually offered and identify unanswered questions before relying on coverage.
BWI is a family-owned aviation insurance agency established in 1977. Availability and price depend on the submission and underwriting; no lowest rate, turnaround or claim outcome is promised by this guide.
Call 800.666.4359 today for a free Airplane Insurance Quote or Start an aircraft insurance quote to submit a quote request online.
Read BWI’s aircraft policy reading guide and obtain written binding confirmation before treating requested protection as effective.
Continue Reading