

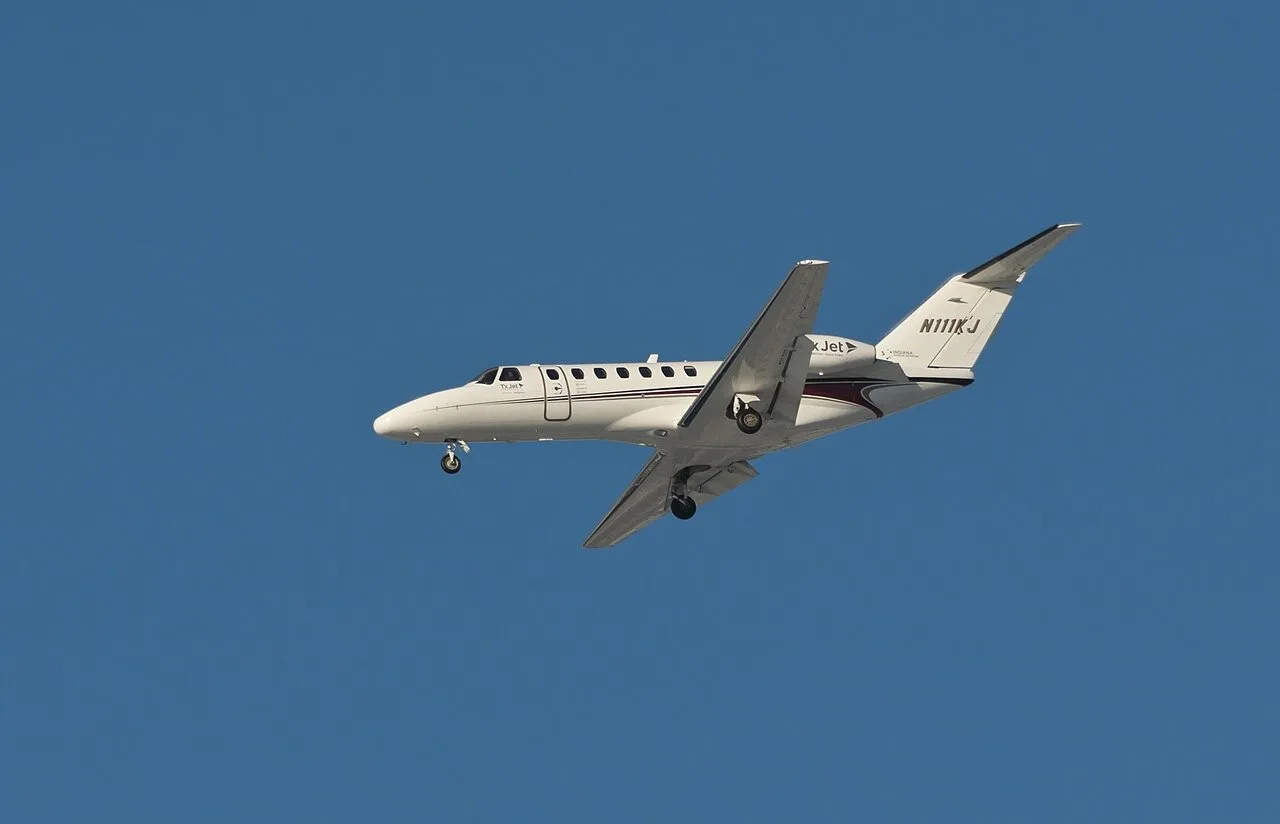
Moving from one Citation CJ model to another can feel like a familiar purchase. You know the aircraft family, may already have an established training routine, and might intend to keep the same ownership entity and airport base. The insurance review still needs to identify what is changing: the aircraft, its value, the pilot’s preparation and the dates when each airplane becomes or stops being your responsibility.
Citation CJ insurance for a model upgrade should be organized as a specific transaction. A policy for the outgoing aircraft is not a blanket approval of every later Citation you may buy. Presenting the upgrade early gives BWI time to review the pilot transition, compare available coverage and coordinate the handoff before closing.
This article supports BWI’s existing Citation jet insurance page. Its focus is the insurance change from one CJ model to another, rather than a replacement for broader Citation coverage information or technical flight training. Use it to prepare the facts and questions that distinguish your particular upgrade.
State the exact change in aircraft
Identify both the outgoing and incoming aircraft by their supported model designations, serial numbers, registrations and ownership records. Explain whether the transaction is a purchase, trade, replacement or addition. The CJ family label is useful context, but it should not conceal a change that the application and proposed policy need to describe accurately.
Include the aircraft’s actual configuration and any significant modifications. A marketing generation, avionics label or seller’s description should be reconciled with the records used by the transaction and technical advisers. If details remain uncertain during the initial search, mark them as pending and update BWI when the specific airplane is selected.
Cessna’s Citation portfolio shows a range of current models and product generations. A model appearing in a manufacturer’s portfolio does not establish its delivery status, pilot acceptance or insurance price for a particular buyer. Verify the aircraft you are acquiring and avoid treating every CJ configuration as the same underwriting submission.
Explain why the operating plan is changing
An upgrade often follows a change in travel needs. Longer trips, more business use, different passengers or a greater reliance on hired pilots can affect the information needed for the insurance review. Give BWI the proposed operation rather than describing only the old aircraft with a new registration number.
Separate aircraft capability from intended use. The fact that a jet can fly farther or carry a different load does not tell an underwriter how you plan to use it. Identify expected bases, regions, frequency of use and regular pilots. Describe any new commercial, lease or management arrangement as a proposal requiring its own review.
If the upgrade is mainly about equipment or comfort and your operation will remain similar, say so. A concise description of what stays the same is useful when it is supported by facts. It should accompany, rather than replace, a complete description of the incoming aircraft and the people who will operate it.
Keep pilot qualifications and model familiarity separate
Provide an updated summary for every proposed pilot. Show experience in the outgoing model, relevant recent activity and training completed or planned for the incoming aircraft. Do not relabel earlier-model experience as hours already flown in the new model. The underwriter can evaluate related experience more usefully when the categories remain accurate.
Have qualified training professionals confirm the applicable regulatory qualifications and limitations for the aircraft and pilot. The current 14 CFR 61.31 addresses type ratings and additional training. A pilot’s qualification for one operation should not be assumed to resolve every question about another aircraft or its configuration.
The insurance review is a separate decision. Ask which pilots are accepted under the offered terms and what model-specific training or other conditions apply. A common type-rating family, where relevant, is not a substitute for obtaining the insurer’s response to the actual submission. Keep technical certification advice and policy acceptance in their proper roles.
Submit the proposed training course before relying on it
Ask the provider to identify the course, aircraft applicability, training device and completion records. If differences training is proposed, explain the pilot’s starting qualifications and the incoming model. Send those details to BWI while the schedule can still be adjusted. General descriptions such as “CJ recurrent” may leave important questions unanswered.
Ask the insurer to evaluate the actual course and timing for each pilot. A familiar training center does not necessarily mean that every program it offers satisfies every proposed policy condition. Obtain a clear response about what is required before delivery, before independent flying and at later recurrent intervals where the terms call for them.
Keep training dates realistic. If a course will occur after closing, identify who will deliver and operate the aircraft until the condition is addressed. Do not present future completion as an existing qualification. A carefully described interim plan can be reviewed on its merits, while an inaccurate application creates avoidable confusion about what the insurer has accepted.
Determine whether another pilot is part of the offer
An owner may intend to fly alone after the upgrade but use another pilot during the transition. Identify the proposed person and role. An instructor, mentor, contract captain and second pilot are not interchangeable labels. Explain who will act as pilot in command, who will provide instruction and what each person will do during the planned flights.
Ask how any required support arrangement is documented and how it ends. The answer must come from the offered terms and insurer’s acceptance, not a general expectation that a few trips will be sufficient. Keep evidence of completed conditions and obtain confirmation of changes before moving to a different operating arrangement.
Plan for substitute pilots. If your preferred contract pilot cannot attend closing, submit the replacement person in time for review. Likewise, a management company’s ability to provide someone at short notice does not automatically establish acceptance under the owner’s policy. A practical insurance plan includes the pilots likely to be used when the original schedule changes.
Review the incoming hull value on its own facts
Give BWI the proposed purchase price, equipment details and supported valuation information for the incoming CJ. Ask how the physical damage coverage addresses the requested value under the actual wording. Do not carry forward the outgoing aircraft’s schedule simply because the policy number or ownership entity may remain the same.
Consider planned changes after delivery. Avionics work, cabin refurbishment or other modifications should be identified with their expected timing and cost where available. Ask what must be reported and when the insured value should be reviewed. A future invoice is not a substitute for describing significant planned work before the aircraft enters the shop.
Compare deductibles, settlement provisions and relevant exclusions along with the headline value. Two proposals can insure the same aircraft at the same stated amount and still differ in meaningful ways. Ask BWI to explain the structure of each offer rather than deciding that the lowest physical damage premium necessarily represents the strongest protection for the purchase.
Reconsider liability instead of copying the old limit
An aircraft upgrade is a useful time to review liability choices, even if you ultimately retain the same structure. Describe the people who will travel, the businesses involved and contractual requirements attached to the aircraft. Ask which limits and sublimits are available for the new submission and what pilot conditions accompany them.
A higher aircraft value does not, by itself, select the right liability limit. Hull and liability address different interests, and the amount of one should not be used as an automatic formula for the other. Review the owner’s circumstances with appropriate advisers and ask BWI to present the terms available for the actual account.
If a lender, hangar operator or management company requests evidence, provide its instructions early. Review named parties and requested interests under the actual policy. A certificate is evidence for a stated purpose, not an independent promise that every contractual obligation is insured. Where contract language needs legal interpretation, have the appropriate adviser review it alongside the insurance discussion.
Manage the interval when both jets are owned
Many upgrades involve a period of overlap. The outgoing CJ may remain on the market after the incoming jet closes, or the seller of the new airplane may need a revised schedule. Tell BWI whether both aircraft will be owned, stored, demonstrated or flown during that interval. Each activity belongs in the review.
Ask about the relevant policy provisions and the arrangement proposed for both aircraft. Do not assume that automatic replacement language, where present, applies without limits, notice requirements or other conditions. An additional aircraft and a replacement aircraft may also raise different questions. The issued wording must be reviewed for the actual transaction.
Keep the old aircraft’s sale team informed about the accepted pilot and use arrangements for remaining flights. A buyer’s demonstration, inspection repositioning or last business trip should not occur under an assumption that the aircraft is still insured exactly as before. Confirm the continuing arrangement until the owner’s remaining responsibilities have ended and the change is properly recorded.
Match closing custody and coverage dates
Build a simple timeline that identifies signing, funding, ownership transfer, physical acceptance, aircraft movement and the requested insurance start. Have the transaction advisers explain when responsibilities pass under the documents. Then give BWI the relevant dates, times and locations, with changes communicated before the original arrangement is relied upon.
An aircraft can change ownership while remaining at a seller’s or maintenance facility. If that is planned, identify the custodian and proposed work or movements. Ask how the buyer’s coverage will be arranged during that period. Physical delivery and financial closing may be different events, and the insurance submission should reflect the distinction.
Avoid cancelling the outgoing coverage or assuming the incoming coverage has started merely because a closing was expected. Obtain the appropriate evidence of the accepted arrangement and address remaining conditions. If closing is postponed, ask which documents need to be revised. A shared calendar is useful only when the actual insurance decisions follow the changing facts.
Compare insurance proposals using the same upgrade plan
Give each proposal the same factual baseline: aircraft value, pilot records, course, support plan, use, base and requested effective date. Record differences where an offer assumes something else. A quotation built around an experienced professional crew cannot be compared directly with one evaluating an owner’s independent operation without explaining that distinction.
Review liability structure, deductibles, pilot acceptance, training conditions and relevant territory or use limitations. Note the quotation’s validity period and outstanding information. A lower annual premium may be attractive, but it should be understood alongside the obligations and coverage it purchases. Ask BWI to resolve unclear wording before you make the selection.
Retain the proposal, acceptance correspondence and issued documents together. Check that the final aircraft identity, parties and terms reflect the arrangement requested. Raise discrepancies promptly. A verbal explanation is helpful during discussion, but the policy and accepted endorsements are the records to review when confirming the continuing insurance arrangement.
Prepare for international trips and management changes
An upgraded jet may make new destinations practical. Tell BWI where you expect to operate and ask how the proposed territory applies. Identify any requested foreign evidence and allow time for review. The aircraft’s advertised range does not establish that every destination or routing is accepted under an insurance policy.
A management arrangement can also change during an upgrade. Explain which party provides pilots, schedules flights, handles maintenance and arranges insurance. Provide relevant contract requirements for review. The management company’s policy may address its own interests without resolving every exposure of the aircraft owner or a related business.
If charter, dry leasing or other commercial use is being discussed, identify it before promising availability to customers or other parties. Insurance and regulatory acceptance are separate matters. Have the appropriate professionals review the operating structure and ask BWI to evaluate the proposed insurance requirements. A private-use quotation should not be presented as approval of a different business operation.
Build a record for the first renewal
Keep records of completed training, changes in regular pilots, equipment work and actual use of the incoming CJ. These details help explain how the transition developed. An application prepared before delivery may contain plans that have since changed. Update the submission with supported facts rather than repeating the original expectations without checking them.
Do not assume that a smooth first year creates a guaranteed reduction in premium. Ask how current experience and the requested coverage affect the renewal offers available at that time. Market conditions and underwriting decisions can change alongside the owner’s operation. Good documentation supports an informed review without predetermining the insurer’s result.
Review the outgoing aircraft’s final paperwork as well. Preserve the sale date, cancellation or schedule change evidence and records of any earlier event requiring notice. A completed upgrade should leave a clear record for both airplanes. That is particularly useful when the transactions span different dates, entities or policy periods.
Test the comparison with an upgrade scenario
Suppose an owner is replacing a CJ2 with a CJ3 and expects to keep both jets for several weeks. One proposal assumes a professional pilot will operate the incoming aircraft until the owner completes training. Another proposal is being discussed around the owner’s eventual independent operation. The premiums should not be treated as directly comparable until those different assumptions are made explicit.
Write the proposed interim operation first. Identify who will fly each jet, the expected training date, whether the outgoing aircraft will be demonstrated and where both will be based. Ask BWI to seek a response to that defined arrangement. If an offer contains a different condition, record it as a difference requiring a decision rather than overlooking it because the aircraft family is familiar.
Next, describe the later operation after the planned training. Ask what evidence and acceptance would be needed before changing the pilot arrangement. Do not count a possible later change as an existing benefit of the offer. If both aircraft will still be owned, that continuing overlap also needs to remain visible in the review.
Finally, compare the offers against the timeline you can realistically follow. A proposal can be competitively priced and still require a schedule or support arrangement the owner cannot maintain. The objective is a coverage decision that fits the accepted operation, with material differences understood. This example illustrates the comparison method; it does not predict acceptance, quote a premium or establish a standard transition requirement for CJ2 or CJ3 pilots.
Citation CJ upgrade insurance questions
Does my existing CJ policy approve a newer CJ model
Not automatically. Ask BWI to review the proposed aircraft, pilots, value and transaction under the actual policy and available terms. Related experience is useful, but it should be presented accurately. Obtain evidence of the accepted new arrangement before relying on it for delivery or continuing operation.
Is a common type rating enough for insurance acceptance
Regulatory qualifications and policy conditions are different questions. Have qualified training professionals confirm the pilot’s applicable qualifications and submit the proposed training to BWI. Ask which pilots and arrangements the insurer accepts for the incoming aircraft. Do not infer a policy decision solely from the rating shown on a certificate.
What happens if the old aircraft has not sold
Describe the overlap and intended use of both jets. Ask how the actual policy and proposed changes address each aircraft, including demonstrations or storage. Do not assume replacement provisions provide unlimited coverage for an outgoing aircraft. Confirm the arrangement before continuing flights under the changed ownership plan.
Can I use the same mentor as before
Submit that person and role for the new review. Prior involvement can be relevant but does not automatically establish acceptance for a different aircraft or transition. Ask how the support arrangement is documented and what evidence is needed before it ends. Make substitute-pilot plans visible when availability is uncertain.
Should I change the liability limit during an upgrade
Use the upgrade as a review point rather than applying an automatic formula. Describe passengers, business interests and contract requirements, then compare the limits and structures offered for the account. BWI can help explain available options. The final choice should reflect the owner’s circumstances and accepted policy terms.
Request a Citation CJ upgrade insurance review from BWI
Send BWI the details of both aircraft, the expected purchase and sale dates, pilot summaries and proposed model-transition training. Include the requested hull value, liability review, lender instructions and any period when both jets will remain in use. Make pending decisions clear so the proposal can be evaluated against a realistic upgrade plan.
Request a Citation CJ insurance review and quote from BWI. Ask for an explanation of the coverage, pilot conditions and transaction handoff before closing. A model upgrade is an opportunity to create an accurate insurance record for the aircraft you are buying and the operation you intend to maintain.
Sources
Continue Reading


