

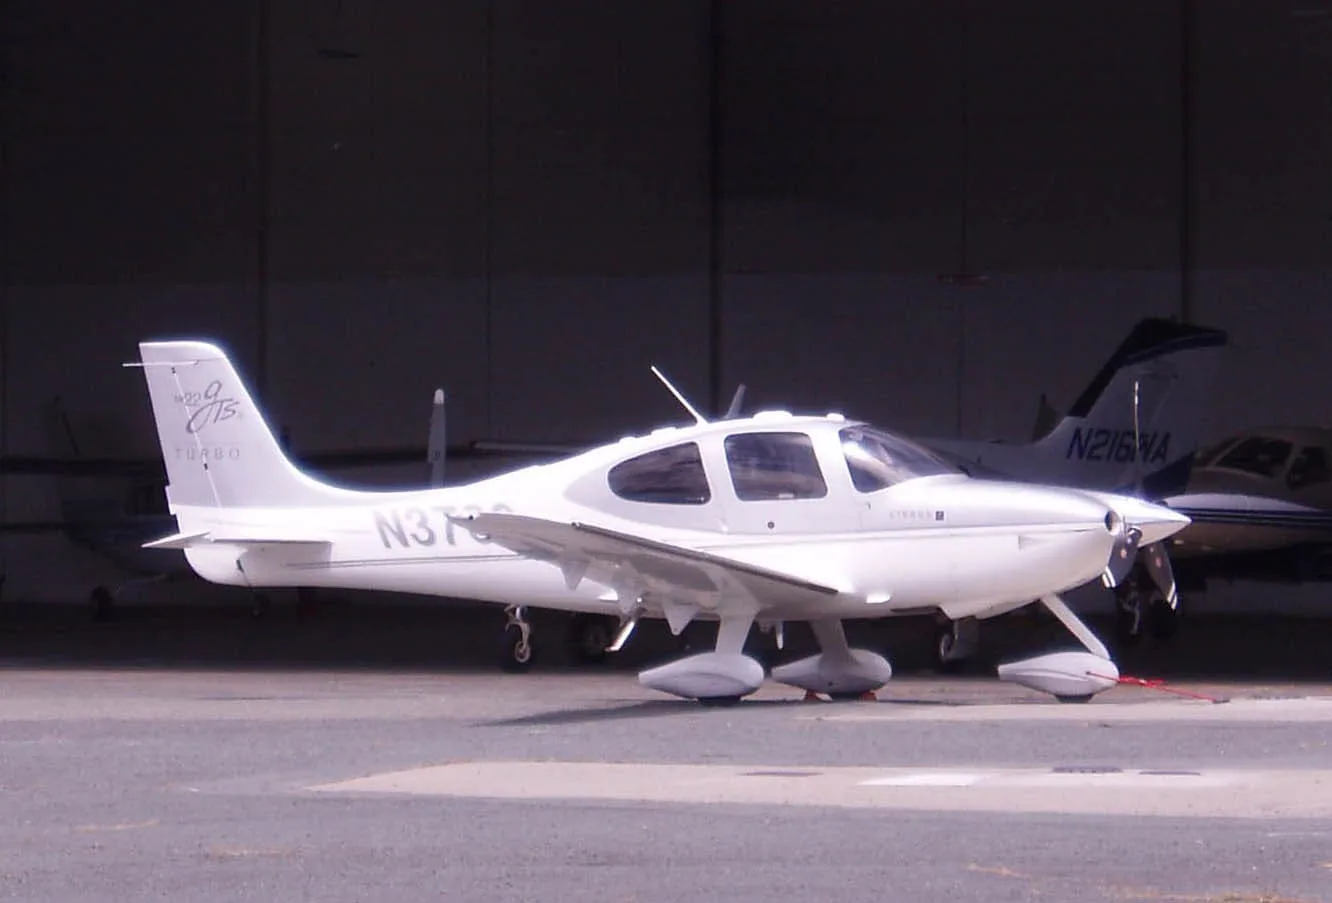
A hangar insurance application should identify who owns or occupies the space, what property is involved and what activities take place there. A building owner, tenant and aviation business can have different interests at the same address. Start with the actual arrangement rather than assuming every applicant needs the same hangar policy.
Separate the hangar structure, contents, aircraft, premises activity and any responsibility for aircraft belonging to others. These are related questions, but they should not be merged into one total value or a broad statement that everything inside the building needs coverage. The submission should make each requested protection understandable.
This guide helps prepare the information behind BWI’s hangar quote request. It supports the existing hangar insurance page and does not replace an insurer’s actual application, technical inspection or legal review of a lease. Use the current requested form and identify uncertain facts rather than inventing an answer.
Identify the Applicant and Its Interest in the Hangar
List the applicant’s legal name, any operating name and the role it holds. Explain whether it owns the building, leases space, manages property for someone else or operates an aviation business at the location. If several entities are involved, identify each separately. An individual owner and a company using the hangar should not be treated as the same insured merely because one person controls both.
BWI’s current quote page distinguishes an owner from a lessee and asks for contact and business information. Provide those facts accurately and keep the proposed effective date clear. For a purchase or new lease, identify what has been agreed and what remains pending. A transaction expected to close later should not be described as a completed ownership transfer.
Keep the actual applicant information consistent with the agreements and requested evidence. If a landlord, association or lender uses a different name for the property, explain the relationship. A quote discussion can begin before every decision is complete, but the information should distinguish the proposed arrangement from the protection actually issued for a specific entity and period.
Gather the Lease Ownership and Written Insurance Requirements
Collect the relevant lease or ownership documents and identify the sections addressing insurance responsibilities. Appropriate advisers should assess the obligations and risk allocation. The insurance contact needs the actual requested terms, including any limits, statuses or evidence requirements, rather than a summary that the airport requires a policy. A contract requirement is not itself an accepted insurance provision.
Explain who is responsible for the structure, tenant improvements, contents and premises activities. A tenant’s assumption that the landlord insures everything can differ from the agreement. An owner’s building policy should not be assumed to answer every tenant interest. The purpose of the review is to identify the actual responsibilities and then compare available protection against those facts.
If an association, manager or other party arranges insurance, identify the placement and the interest it addresses. Ask for the relevant information without treating another party’s certificate as a complete explanation of your own protection. Keep unanswered questions visible before the applicant relies on a presumed division of responsibility. A shared address does not establish identical insured interests.
Describe the Building and Location From Reliable Records
Prepare the location information requested, including the airport or property address and the particular building or unit. Identify construction, approximate size, age and relevant updates from available records. Do not guess technical details merely to complete a field. If a fact needs confirmation from the owner, manager or qualified professional, mark it as pending and obtain the appropriate information.
Describe the actual occupancy and use, including shared areas, offices, shops or other material activities. A property called a hangar can contain more than stationary aircraft storage. Explain the work occurring there and which organization performs it. An accurate description helps the reviewer identify follow-up questions without relying on the building’s name as a substitute for its use.
Provide requested photographs or records through the appropriate process and identify when they were taken. A picture of an empty unit before occupancy may not describe the current arrangement. If changes are planned, distinguish them from existing conditions. An insurance application is a factual submission, not a technical certification of the structure or a finding that it complies with every applicable requirement.
For more than one unit or building, keep a separate location record for each and explain how the applicant uses the spaces. Do not copy a single building value or occupancy description across several addresses without confirming that it applies. A clear location schedule helps distinguish shared features from facts that belong to only one part of the property.
Where the leased unit forms part of a larger building, identify which figures describe the whole structure and which describe the applicant’s space. Ask for clarification before using a landlord’s total as the tenant’s requested value. The submission should make the boundary of the requested interest visible instead of leaving the reviewer to infer it from a street address.
Separate Building Contents and Aircraft Values
Identify the property interests for which protection is being requested. The structure, tenant improvements, tools, equipment and other contents may require different information and valuation questions. Ask what basis the insurer wants used for each amount. A purchase price, tax assessment and estimated reconstruction figure are not interchangeable simply because each describes the same property in a different context.
Keep aircraft values separate from building and contents figures. The presence of an aircraft inside an insured hangar does not establish the aircraft’s own physical-damage protection. Identify the relevant aircraft policy or other arrangement for review. Likewise, an aircraft’s hull coverage should not be assumed to insure the building, every tool or another person’s property stored nearby.
Use an inventory to explain significant contents and ownership. Note items belonging to tenants, customers or other parties rather than including everything in the applicant’s total without explanation. If values remain estimates, label the basis and date. The final requested information should make clear which interest is being insured and what the offered terms actually accept.
Describe Aircraft Custody and Handling Separately
Tell BWI whether aircraft belonging to others are stored, moved, serviced or otherwise handled by the applicant. Explain the actual activities and agreements rather than assuming shared storage creates one standard arrangement. A private tenant storing its own airplane and a business handling customer aircraft present different questions, even if both use similar buildings.
BWI’s hangarkeepers liability information addresses a related liability area involving aircraft in an aviation business’s care, custody or control. Ask how the actual arrangement should be reviewed. Do not assume building insurance, premises liability and hangarkeepers protection are interchangeable labels or that one automatically includes the others.
Identify who may move aircraft, how the activity is organized and whether any operation beyond storage is contemplated. Appropriate aviation professionals should assess operational and technical requirements, while the insurance contact reviews the requested protection. A service contract or permission to use a tug does not itself amend an insurance policy. Record accepted terms and unresolved questions separately.
Explain Activities That Go Beyond Storage
Describe maintenance, repair, instruction, retail, fabrication, fueling or other business activities actually conducted at the location. Do not omit an activity because it is occasional or performed by a separate organization. Explain the relationship and the space used so the submission accurately represents the location. A noncommercial storage description should not silently stand in for an active aviation business.
For a proposed change in use, provide the expected timing and what remains subject to approval or agreement. Appropriate technical, legal and property advisers should assess the relevant requirements. The insurance review should use the actual proposal without treating an insurer’s response as permission to conduct the activity or evidence of compliance with building, airport or operational rules.
Keep the workforce and related business questions visible. A commercial occupant may need to review employee-related protection, products or service liability, vehicles and other interests separately. The goal is not to force every business exposure into a hangar application. It is to identify the wider operation and direct each question to the relevant placement and responsible adviser.
Present Protection and Security Information Accurately
Provide the information requested about access, security, fire protection and other relevant property features. State what is actually installed or in use, who maintains it and what records are available. Do not describe a planned improvement as operational or assume a protection feature guarantees a particular price. The submission should report facts, leaving underwriting to assess the offered terms.
If the applicant is a tenant, obtain the appropriate information from the owner or manager instead of guessing about shared systems. Explain any limits in the applicant’s knowledge and control. A tenant may know how it secures its own unit without being able to certify the condition or operation of every building system. Keep those distinctions clear in the response.
Do not use this application guide as a safety inspection or a set of technical instructions. Qualified professionals should assess the property and applicable requirements. If their review identifies a condition relevant to the insurance submission, communicate the accurate facts through the proper process. The insurance file should not present an unverified safety conclusion as though a technical assessment has already been completed.
Use a Document Checklist Without Treating It as a Universal Requirement
| Information group | Records to gather where relevant | Question to clarify |
|---|---|---|
| Applicant and interest | Legal names, role, ownership or lease information | Who needs protection for which interest? |
| Location and building | Address, unit identification and reliable property details | What is known and what needs confirmation? |
| Values and contents | Requested valuation information and an ownership-aware inventory | Which property is included and on what basis? |
| Aircraft and handling | Ownership, storage and custody activities | Which separate aircraft or hangarkeepers questions apply? |
| Operations and people | Activities, occupancies and business relationships | Does the description reflect the actual use? |
| Contracts and evidence | Written requirements and existing policy documents | Which requested terms are offered or unresolved? |
Prepare a compact file that explains the applicant, interest, location, property, activities and requested terms. The exact supporting documents depend on the insurer’s questions and the actual operation. Keep the current application separate from background notes so a reviewer can identify which information has been formally submitted and which items are still being gathered.
Use this checklist to organize the conversation rather than as a promise that every listed item will be required or sufficient. If a requested record is unavailable, disclose the issue and ask what alternative or clarification is appropriate. An incomplete but truthful account is more useful than an apparently finished file containing unsupported facts.
Review Existing Insurance and Relevant History
Provide current insurance information and the requested renewal details accurately. Keep the existing policy, relevant endorsements and any evidence available for comparison. Do not assume the new proposal is identical because the property address and insured name remain the same. Review the actual values, limits, deductibles and conditions in the offered arrangement.
Answer the application’s history questions using the requested period and definitions. Distinguish claim records from other events or circumstances if the questions ask about both. Ask for clarification where needed rather than interpreting an ambiguous question to produce the shortest answer. Keep supporting records and explanations consistent with the actual facts.
If new information arises during the quote process, communicate it before relying on a proposal based on an older account. A change in occupant, planned activity, ownership or property condition can matter to the submission. Keep the dated versions and final response so the applicant can identify what was disclosed and what was accepted.
A Hypothetical Tenant Adds Tools and Shared Storage
Consider a hypothetical pilot leasing a hangar for an owned aircraft and a growing collection of tools. Another owner asks to share the space, and the tenant is unsure which insurance questions that creates. This is an organizing example, not a customer case or a determination that the lease permits the arrangement.
The tenant reviews the agreement with the appropriate advisers, identifies the proposed occupants and describes the property and activities to BWI. The aircraft, tools, premises interest and any responsibility for the other aircraft are treated as separate questions. The tenant does not assume the landlord’s building policy or the existing aircraft policy resolves every interest at the shared location.
Before relying on a changed arrangement, the tenant obtains the relevant approvals and insurance responses through their separate processes. Unresolved items remain visible. The lesson is to describe the planned use accurately and connect each interest to an actual answer, rather than treating a hangar address as a complete insurance specification.
Review the Final Application and Offered Policy
Use a dated question log when the application depends on information from several people. For example, a tenant might know the value of its tools while the landlord supplies the building dimensions and roof information. Record who supplied each answer, the document or observation supporting it, and any item still awaiting confirmation. If the landlord later corrects the roof age, send the correction through the same submission channel and ask that it be incorporated into the current application. Retain the corrected version rather than leaving two conflicting copies in circulation. This suggested recordkeeping method does not replace the insurer’s questions, establish a coverage requirement or authorize anyone to sign for another party.
Have the person familiar with the records review the application before it is submitted or signed through the appropriate process. Confirm the legal name, property interest, location, values and activities. If another person completed the fields, do not assume the answers are correct without checking. Resolve contradictory figures and explanations before they become part of the final submission.
Compare the offered terms with the actual request. Identify the property and liability protection included, the relevant limits and deductibles, important conditions and any unresolved provision. A quote inquiry or preliminary indication is not an issued policy. Confirm acceptance, final documents and effective time before relying on coverage for a purchase, occupancy or changed use.
Keep the accepted submission and policy together, and revisit the account when ownership, occupants, activities or property change. At renewal, update the facts rather than copying last year’s form without review. A consistent record makes it easier to explain the actual hangar arrangement and distinguish the protection requested from the terms finally issued.
Hangar Insurance Application FAQs
Can an owner and tenant use the same information
They may share location facts but have different legal and property interests. Identify the actual applicant, agreements and requested protection rather than assuming the parties need identical arrangements.
Should aircraft be included in the hangar contents total
Identify aircraft and other property separately for review. Do not assume building or contents insurance establishes the aircraft’s physical-damage protection, or that an aircraft policy insures every item in the hangar.
What if I store someone elses aircraft
Describe the ownership, custody, agreements and actual handling. Ask about the relevant hangarkeepers and other insurance questions instead of treating shared storage as one standard arrangement.
Is this article the insurers application
No. Use the current form and questions requested for the actual placement. This guide organizes the information behind the submission and does not establish a universal required document list.
Can a quote approve a new hangar activity
Insurance acceptance, lease permission and technical or regulatory requirements are separate. Obtain the appropriate responses for each process and confirm the final insurance terms before relying on them.
Get a Hangar Insurance Quote From BWI
Bring BWI the applicant details, ownership or lease information, location, property values, activities and written insurance requirements. Explain what is confirmed, what will change and what needs further review. A clear submission helps focus the conversation on the actual hangar and interests involved.
Available terms depend on underwriting and the issued policy. A quote request does not bind protection, authorize an activity or satisfy every contract provision. Confirm the accepted arrangement and effective dates through the appropriate process before relying on it.
Continue Reading


