

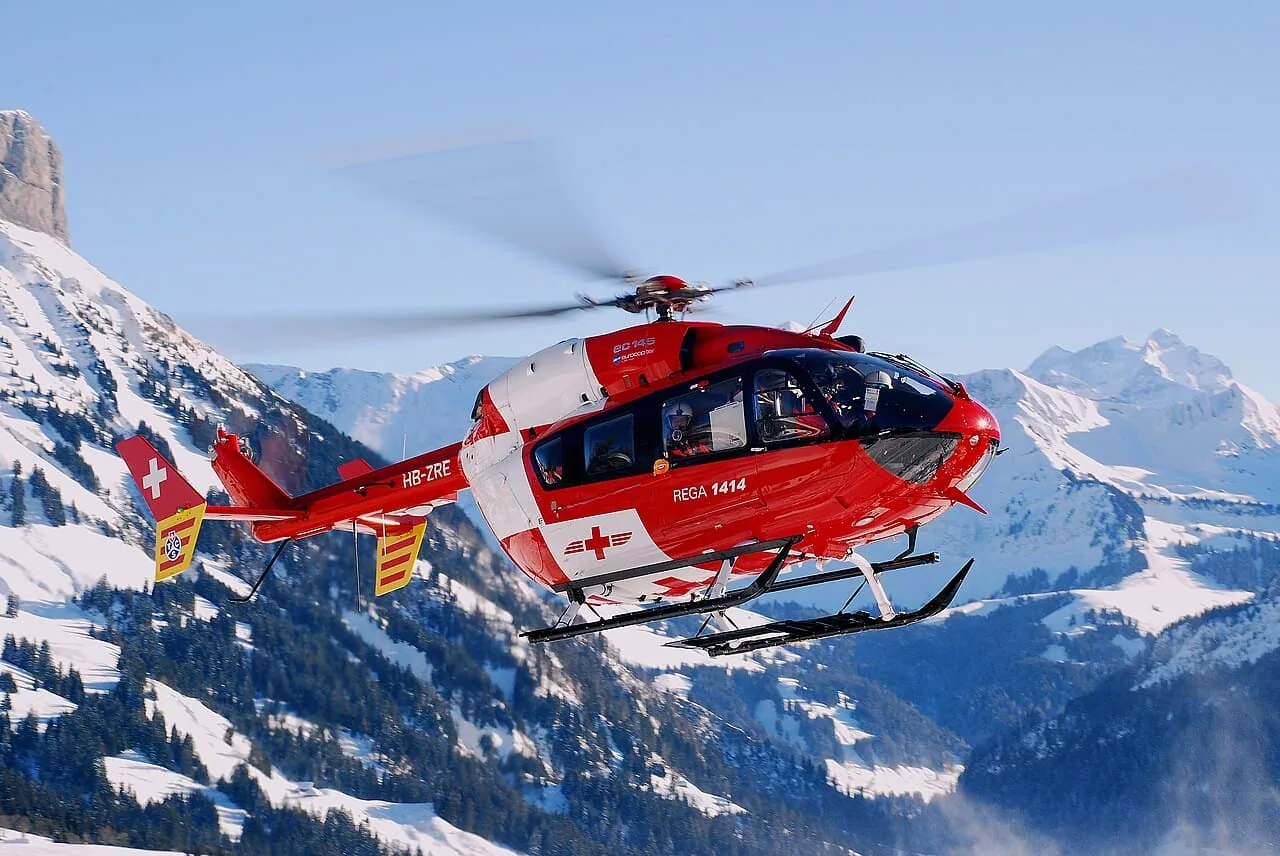
Helicopter emergency medical services insurance is an operator’s program discussion, not a patient’s health insurance question. The aircraft, flight operation, medical services, personnel and facilities can involve different organizations and different policies. A sound review identifies those parties and their responsibilities before trying to compare premiums or summarize coverage in a single sentence.
An aircraft operator may supply the helicopter and flight crew while a hospital or another organization supplies the medical team. A different arrangement may place more functions within one business. Leased aircraft, contracted maintenance and shared facilities add further relationships. The insurance submission should describe the real structure instead of assuming the words air ambulance explain it.
This guide is for organizations preparing an aviation insurance review of a helicopter medical transport operation. It provides questions and document-preparation methods, not clinical guidance, flight procedures or an approval to operate. It does not determine whether a patient’s transport bill is covered. Those patient payment and benefit questions belong with the relevant health plan, provider and appropriate advisers.
Start With an Entity and Responsibility Map
Identify the legal aircraft operator, aircraft owner, contracting customer, medical service provider and employers of each team. Explain how those parties relate through ownership, leases or service agreements. A common brand displayed on the helicopter does not establish that all organizations are the same insured or share the same policy.
Record who performs each function: flight operations, medical care, maintenance, dispatch or coordination, facilities management and equipment ownership. Describe any outsourced responsibilities and the duties retained by the applicant. A clear responsibility map helps the insurance review focus on actual exposures rather than the name used in a public announcement.
Provide the complete contracts that support the map. If an agreement is under negotiation, identify it as proposed and note the anticipated start date. The broker can then distinguish current operations from planned obligations. Where contract interpretation is needed, obtain appropriate legal advice alongside the insurance review.
Describe the Operation Without Substituting for Regulatory Review
The FAA publishes guidance on helicopter air ambulance operations for existing and prospective operators. Use the applicable current regulatory resources and qualified operational advisers for authorization and compliance questions. An insurance submission is a separate process and does not establish that an operation is authorized.
For underwriting, provide the requested operating authority information and a factual summary of services, locations and aircraft use. Identify whether the applicant is an established operator, adding a base or developing a new program. Keep effective dates and planned changes clear so a reviewer does not mistake a proposed service for an existing one.
Describe the operating environment at the level requested by the insurer. Explain the bases used, geographic scope, categories of missions and staffing arrangement. Do not omit repositioning, training or other aircraft use because it is outside a patient-carrying segment. The entire disclosed operation should be considered against the actual proposed coverage.
Build an Aircraft and Equipment Schedule
List each helicopter using the identifying information requested for the submission, its ownership or lease status, proposed insured value and use. Include relevant installed equipment in the valuation discussion. A purchase figure, lease requirement and current agreed insurance value may be different numbers, so identify the purpose and support for each.
Schedule portable medical and mission equipment separately where appropriate. Explain who owns it, where it is kept and whether it moves between aircraft, facilities or vehicles. Ask how the proposed program treats installed equipment, removable equipment and items belonging to another organization. An aircraft hull limit should not be assumed to answer every equipment question.
Describe spare components and off-aircraft property that the applicant wants considered. Record locations and transit arrangements where relevant. If an item appears under more than one proposed policy, ask how the intended arrangement works instead of assuming duplication provides a larger payment. If it appears nowhere, resolve the omission explicitly.
Separate the Major Program Questions
| Exposure or party | Submission detail | Coverage question |
|---|---|---|
| Aircraft physical damage | Aircraft schedule, values and equipment | What property and uses are included in the hull arrangement? |
| Aviation liability | Operator, aircraft use and people carried | Which liability terms, limits and definitions apply? |
| Clinical services | Medical provider and staff responsibilities | How is professional medical liability addressed separately? |
| Employees and contractors | Employer and service agreements | Which employment and occupational injury policies apply? |
| Facilities and ground activity | Bases, leases and retained duties | What premises, property or ground exposures need review? |
| Equipment belonging to others | Ownership, custody and movement | Which party insures each item and under what terms? |
| Contracting organizations | Full insurance and indemnity provisions | Which insured status and endorsements are requested? |
Review Aviation Liability and the People Carried
Provide the requested information about the people carried and their roles. Pilots, medical personnel, patients and accompanying persons should not be treated as interchangeable without reading the definitions. Ask how the proposed policy classifies relevant occupants and how those classifications interact with limits, exclusions and other coverage.
Compare the liability limit and any applicable sublimits using the actual offer. Ask how defense costs are treated and whether particular operations or occupants have distinct provisions. A large headline limit is insufficient if a material exposure is restricted elsewhere. Keep those differences visible in the written quote comparison.
The aircraft operator and medical provider should understand the boundaries of their respective programs. A claim arising around a transport can allege different kinds of conduct. Do not assume that a clinical allegation is an aviation liability claim, or that medical professional liability automatically insures the aircraft operation. Have the relevant brokers and advisers review the actual division of responsibility.
Treat Medical Professional Liability as a Separate Subject
Identify the organization responsible for patient care and the professionals providing it. Describe those relationships in the program review without including unnecessary patient information. The aviation submission should make the structure understandable while clinical scope, professional liability and applicable medical requirements are evaluated by the appropriate specialists.
Ask which entity maintains medical professional liability and how contracts allocate the responsibility to obtain it. Obtain the evidence and terms required for the review rather than relying on a general assurance that the hospital’s insurance covers everyone. Employment, contracting and insured status can differ for individual members of a transport team.
Do not use an aircraft insurance quote to answer a patient’s benefit, reimbursement or balance-billing question. Those issues involve different documents and may require specialized guidance. An operator’s program can be carefully arranged while a particular patient’s payment question remains entirely separate. Keeping the distinction clear prevents misleading communications with both staff and the public.
Explain Pilots Training and Staffing Arrangements
Prepare the pilot information requested by underwriting, including relevant experience and the training arrangements for the disclosed operation. State whether pilots are employees, supplied through another operator or engaged under a contract. Identify who has responsibility for qualification records and for communicating changes in the roster.
Review proposed pilot conditions and training requirements against the operator’s intended staffing. Ask how additions, substitutions and changes in qualification are handled. A person being operationally qualified does not, by itself, establish compliance with every insurance condition. Conversely, insurer acceptance does not replace regulatory or employer requirements.
Explain any planned expansion that changes staffing, aircraft type or operating footprint. A new base may require more than another location line if it changes personnel, contracts or aircraft use. Provide those facts in advance and request clear confirmation of what underwriting information or policy changes are needed before relying on an existing arrangement.
Review Leases Service Agreements and Insured Status
Aircraft leases, hospital service contracts, base agreements and maintenance arrangements can each create insurance obligations. Assemble the complete documents, including amendments and relevant exhibits. Record required limits, requested insured status and special wording beside the source provision so the review can be checked systematically.
Ask how each requested status is reflected in the proposed policy. An aircraft owner, lender, hospital and facilities landlord can have different interests. Being named on a certificate is not the same as obtaining every requested policy endorsement. Compare the actual wording and any limitations before representing that the contract requirement is satisfied.
Have counsel evaluate indemnification and other legal obligations, while the broker evaluates the proposed insurance response. If a requirement cannot be met as written, identify that issue early for discussion with the contracting parties. Do not allow a certificate deadline to turn an unresolved coverage question into an unsupported promise.
Include Bases Ground Property and Other Business Activities
Describe owned and leased facilities, equipment storage and ground activities performed by the applicant. Explain which party maintains common areas and which controls access or accepts property into custody. A helicopter’s aviation policy should not be assumed to provide every premises or property coverage needed for a base.
Identify vehicles, employee exposures, data systems and other business activities for separate review where relevant. Each organization should understand which policies it purchases and which contractual insurance it expects from others. A program schedule showing entities, policy periods and intended roles is useful when several brokers or departments are involved.
Keep operating changes connected to this schedule. Adding equipment, relocating a base or changing the service provider may affect multiple coverage discussions. A single notification to one policy contact may not resolve every issue. Ask who should receive updates and keep a record of the confirmations obtained.
Assemble a Submission That Can Be Compared
Provide a current organization chart, aircraft and equipment schedules, operating summary, pilot information, contracts and requested loss records. Use consistent dates and entity names. Identify any estimates and explain the basis rather than presenting projections as established operating history. New programs should describe both planned operations and the experience of the people involved.
When comparing offers, use the same disclosed operation and requested values. Record policy periods, limits, deductibles or retentions, exclusions, pilot conditions, required endorsements and outstanding binding conditions. A premium comparison is meaningful only when the material coverage differences and unresolved items remain visible.
BWI’s helicopter insurance information offers a starting point for a rotorwing coverage discussion. Present the emergency medical service structure explicitly. Do not assume that a quote for another helicopter use can be carried across unchanged to the medical transport operation.
A Hypothetical New Base Review
Imagine an established flight operator planning a new hospital service location. The operator supplies the helicopter and pilots, the hospital supplies medical staff and portable equipment, and a separate landlord leases the base facility. This example is a framework for asking questions, not a description of an insured operation or a promise of coverage.
The review file would identify the aircraft and value, the location, the staff employers, equipment ownership and each agreement. It would also explain any change in geographic scope or aircraft use. The program comparison would ask which entity and policy address each exposure, and whether the required endorsements have actually been proposed.
Before the planned start date, the parties would need to resolve operational authorization, contractual and insurance questions through their respective processes. Retaining the final documents together helps staff distinguish an approved arrangement from a draft plan. Later changes should be reviewed against those documents rather than assumed to fit because the base name stays the same.
Plan the Renewal and Change Review
Assign a responsible person to maintain the program schedule and collect changes during the year. At renewal, reconcile the aircraft list, equipment ownership, contracts and bases with the previous submission. Include acquisitions, disposals, new service relationships and activities that stopped. Removing an obsolete item can be as important as adding a new one.
Keep reporting instructions available to authorized staff. If an incident or allegation occurs, use the applicable procedures and obtain guidance on which insurance contacts need notice. Preserve relevant records appropriately, including the versions of agreements and schedules in effect. Do not delay a potential reporting obligation simply because responsibility between organizations is still being discussed.
After binding, review the issued aviation documents against the accepted offer and raise discrepancies promptly. Separate this document check from any claim-specific coverage conclusion. The objective is a coordinated program based on the actual operation, with a reliable process for updating it when the organization, aircraft or service arrangement changes.
Use an Equipment and Responsibility Handoff
For a shared service arrangement, prepare a practical handoff register for equipment and facilities. Record the item or responsibility, the party that owns it, the party that controls it during operations and the agreement that governs the relationship. Ask each organization to verify its own entry rather than having one coordinator infer everyone else’s obligations.
An installed mission system, a portable monitor and a component awaiting maintenance may each need different information. Identify whether the item remains with one aircraft or moves between locations, and whether an outside vendor takes custody. Provide values on the basis requested by underwriting, with supporting records where available. A register should make movement and ownership visible without attempting to decide coverage by itself.
Use the same method for shared facilities. Record which entity leases the space, maintains equipment, permits visitors and contracts for services. If the operator pays a bill on behalf of another organization, explain the underlying arrangement. Payment administration alone may not establish who owns property or carries the relevant contractual responsibility.
Compare the register with the policy schedules and contract requirements before the service begins. Ask about any item that appears omitted or described inconsistently. Where insurance evidence is required from another party, identify the document to collect and the person responsible for checking it. A generic statement that all partners are insured does not resolve those details.
Review the handoff when equipment is replaced, an aircraft is substituted or a service contract changes. Keep dated versions so staff can reconstruct the arrangement that existed at a particular time. This administrative record supports a focused insurance discussion while operational, clinical and regulatory decisions remain with the people authorized to make them.
For example, a substitute helicopter might arrive without the same installed mission equipment as the aircraft it replaces, while portable items remain owned by the medical provider. Record the actual replacement aircraft, the equipment that moved and the date of the change. Give the relevant insurance contacts the requested facts and ask which schedules or confirmations need revision. Do not infer acceptance from a previous aircraft entry or from the fact that the same personnel remain on duty. Keep the response with the updated equipment register. This example concerns administrative coordination only; technical suitability, clinical readiness and authority to conduct a flight require their own qualified review before anyone relies on the substitution.
Frequently Asked Questions
Is this insurance the same as coverage for an air ambulance bill
No. This guide concerns the operator’s aviation and business program. A patient’s health benefits, provider charges and payment obligations require a separate review with the appropriate organizations and advisers.
Does aircraft liability automatically include medical malpractice
Do not assume so. Aviation operation and clinical services involve different exposures and potentially different insured entities. Review the actual aviation and medical professional liability arrangements separately.
Is portable medical equipment part of the aircraft hull value
Its treatment depends on ownership, scheduling and policy wording. Identify installed and removable items and ask which policy is intended to insure them, at which locations and during what movements.
Does an operating approval establish insurance coverage
No. Regulatory authorization and insurance are separate. Provide the requested authority information to underwriting, and confirm insurance through the actual accepted and issued documents.
What should be reviewed when adding a base
Review the location, aircraft, staff, services, equipment, contracts and any change in operating scope. Ask what underwriting acceptance and policy changes are required rather than treating it only as an address update.
Talk With BWI About Your Business
Bring BWI a current description of the helicopter operation, aircraft and equipment schedules, entity responsibilities, relevant agreements and the information requested for underwriting. Identify the medical provider and any planned program changes.
Discuss helicopter insurance with BWI and request a review tied to the disclosed medical transport operation. Coverage and availability depend on underwriting acceptance and the actual issued terms.
Continue Reading


