

An independent aircraft prebuy inspection business needs its insurance reviewed for both the work it performs and the conclusions it sells. Accidentally damaging a seller's airplane during an inspection is one concern. A buyer alleging that an incomplete condition report led to an expensive purchase is another, even when no accident or new physical damage has occurred.
Begin with your actual inspection agreement, a representative report and a description of everything your business does around the aircraft. Ask the insurance reviewer to address inspection advice and alleged financial loss separately from maintenance, aircraft custody and flying. A mechanic certificate, the seller's hull policy and a general liability certificate do not establish the same protection.
This guide is for the inspection provider rather than the prospective aircraft owner. It explains how to prepare a focused insurance submission, compare proposals and keep a growing inspection business within the operation actually disclosed. BWI's aviation professional liability information provides a starting point for that discussion. Availability and eligibility require review of the particular business.
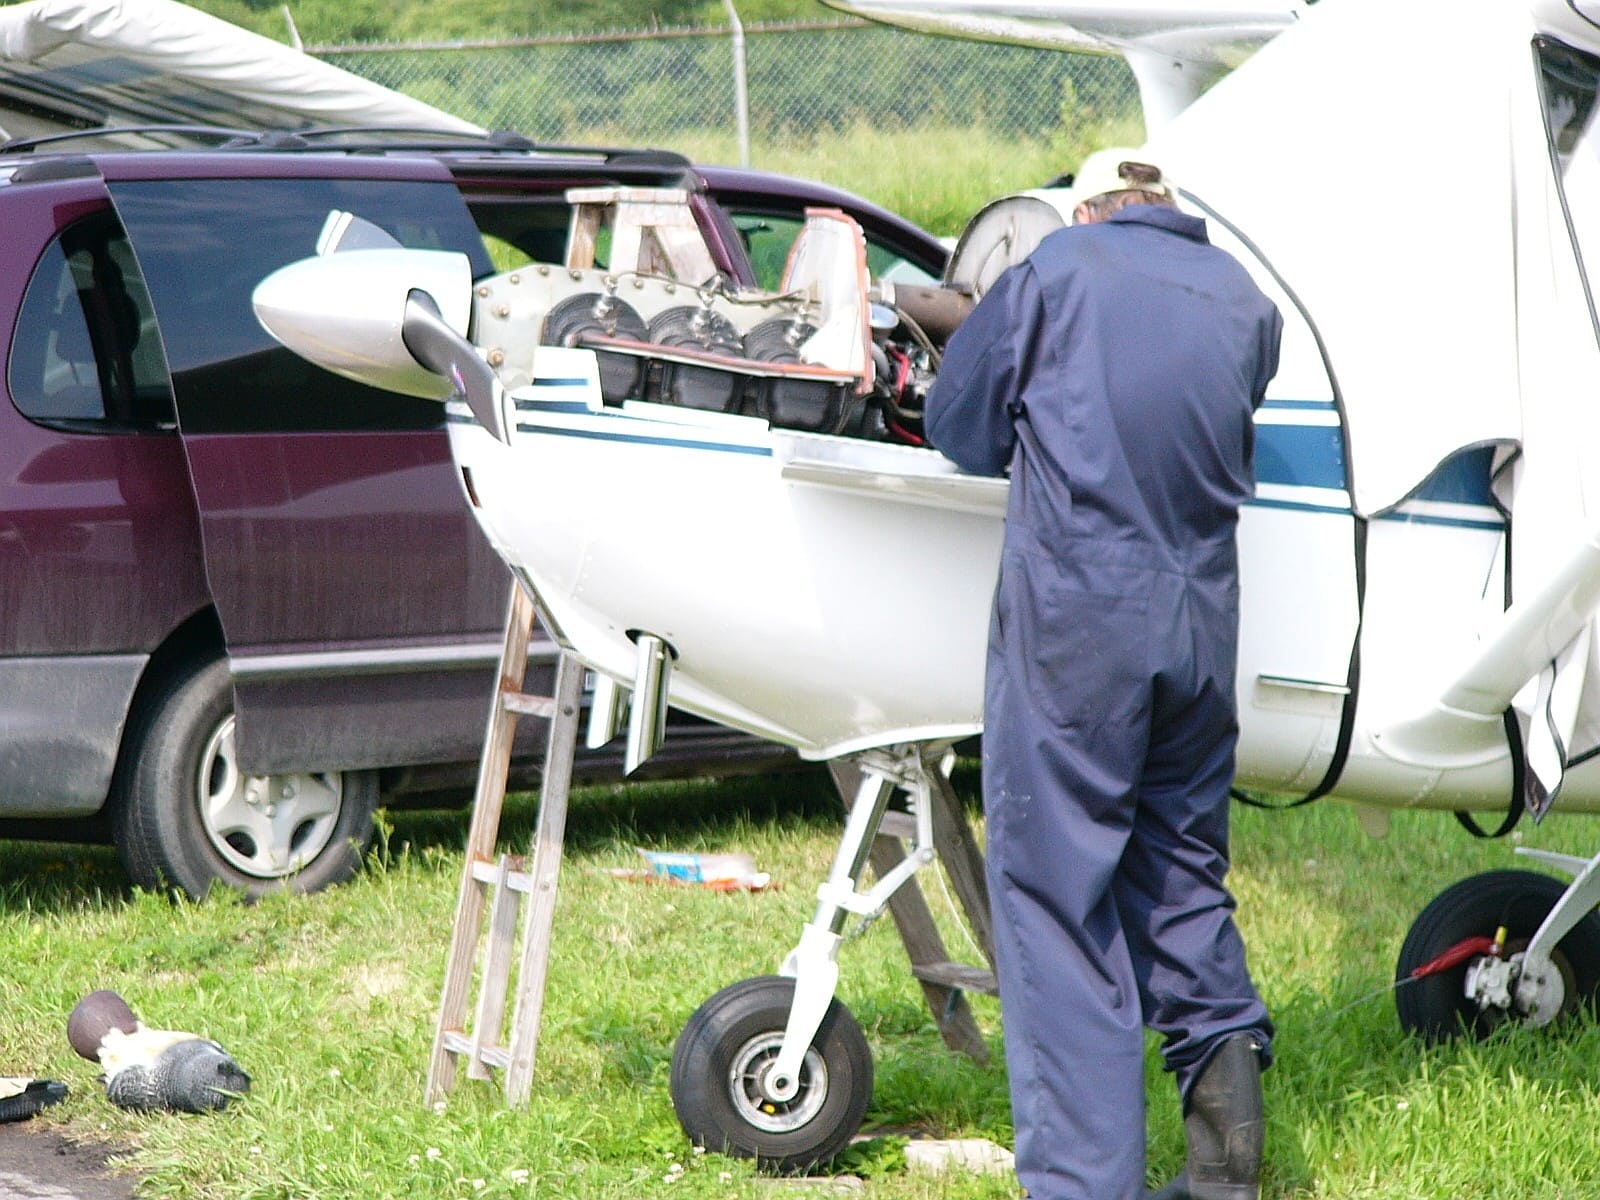
Define the Service the Buyer Is Purchasing
A prebuy engagement can mean a remote review of scanned records, an on-site condition assessment, a detailed physical inspection or an inspection combined with corrective maintenance. Those descriptions should not be used interchangeably in an application. Identify the deliverable the customer receives and the activities your people undertake to produce it.
Describe the aircraft categories and the depth of the engagement. Reviewing a familiar piston single at a local hangar differs from coordinating several specialists for a business jet transaction. Explain which systems your business evaluates itself, which findings depend on another specialist and what the customer has deliberately excluded from the assignment.
Supply the actual written scope used with customers. If your quotation promises a comprehensive inspection but your agreement describes limited observations, resolve that mismatch with appropriate counsel. The insurer should see the service you are selling, including statements on your website and sample reports, rather than a narrower description selected only for the application.
Identify any additional role in the transaction. Finding aircraft for a buyer, negotiating a price, receiving a referral payment, valuing the airplane or managing delivery can introduce questions beyond inspection work. Disclose those services and financial relationships. A single invoice for a package of services does not make all of them the same insured professional activity.
Review Financial Loss Without an Accident
A buyer might allege that a missed discrepancy caused it to overpay, accept an aircraft it would otherwise have rejected or incur avoidable evaluation expenses. Those allegations can concern the inspection service even if the aircraft never has an accident. Start the coverage discussion with the alleged loss rather than assuming every aircraft-related complaint belongs under bodily injury or property damage liability.
Global Aerospace's current aviation professional services overview specifically uses an inadequate pre-purchase inspection to illustrate why financial-loss liability deserves separate consideration. That is a primary insurer's explanation of a coverage category, not confirmation that a particular inspection business or allegation is accepted under a BWI placement.
Ask the proposed insurer which professional services are described, how a wrongful act and damages are defined, and what exclusions affect the assignment. Review whether the offered wording addresses the kinds of reports and advice your business actually provides. Do not substitute a policy title for that comparison or assume every cost claimed by a dissatisfied buyer is an insured amount.
Keep a refund request, the cost of repeating your work and an allegation of consequential financial loss distinct. Ask about each under the actual terms. The engagement fee is also different from the aircraft purchase price and the amount a customer might demand. Those figures help explain the transaction, but none establishes the available policy limit or a future settlement.
Separate the Inspection Report From Maintenance Authority
A commercial condition report and a required maintenance record serve different purposes. If the engagement includes maintenance or a required inspection, qualified personnel must determine the applicable authority, procedures and entries. Calling the assignment a prebuy does not remove those obligations, and buying professional liability insurance does not authorize technical work.
The FAA's owner and mechanic responsibilities guidance explains the importance of defined roles and maintenance communication. Keep the responsibilities of the owner, mechanic and inspection customer visible in your work arrangements. Do not imply that an advisory report transfers all airworthiness responsibility to the inspection business or replaces the records required for work actually performed.
Give the insurance reviewer examples of the documents you issue. Distinguish a condition summary, a maintenance entry, a discrepancy list, a repair recommendation and an appraisal. Explain who signs each and in what capacity. A technician may perform more than one role, but the submission should identify those roles rather than leaving them hidden behind the same signature.
If a customer asks you to convert the assignment into an annual inspection or perform repairs, document the revised scope and obtain the required operational and insurance review. A quote based on records analysis alone should not silently become the insurance description for hands-on maintenance and release activity.
Identify the Client and Everyone Who May Rely on the Report
Write down which legal entity engages your business and who may receive or use the report. The individual coordinating the inspection may represent an acquisition company, a prospective owner, a lender or another adviser. Identify the actual customer instead of assuming the email sender and contracting entity are identical.
Have counsel review permitted reliance and distribution provisions. A report prepared for one buyer may later circulate to another bidder, a financing contact or a resale prospect. That can raise different allegations and contract questions. Do not assume an email disclaimer resolves every duty, or that adding recipients after delivery is a purely administrative change.
Explain those arrangements to the insurer, including reports marketed for repeated use or sold to more than one party. If your ordinary service permits only a named client to rely on the findings, describe how requests from other users are handled. The policy review needs the real practice, including exceptions regularly approved by sales staff.
Identify relationships with the seller, aircraft broker and maintenance facility. A prior service history or referral relationship need not be concealed to make the engagement look independent. Disclose the facts accurately and let appropriate advisers assess conflicts, customer expectations and insurance implications. Do not promise that a label such as independent eliminates the possibility of a claim.
Make Inspection Limitations Specific and Traceable
Access restrictions matter to both the report and the insurance submission. The seller may decline a particular test, records may be missing or a component may be inaccessible within the agreed scope. Record what was not evaluated and why. Do not present an unavailable source or unperformed task as a satisfactory result.
Use a clear process for communicating important limitations before a customer makes a transaction decision. A limitation buried in an appendix can be difficult to reconcile with a broad assurance in the opening summary. The report should distinguish an observation, an inference, an unresolved question and a task referred to another specialist.
Retain the customer's written instruction when it chooses a narrower scope, but avoid treating that instruction as a universal release of liability. Counsel should review the contract's effect, and the insurer should review the actual service and relevant exclusions. Good documentation explains the assignment; it does not manufacture coverage or decide a future dispute.
When additional records arrive after the report, decide who reviews them and how a correction or supplement reaches the appropriate recipients. Preserve the original and the dated revision. An informal replacement file with no explanation can make it harder to establish which information the buyer possessed when it made its decision.
Aircraft Custody and Physical Work Need Separate Protection
A provider that opens panels, removes components, moves the airplane or arranges ground activity has exposure beyond the content of its report. Explain who owns the aircraft, who authorizes access and who controls it while the work occurs. The buyer commissioning an inspection may not yet have authority to approve every action involving the seller's property.
Ask how customer aircraft damage is addressed under the proposed program, including relevant care, custody or control provisions. Review the services and locations covered, applicable limits and deductibles, and any restrictions on movement or ground operations. A financial-loss professional liability proposal should not be assumed to insure accidental damage during physical inspection.
If your business performs corrective work, review products and completed operations separately. Distinguish an allegation that the report omitted a defect from an allegation that a repair caused later damage. The two may involve different facts, coverage sections and reporting requirements even when they arose during the same visit.
BWI's hangarkeepers liability information provides context for customer aircraft custody. Your inspection operation still requires its own review. A borrowed workspace, a seller's hangar or an off-site subcontractor can change the description; owning no hangar does not make the custody question disappear.
Disclose Specialists and Any Flying Arrangements
List independent specialists used for engines, avionics, structures or records analysis. Explain whether the customer hires them directly or your business contracts for their work and incorporates their findings into its own report. A subcontractor's insurance certificate does not by itself establish your protection for a complaint about the combined service.
Provide the relevant agreements and describe who selects, instructs and pays each specialist. Ask how the proposed policy treats subcontracted professional work and allegations against your own business. Also identify any technical tasks outside your competence that you decline rather than describing every requested capability as available.
If an inspection includes a flight, disclose your business's precise involvement. Acting as pilot, supplying a pilot, arranging a flight and observing as a passenger are different roles. Identify the aircraft, actual operator, pilot, purpose and occupants for the appropriate review. An owner's permission and an insurer's acceptance are different questions.
Do not infer flying protection from professional liability or a ground-services description. Resolve applicable aircraft, nonowned, pilot and business liability questions with the relevant parties before relying on the arrangement. The insurance review does not establish airworthiness or operating authority, and this guide does not prescribe technical inspection or flight procedures.
Compare Dates Defense Costs and Retained Amounts
Professional liability proposals may use claims-made wording and specific reporting conditions. Ask the insurance contact to explain the actual trigger, retroactive date, treatment of prior services and notice requirements in the offered form. Do not assume that the date of the inspection alone determines which policy must respond.
Review continuity before changing insurers, reorganizing the business or ending inspection work. A report can become the subject of an allegation after the engagement ends. Ask about any available extended reporting provisions and their limitations, without assuming they create protection for new work or cure a known problem disclosed too late.
Compare defense-cost treatment, limits, aggregates and deductibles or retentions. Determine whether expenses reduce the amount available for damages and how related allegations are treated under the actual wording. A proposal with the same headline limit can allocate costs differently from another offer. Do not add unrelated aircraft and professional liability limits together as though they form a single fund.
Read contractual liability, warranty and performance provisions carefully. A customer may request a guarantee of condition or reimbursement far beyond the professional service you intended to sell. Have counsel assess that commitment and ask the broker what the policy actually supports before signing. Insurance is not a guarantee that the purchase will meet the customer's expectations.
Test the Submission Against a Changed Assignment
Consider a fictional inspection company hired to examine a prospective buyer's airplane candidate at the seller's hangar. The initial engagement includes records review and a limited physical assessment. The buyer then asks the company to negotiate a price reduction, while the seller requests a repair and a flight before releasing the aircraft.
The company now has several additional roles to consider. Negotiation may be a separate advisory service, repair adds maintenance exposure, and flight introduces aircraft and pilot questions. The original inspection description does not explain all three. The practical response is to define the proposed additions and obtain the necessary reviews before accepting them.
Suppose the sale proceeds and the buyer later alleges that an excluded system should have been evaluated. The useful file would preserve the agreed scope, access limitations, report versions, communications and the timing of the buyer's decision. Those records assist factual review; they do not prove that the company is free of liability or that any insurer must pay.
This example is not a reported BWI customer event. Use it to identify gaps in your own submission: who the client is, what was sold, which work was performed, who handled the aircraft and what changed. Keep the professional service and physical operation visible throughout the engagement.
Keep the Complaint File Separate From Sales Follow Up
If a buyer challenges your findings, preserve the original complaint and supporting report before revising or withdrawing anything. Follow applicable policy notice instructions and identify who will coordinate with the insurer and counsel. A salesperson offering a quick fee refund should not inadvertently make an unsupported admission or settlement commitment.
Keep factual corrections distinct from conclusions about fault. Record what was known at inspection, what arrived later and which recipients received each version. Use the established service and claim contacts for an existing allegation; a fresh quote application is not a substitute for notifying the relevant policy.
Prepare a Focused Quote and Renewal File
Send the legal business name, ownership structure, personnel qualifications, years of relevant experience, services and aircraft categories. Include revenue information in the format requested by the application, along with representative engagement agreements and reports. Identify separate appraisal, brokerage, maintenance or flight activity rather than folding it into inspection revenue without explanation.
Add subcontractor arrangements, work locations, customer aircraft values where relevant, current policies and available loss or complaint information. Describe unresolved allegations accurately. Ask how the application wants a complaint, circumstance or claim reported; do not select a favorable label merely because no lawsuit has been filed.
At renewal, compare the current service with the prior submission. Note larger aircraft, additional personnel, overseas customers, new report users or expanded transaction assistance. Explain changes in contract language and limitations. A business can materially change its professional exposure without buying a hangar or increasing the number of aircraft inspected.
Request a comparison that identifies the accepted professional services, relevant dates, limits, retained amounts, defense provisions and important exclusions. Keep aircraft custody and maintenance answers alongside that comparison, clearly labeled. Before relying on a placement, confirm the issued terms, effective date and outstanding conditions with the insurance contact.
Discuss the Inspection Business With BWI
Bring BWI a representative engagement from first instruction through final report. Show which entity contracts with the buyer, who works on the aircraft, which specialists contribute and what the customer is entitled to rely on. That makes the insurance discussion more precise than requesting a generic mechanic policy for an operation that also sells inspection conclusions.
Start a commercial aviation insurance quote review or call 866 788 6291. Ask specifically about professional service allegations involving financial loss, together with any customer aircraft custody, maintenance and flying your business undertakes. BWI and the relevant underwriter must confirm available terms for the actual operation; an inquiry or submitted application does not bind coverage.
Sources and further reading
Continue Reading


