

An aircraft maintenance training provider needs insurance reviewed for the education it sells and the practical work students undertake. A classroom presentation, a demonstration on a training aid and a task involving a customer's aircraft can create different responsibilities. The submission should explain those differences rather than describing the business simply as an aviation school.
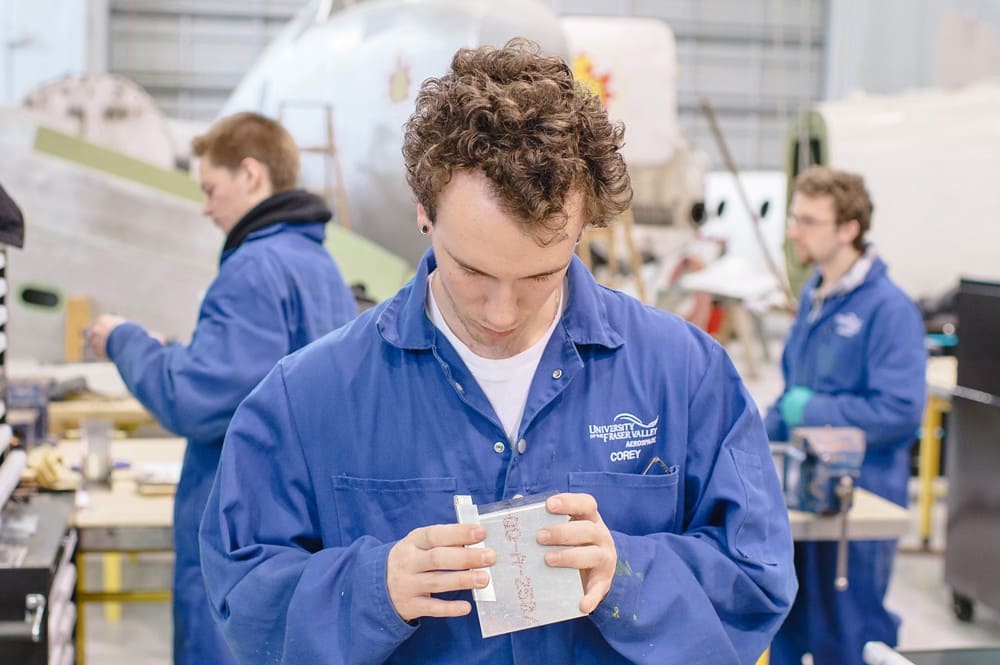
Begin with the course model, students, instructors, premises and equipment. Identify who owns the aircraft or components used, whether they are training property or operational customer assets, and what the provider promises about the course outcome. Then ask which proposed protection addresses instructional allegations, injury, property damage, customer custody and the school's own equipment. Neither a training approval nor a general business certificate settles every insurance interest.
This guide helps commercial maintenance training providers prepare that inquiry. It does not design a curriculum, establish a student's maintenance privileges or provide workshop procedures. Qualified education, technical and legal personnel must address those matters. BWI's commercial aviation insurance information introduces the broader discussion; specialist eligibility and terms require confirmation for the actual provider.
Explain Whether the Business Is a School or a Specialist Course Provider
Describe the training sold in plain language. A school preparing people for maintenance careers, a company teaching an existing workforce a specialist topic and a vendor demonstrating equipment can have different agreements and responsibilities. Identify the actual customers and deliverables rather than assuming every maintenance course belongs to the same insurance category.
Give the legal entity that contracts with students or employer customers. If a related maintenance shop supplies instructors or aircraft, explain the relationship. A common logo or ownership group does not automatically make every organization an insured under the same policy. The reviewer needs the parties behind the enrollment, premises and equipment agreements.
Separate established courses from plans. A provider considering practical training next year should not describe that capability as currently operating, while an existing occasional workshop should not be omitted because classroom work supplies most revenue. Present supported activity information or clearly identified projections in the periods requested by the application.
Explain whether the company performs paid maintenance, repair or consulting as well as education. The distinction matters when an instructor shifts from demonstrating a concept to accepting responsibility for a customer's operational equipment. List the actual services and contractual roles instead of expecting an educational description to encompass them all.
Describe Regulatory Status Without Promising a Credential
The FAA aircraft maintenance technician school information describes an AMTS certificated under Part 147. It distinguishes the school's status and ratings from the other eligibility requirements a mechanic applicant must meet. State the status your institution can document; do not present every specialist course as an FAA-certificated maintenance school.
Explain precisely what completion documentation your provider issues and what it represents. A course attendance record, a provider's assessment and a document associated with an authorized curriculum have different purposes. Have qualified education personnel verify the descriptions used in marketing, enrollment agreements and the insurance application.
Regulatory acceptance and insurance acceptance remain separate. A school certificate does not schedule every piece of equipment as insured property or determine how an instructional allegation is treated. An insurance quotation does not authorize a curriculum or grant students maintenance privileges. Keep the evidence supporting each subject clearly identified.
If the provider operates under another institution's arrangement, describe who holds the relevant status and who actually delivers the course. Supply the agreement rather than referring loosely to an approved program. The insurer should be evaluating your organization's disclosed role, not inferring it from another institution's name.
Make Practical Exercises Specific Enough for Underwriting
Identify the settings where instruction takes place, including classrooms, workshops, customer facilities and remote sessions. Explain what students physically do at each one. Observing an instructor, using a bench training aid and handling an aircraft component are different facts, even when they appear in the same course catalog.
Describe the actual equipment and materials involved without turning the insurance submission into a technical manual. Identify whether training aircraft are static aids, potentially airworthy assets or customer aircraft. Tell the reviewer who controls them and what work is undertaken. Do not assume an aircraft commonly used for teaching has no value or operational significance.
List any ground movements, engine activity, flight demonstrations or other operations associated with a course. Qualified professionals must establish the applicable procedures and authority. For insurance, the important point is that these activities reach the underwriter rather than disappearing within a broad description of hands-on learning.
If learners perform work that may enter an operational maintenance record, disclose that arrangement explicitly. Explain who supervises, evaluates and holds the relevant responsibility. This guide cannot decide a student's authority or return-to-service status, but the insurance description should not obscure the fact that operational customer equipment is involved.
Separate Training Property From Customer Aircraft and Components
Prepare separate schedules for assets owned by the provider and equipment entrusted by others. A donated training airframe, leased engine, instructor-owned tool and customer's serviceable component can each have a different financial interest. Ownership should be supported by the actual donation, lease or service agreement rather than inferred from where an item sits.
For owned or leased training equipment, discuss valuation with the insurer using supported records. The nominal purchase price of a donated or retired asset may not represent the cost of replacing a usable training setup. Conversely, an operational aircraft value should not be copied onto a static aid without explaining the condition and basis.
For customer property, identify the maximum concentration, location and custody period. Ask which proposed section addresses your business's responsibility, relevant exclusions and the limits and deductibles offered. A provider's premises liability should not be assumed to protect every aircraft or component used in a class.
If an outside maintenance organization supplies equipment, obtain the agreement and insurance evidence required for the relationship. Its own policy does not automatically make your organization an insured or remove your contractual obligations. Keep the property interest separate from possible liability involving instruction or practical work.
Review Student Injury Questions Separately From Course Quality
Describe who attends courses and the relationship to the provider. Students enrolled independently, employees of a customer company and the provider's own trainees can have different arrangements. Do not use a single label to decide employment status, benefit eligibility or which policy should address an alleged injury.
Ask the appropriate insurance and legal advisers how premises liability, participant-related protection, workers compensation or other arrangements apply to the disclosed facts. An educational liability title should not be treated as a universal personal accident benefit for learners. Likewise, a student's health insurance does not establish the provider's own protection.
Provide the complete agreements governing visits to customer workshops or hosted classes. Identify who controls the room, tools and teaching activity. The host's invitation and certificate may be relevant documents, but they do not independently resolve every responsibility of your instructors or business.
Practical safety decisions belong with qualified personnel responsible for the environment and equipment. Insurance review should use the resulting accurate facts rather than being presented as approval of a workshop layout or exercise. A favorable quotation cannot replace the operational review necessary for the course being delivered.
Ask About Allegations Concerning Instruction and Assessment
A customer may allege that course material was incorrect, an assessment was recorded improperly or a promised instructional service was not delivered. Explain the actual service and commitment to the insurance reviewer. A physical property policy is not a complete answer to an allegation about the information or evaluation the provider supplied.
Ask what professional or educational liability wording, if any, can be considered for the disclosed activities. Examine the defined services, damages, exclusions, defense provisions and reporting conditions. Do not infer that a general professional policy accepts aviation maintenance instruction or every form of educational dispute without review.
Separate a refund obligation, re-teaching expense and alleged consequential loss. An insurance proposal should not be described as a guarantee that tuition or every employer complaint will be reimbursed. The legal obligation and policy response need their own assessment based on the actual enrollment or course contract.
Provide examples of materials and completion records when requested. Explain who reviews content and controls revisions as an established practice. A polished syllabus should not make unsupported promises about licensing, job placement, insurer acceptance or a student's authority to carry out maintenance after the course ends.
Identify Instructors and Outside Content Providers
Describe instructor duties and the factual employment or contracting relationships. A teacher can also be a technical adviser, examiner, demonstrator or maintenance provider. Identify those roles rather than assuming an instructor label adequately explains every task sold through the business.
If independent specialists deliver modules, provide the agreements and describe whose name appears on the course documentation. Explain who contracts with the learner and handles a complaint. The specialist's insurance and your organization's potential responsibility are separate subjects; neither should be assumed to eliminate the other.
Identify curriculum, photographs, software and technical resources licensed from other organizations. Qualified personnel should establish the rights to use and distribute them. A professional liability policy does not itself grant a content license, and a supplier relationship does not automatically transfer every responsibility for the finished course.
For remote instruction, explain the platform, recordings, assessment service and customer data your organization manages. Ask how instructional, technology and cyber-related questions fit together. An error in teaching, loss of a learner record and unauthorized system access should not be treated as one identical event because all involve a computer.
Follow Demonstration Equipment Through Travel and Installation
A provider delivering courses at customer sites may transport tools, models, components or portable equipment. Identify who owns each item, who carries it and where it is stored. Ask about property away from the main premises, transit, loading and temporary custody rather than assuming a scheduled workshop address follows the instructor everywhere.
If an outside company installs or removes a training aid, provide the relevant agreement. Describe whether it accepts responsibility for the property or supplies labor under your direction. A paid installation invoice does not determine which party's insurance protects the equipment during that stage.
Review leased or borrowed demonstration equipment using the actual contract and supported values. Identify return obligations, damage responsibilities and any lender or lessor evidence requests. A rental charge or damage waiver should not be treated as equivalent to an accepted property policy without reading what it provides.
When a course changes location, update the relevant submission. A hotel classroom, college workshop and operational hangar can create different premises and customer property questions. The same instructor and lesson title do not make the new setting identical to the location previously described to the insurer.
Read Customer Agreements Before Guaranteeing an Outcome
Employers buying a course may require specific completion records, assessment standards or a fixed delivery deadline. Provide the actual agreement and insurance schedule for review. Identify warranties, indemnities, liability limitations and reimbursement obligations rather than sending only the paragraph with the requested limit.
Have qualified counsel assess what the provider is undertaking and the broker compare that responsibility with the offered terms. A requested endorsement and an accepted endorsement are different facts. Do not tell a college, employer or landlord that every contract requirement is met merely because a certificate has been issued.
Review marketing commitments as part of the same process. Promising that every graduate will qualify for a credential or perform independently can be materially different from describing the actual educational service. Use accurate course claims supported by the responsible education professionals instead of relying on insurance to absorb an overbroad promise.
If another organization resells your course, clarify whose terms the learner receives and which party handles refunds or complaints. A reseller can change the customer relationship without changing your lesson material. The submission should disclose the arrangement so the insurer is reviewing the service as it reaches the actual buyer.
Test a Fictional Practical Course Against the Submission
Imagine a specialist provider booked to teach an employer's maintenance staff a classroom module. The employer later asks for a workshop session using its own operational component. The provider also plans to bring a leased demonstration unit. This is a fictional example about scope and property responsibility, not a training recommendation or BWI customer case.
Before treating the change as incidental, the provider identifies the revised activities, supervision, equipment ownership and customer agreement. Qualified personnel address the technical and educational requirements, while the insurance contact reviews the changed facts. The original classroom description should not be presented as confirmation that all practical work has been accepted.
If the demonstration unit is damaged, the property review would need the lease, location, condition and actual event. If the customer separately complains about instruction, the relevant service and allegation would need their own analysis. Neither outcome can be established from the course name or the fact that both concerns arose during one visit.
Use the example when preparing terms to identify changes that require a further conversation. The objective is to make responsibilities visible before selling the expanded course. A customer request, instructor agreement and insurer response each need to be retained for the purpose they actually serve.
Plan for Interrupted Courses and Missing Records
Discuss any business income and extra expense protection using the offered trigger, limits, waiting periods and relevant dependencies. Damage to a provider's training equipment can raise a different question from ordinary breakdown, a canceled venue or an instructor's absence. Lost bookings are not automatically covered merely because a course cannot proceed.
Keep commercial rescheduling and refund arrangements clear independently of insurance. A backup classroom or another training provider may be useful, but its availability and customer acceptance need agreement. Do not promise reimbursement from an insurer before the appropriate claim contact has reviewed the actual facts and terms.
Protect learner, assessment and completion records through the systems your organization actually uses. Explain third-party access and retention arrangements where requested. Regulatory, contractual and privacy requirements need qualified review; an insurance guide cannot supply a universal retention period or permission to share student information.
If a complaint, damage event or potentially reportable circumstance occurs, follow the applicable policy notice process and preserve relevant records. Obtain appropriate guidance before admitting liability or agreeing to payment. A new quote application is not the reporting route for an existing allegation.
Prepare a Maintenance Training Insurance Review With BWI
Bring the course inventory, student and customer types, instructor roles, locations, regulatory status where applicable, equipment ownership schedules and representative agreements. Identify practical work involving customer property, remote instruction, outside specialists and planned expansion. Include current policies and the activity and complaint information requested for an established business.
Compare proposals against the same operation. Record the intended treatment of instruction, injury allegations, owned equipment, customer property, travel, electronic records and contractual requirements. Mark exclusions and unresolved conditions beside the premium so a cheaper quotation is not mistaken for equivalent protection.
Start a commercial aviation quote review with BWI or call 866 788 6291. Explain that the submission concerns maintenance education and describe the practical work in full. Confirm suitable options, accepted services, insured entities, endorsements and effective dates in the final documents before relying on coverage.
Sources and further reading
Continue Reading


