

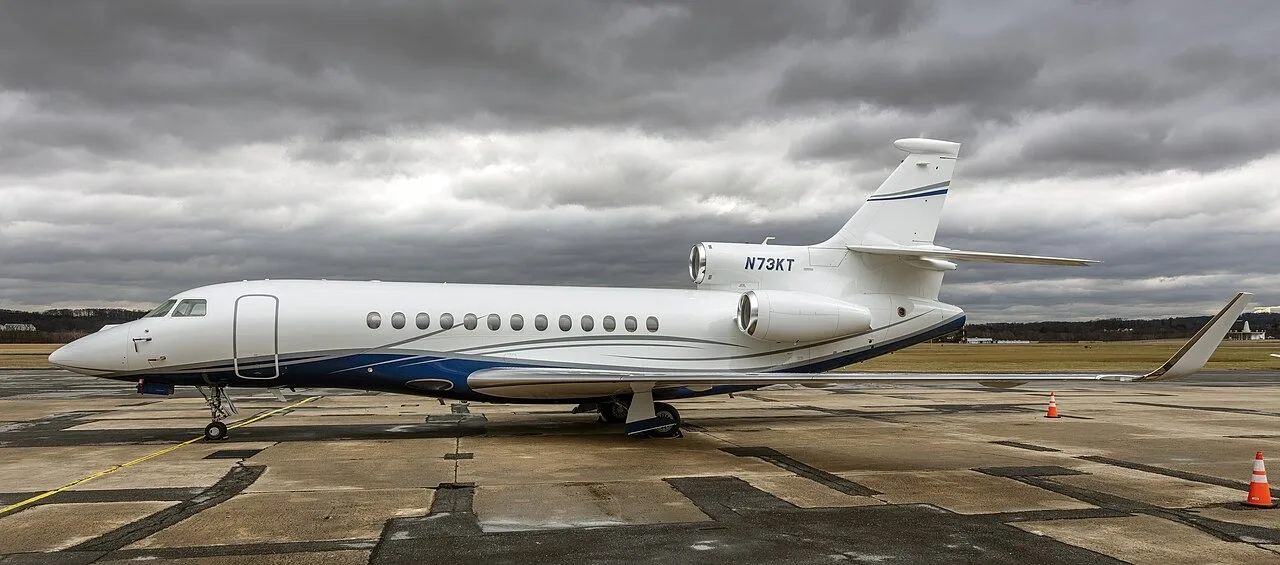
A company buying its first Falcon is establishing an aviation operation as well as acquiring an aircraft. Insurance needs to follow that operation: the entity that owns the jet, the businesses using it, the people flying it and the agreements supporting it. Reviewing those relationships before delivery is more useful than asking for a premium against an aircraft value alone.
A new corporate flight department may begin with an experienced captain and a straightforward travel plan. It can still involve a separate aircraft LLC, a parent company, a lender, contract pilots and several service providers. Each has a different role. A clear submission helps BWI present the account without expecting an underwriter to infer the structure from a company name.
This guide focuses on forming the insurance file for a new Falcon flight department. It supports BWI’s existing Falcon jet insurance page. Use it to organize the decisions that connect the company’s purchase, staffing and travel plans to the coverage being requested.
Start with a description of the company operation
Explain why the company is buying the Falcon and how it expects to use it. Identify the principal business, regular passengers, approximate flying activity and anticipated regions of operation. Distinguish an established travel need from an ambitious future schedule. The insurance submission should describe what management intends to implement, including decisions still awaiting approval.
Describe whether the operation will be staffed internally, supported by a management provider or developed in stages. An outside company may supply pilots without owning the aircraft. An aircraft LLC may own the jet without employing anyone. These are useful distinctions because a single phrase such as “corporate ownership” does not explain who is responsible for each activity.
Prepare a short organizational summary that finance, aviation management and BWI can all understand. Use legal entity names consistently. Identify the person authorized to answer questions and request insurance changes. That practical starting point helps keep the submission connected to the company’s approved plan instead of several competing descriptions circulating among advisers.
Map the owner users and service providers
List the aircraft owner, parent or affiliated businesses, management provider and any lessee or other proposed user. For each, record its role and the supporting agreement. Ask BWI how the relevant interests should be considered under the offered insurance. Ownership, operational responsibility and insured status should not be treated as interchangeable concepts.
Related companies deserve particular attention. A business group may refer to all its entities by the same trading name while contracts use different legal names. Give the insurance team the supported structure and proposed use by each entity. Ask the appropriate legal and tax advisers to resolve ownership and use questions that extend beyond an insurance application.
Keep service providers separate from aircraft users. A maintenance facility, hangar operator and contract pilot may each ask for insurance evidence, but their interests differ. Submit the request and relevant agreement before promising wording. The correct response depends on the role, proposed policy and insurer’s acceptance rather than the length of a list of names.
Select the aircraft facts that belong in underwriting
Provide the exact Falcon model, serial number, registration, year and equipment configuration. A 2000-series aircraft and a 7X or 8X should not be presented as an undifferentiated “Falcon jet.” The purpose is not to reproduce the sales brochure; it is to identify the aircraft, its value and the operation the insurer is being asked to consider.
For a pre-owned purchase, coordinate requested maintenance, modification and damage-history information with qualified technical advisers. For a new delivery, distinguish the delivered configuration from later work. Make inspection findings and pending questions visible through the proper channels. Insurance does not replace technical due diligence or establish that an aircraft is ready for service.
Use consistent aircraft information in the purchase file, financing instructions and insurance submission. If registration or ownership details will change, identify the supported present information and expected amendment. A mismatch should be resolved before the documents are relied on, rather than left for the closing team to interpret on the day funds move.
Define the people who will fly
Prepare an individual record for each proposed pilot. Include the experience, qualifications, recent activity and training information the application requests. Distinguish experience in another Falcon model from experience in the purchased aircraft. An experienced captain can still have model-transition needs, and a submission is stronger when it explains them accurately.
Identify the expected crew combinations. If the department will use employee pilots for regular trips and contract pilots for relief, describe both. Ask how each person or applicable pilot qualification provision is reviewed under the offered terms. Employment by a respected company is not, on its own, evidence that a pilot meets the aircraft owner’s policy conditions.
Discuss the hiring sequence. A company may close before its second permanent pilot begins work. Provide the interim staffing plan instead of assuming the eventual team is already in place. Ask BWI what needs to be accepted for delivery and the early operation, then update the file as permanent appointments and training are completed.
Connect manufacturer support to the training plan
Dassault’s Falcon fleet support information describes operational assistance, aircraft briefings and training resources. These can help a new department identify the technical support available for its aircraft. Confirm the services and course arrangements directly with the responsible providers for the particular model and crew.
Present the proposed initial, differences or recurrent training to BWI with accurate provider and course details. Ask which conditions apply under the insurance offer and what completion records are required. Manufacturer support and course availability are useful planning facts, but they do not independently approve a pilot under an aircraft insurance policy.
Build training dates into staffing and delivery decisions. If a captain’s course moves, review the resulting flight plan and any proposed substitute. Keep regulatory qualifications, company operating standards and insurance conditions distinct. The relevant professionals should resolve each question within their responsibilities, with the accepted insurance arrangement documented before it is relied upon.
Establish a practical process for insurance changes
Choose who maintains the current aircraft and pilot records and who tells BWI when something changes. A flight department needs a usable communication process, not simply a completed application. Finance may know about a new lease while aviation personnel know about a new pilot; both facts can matter to the insurance review.
Keep a short change register containing the proposed change, requested effective date, supporting documents and response received. It can cover pilots, bases, use, aircraft value and named parties. Do not mark an item complete merely because someone sent an email. Record the decision and any remaining conditions so the department knows what has been accepted.
Make access practical for authorized personnel. The captain should be able to find relevant operating conditions and contact instructions; finance should be able to locate coverage documents and lender evidence. Sensitive pilot or company information should be delivered through appropriate channels rather than copied unnecessarily to everyone involved in the purchase.
Review hull value and liability as separate decisions
Present the requested physical damage value with purchase and configuration information. Ask how the policy’s valuation and settlement wording applies. Significant refurbishment or equipment work should be identified with its timing. A finance team should not assume that loan principal, purchase price and the amount requested for insurance necessarily answer the same question.
Then review available liability structures around the company’s operation and contractual obligations. Ask BWI to explain limits, applicable sublimits, insured parties and material conditions. A large hull value does not create a universal formula for liability. The company’s advisers and decision makers need a comparison of the options available for their account.
Record the decision in a way the company can revisit. State the information reviewed and the terms selected without inventing a promise that all future claims will fit that choice. Revisit the analysis when operations change. The first policy should establish an accurate starting arrangement rather than freeze the company’s exposure assessment indefinitely.
Examine agreements before promising insurance wording
Provide the relevant lender, hangar, management and service agreements early enough for review. Identify clauses requesting insured status, evidence, waivers or other insurance-related commitments. Have qualified counsel address the contractual obligations while BWI reviews the coverage being requested. A broker’s certificate should not be used to decide what an ambiguous contract means.
Ask whether the proposed policy can address each requested interest and what conditions or limitations apply. Additional insured, loss payee and other terms serve different purposes. Avoid offering a standard certificate as proof that every promise in a large management agreement has been met. The response should match the particular request and the issued wording.
Keep accepted endorsements and evidence with the agreement they support. If a service provider changes, review the replacement requirements rather than recycling the previous provider’s documents. Good filing makes it easier to see why an endorsement was requested and whether it still relates to the department’s current arrangement.
Describe territories and missions realistically
Prepare an outline of anticipated domestic and international use. Identify regions, likely destinations and unusual activities that need discussion. A Falcon’s range and manufacturer support network do not determine the territory accepted by an insurer. Give BWI enough information to review the intended operation before a new itinerary creates an urgent evidence request.
If charter, leasing or carriage for another party is contemplated, identify it separately from ordinary company travel. Ask appropriate aviation advisers about the operating structure and regulatory requirements. The FAA’s owner and operator resource explains why leasing and operational responsibility require care. Insurance acceptance does not establish regulatory authority.
Do not describe a business plan as a current operation unless it is one. A company can ask about future expansion while requesting a policy for a more limited present use. Make the distinction clear and obtain the necessary reviews before the expansion begins. That protects the accuracy of the original submission and the usefulness of later advice.
Include the hangar and maintenance interval
The aircraft may spend time at a seller, completion center or maintenance facility after ownership changes. Describe the location, custody and proposed work, along with any planned technical or delivery flights. Ask how the buyer’s insurance will be arranged during that interval instead of assuming responsibility begins only when the jet reaches the home airport.
Review equipment and property outside the installed aircraft separately. Tools, spare parts, office property and hangar interests may raise additional questions. Tell BWI what the department owns, leases or borrows and who has custody. An aircraft hull value should not be treated as a complete inventory of every asset supporting the flight department.
Keep service contracts and reporting instructions available. If damage or a possible claim is discovered, follow the applicable notice requirements and obtain qualified technical assistance. The department should preserve factual records without promising itself a coverage outcome. Maintenance findings and insurance decisions answer different questions even when they concern the same event.
Consider the department as an employer
A company hiring pilots and aviation staff is also taking on employment responsibilities. Give the appropriate insurance and legal advisers the supported employment arrangements and working locations. Ask which employee-related coverages need a separate review. Aircraft hull and liability insurance should not be assumed to resolve every obligation associated with employing a flight crew.
Contract personnel require a similarly accurate description. Identify who contracts with them, what work they perform and which insurance requests appear in the agreement. Their separate coverage does not automatically replace the aircraft owner’s review. Nor does acceptance as a pilot, by itself, establish every person’s insured status for every allegation.
Keep this work coordinated without turning one policy into a promised package of unrelated protection. BWI can review the aviation submission and help identify the coverage questions to address. Availability of other insurance products and market acceptance must be established for the account. Present open questions accurately instead of telling management they were resolved by purchasing the jet policy.
Test the plan against a delayed crew appointment
Consider an illustrative company that is ready to close on a Falcon while one permanent pilot’s start date moves back a month. The company wants to keep its first executive trip and proposes using a contract captain for delivery and early flights. That proposal changes the immediate staffing facts even if the long-term department plan remains intact.
First, update the pilot submission and training schedule. Explain which people will operate during the interim and which duties they will perform. Ask BWI what acceptance and evidence are needed. The contract pilot’s résumé, the permanent pilot’s later appointment and the company’s desired itinerary should be presented as separate facts rather than combined into an assumption of uninterrupted approval.
Next, update the responsibilities and custody timeline. Identify who accepts the aircraft, where it will remain and which agreements apply before the permanent team is complete. Have the relevant advisers resolve contract and operational questions. Obtain the insurance response before the department treats the early trip as ready to go.
Finally, close the interim arrangement deliberately when staffing changes. Submit the completed records and obtain any necessary policy updates. This example does not predict an insurer’s decision. It shows how a new department can keep a single scheduling change from becoming several undocumented changes to the aircraft operation.
Give company decision makers a usable coverage summary
Prepare a short decision summary after BWI has presented the available proposals. Identify the aircraft, intended operation, proposed policy period and the parties the submission describes. State the hull value and liability structure being compared, then list the material pilot, training, territory or use conditions. Management should be able to see the insurance decision without reading every application attachment first.
Show unresolved matters separately from accepted terms. A requested endorsement, a lender wording question and a future pilot appointment should not appear in the summary as completed simply because someone expects a favorable response. Record the responsible person and the event that will close each item. This makes approval meaningful: the company knows what it is choosing and what must still happen before relying on the arrangement.
Keep the summary tied to the dated proposal and subsequent issued documents. If management approves one option and the aircraft configuration or ownership structure later changes, return the changed facts for review. An internal approval does not require the insurer to accept a revised submission, and an insurer’s response does not resolve every company governance requirement. Both records should reflect the transaction that actually proceeds.
After placement, replace preliminary documents with the appropriate final evidence while retaining the earlier decision record. Give authorized aviation and finance staff access to the information relevant to their duties. This is a practical way to connect the purchase decision to daily administration without treating an internal memo as a substitute for the aircraft policy or its endorsements.
Falcon flight department insurance questions
Can one policy protect every company in our group
Ask BWI to review the ownership and use structure rather than assuming group membership creates coverage. Provide legal names, roles and relevant agreements. Available wording depends on the submission and insurer’s acceptance. Have company advisers resolve the legal relationships while the insurance review addresses the interests being requested.
Does hiring professional pilots guarantee lower premiums
No particular premium result should be assumed. Submit the pilots’ supported qualifications, training and proposed operation. Compare the terms offered for that account, including conditions and coverage. A professional crew changes the facts to be evaluated; its involvement does not establish a universal discount or approval.
Should we wait until delivery to submit lender requirements
Submit them before document deadlines wherever possible. Requested evidence or wording may need review and clarification. Give BWI the instructions and relevant agreement so outstanding questions can be addressed while the closing schedule remains flexible. A certificate should reflect an accepted arrangement rather than substitute for one.
Can manufacturer training replace the insurance review
No. Provider support helps establish what training is available or completed. Ask the insurer, through BWI, how that course and pilot fit the offered terms. Keep course evidence and the insurance response together, and resolve any further conditions before changing how the aircraft is operated.
Request a Falcon corporate insurance review from BWI
Send BWI the aircraft details, ownership structure, proposed pilots, training schedule and first-year operating outline. Add lender and management requirements, expected territories and any interim arrangements before the permanent department is ready. A complete submission helps the team review the company operation behind the aircraft purchase.
Request a Falcon insurance review and quote from BWI. Ask for an explanation of available hull and liability terms, insured interests and pilot conditions. Establish the insurance file before delivery so the new flight department begins with a documented arrangement that can be maintained as the company’s aviation needs develop.
Sources
Continue Reading


