

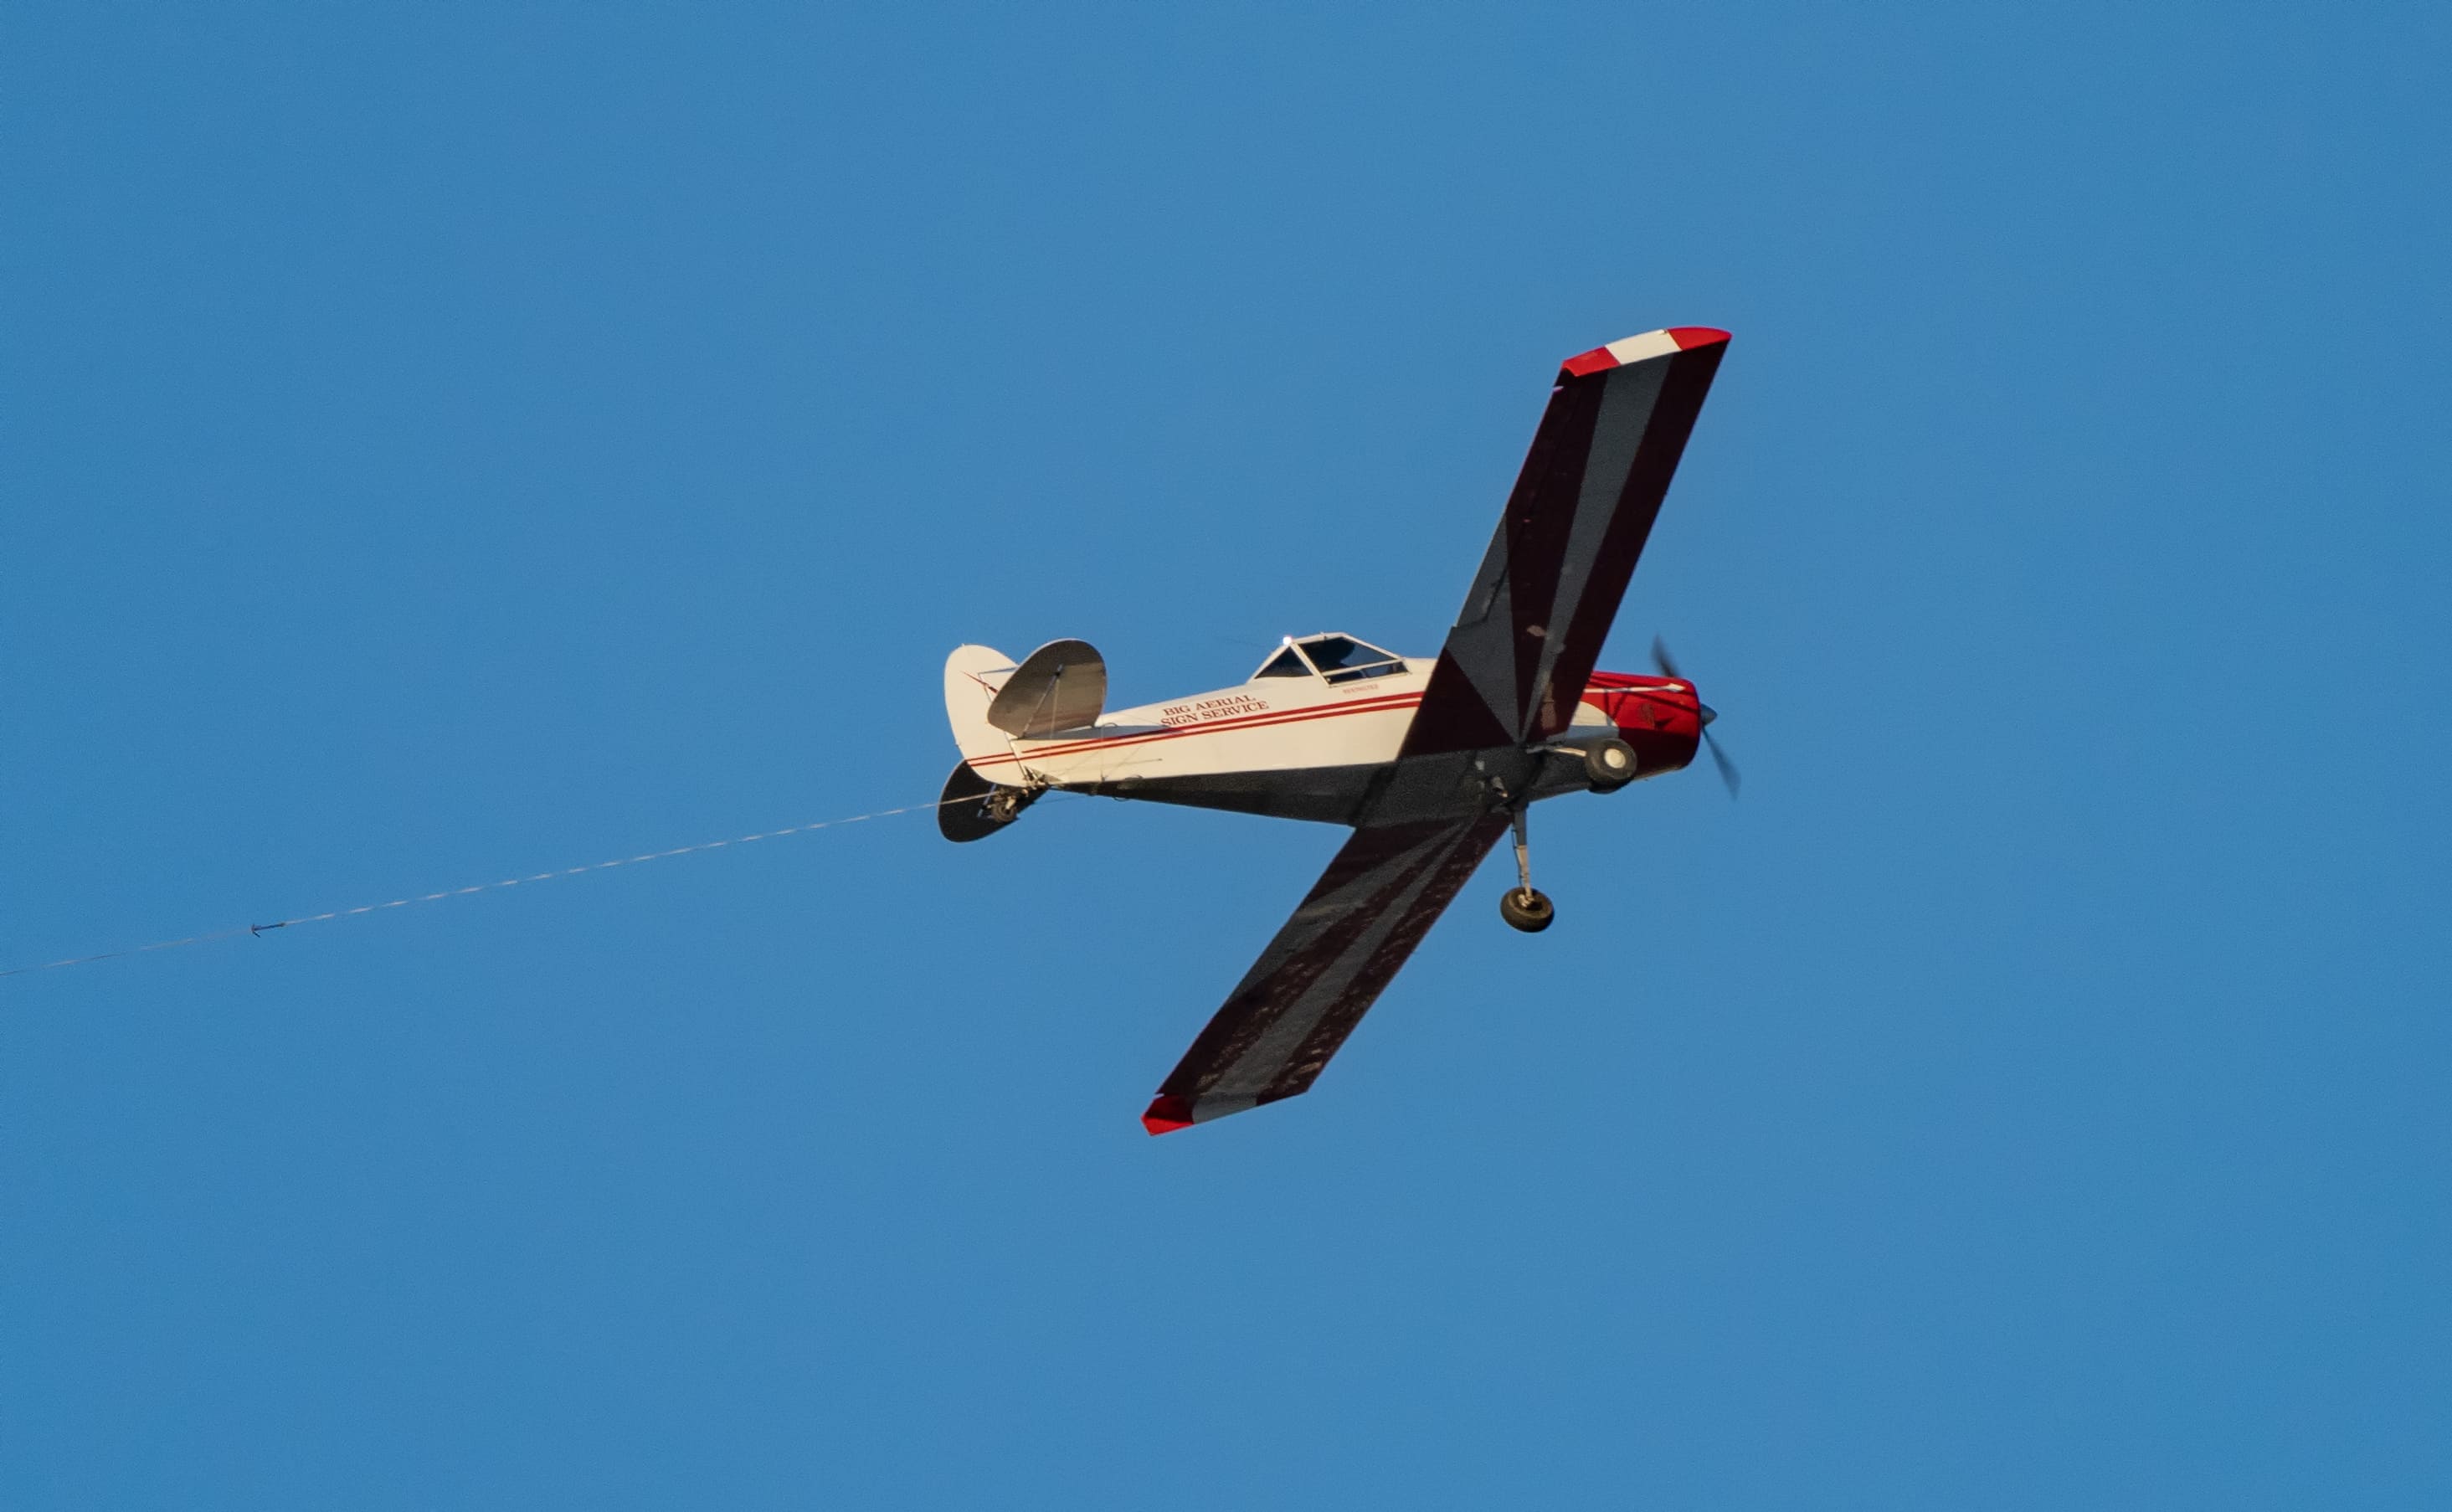
Banner towing aircraft insurance should be reviewed around the aerial advertising operation you actually intend to run. Tell BWI which business signs the advertising agreements, which aircraft and pilots perform the work, where the operation is based and who handles the banners on the ground. A policy arranged for ordinary personal flying should not be treated as confirmation that paid towing work has been accepted. Ask for the response before making promises to an advertiser or committing an airplane to a campaign.
This guide helps an owner or aerial advertising business prepare that insurance discussion. It addresses aircraft, equipment, people, seasonal contracts and evidence of coverage. It does not teach banner pickup, release, towing technique or flight planning. Operating permissions, aircraft suitability and crew procedures belong with qualified aviation professionals and the responsible authorities. The insurance file should describe the resulting operation accurately rather than use insurance as a substitute for those decisions.
For the broader business discussion, see BWI commercial aviation insurance. Describe banner towing specifically in your submission.
Describe the advertising business and its contracting role
Begin with the legal business that sells the service. An advertiser may book directly with the aircraft operator, through an advertising agency or through another aerial advertising company. Identify who invoices the customer, who provides the airplane and who accepts responsibility for the completed assignment. Those roles matter when an insurer reviews activities and contractual promises. A familiar trading name alone may not identify every legal party that needs consideration.
Explain whether the business operates its own aircraft, leases airplanes or arranges work by other operators. If the same company also offers photography, instruction or another flying service, list those activities separately. A description limited to advertising can leave out other operations using the same aircraft or personnel. Give BWI a complete business description while keeping the proposed banner work specific enough to evaluate on its own facts.
Give the insurer a realistic seasonal operating picture
Describe the expected season, geographic area, airports and proposed volume of work in the detail requested. A company flying recurring campaigns from one base presents a different submission from a business taking occasional assignments at changing locations. Identify temporary bases and periods when aircraft or equipment will be away from their normal storage location. Estimates should be labeled as estimates, with material changes returned for review.
Include positioning, ground preparation, custody and return to storage in the business description. The minutes of banner display do not describe the entire assignment or every property interest. Identify each relevant stage without treating it as a list of automatically insured activities.
Keep operating authority distinct from insurance acceptance
Current 14 CFR 91.311 addresses towing other than the glider-towing subject in section 91.309 and requires compliance with an Administrator-issued certificate of waiver. Establish the actual operating framework directly with the FAA and qualified aviation professionals. Do not use an old notice or another operator’s document as authority for the proposed business. This guide supplies no waiver application procedure or individual approval decision.
Provide the insurance team with the confirmed operating framework and any relevant restrictions or unresolved issues. Insurance acceptance does not issue a waiver or establish that a location is appropriate for a flight. Likewise, an operating authorization does not rewrite the aircraft policy. Keep the documents connected by the same accurate operation description, while recognizing that they answer different questions and may be issued by different parties.
Build a banner towing insurance submission record
A useful submission connects the business, aircraft, pilots, ground arrangements and customer agreement. The comparison below identifies subjects to organize before requesting terms. It is a preparation aid for the insurance discussion, not an operating checklist or a statement that each item will be insured. Add the real legal names, aircraft details and proposed dates rather than sending a generic brochure that leaves those facts unstated.
Choose a person to maintain the record during the season. Campaigns can change after quoting when a customer adds dates, another aircraft becomes necessary or a temporary base is proposed. Keep a dated account of those changes and the actual responses. That allows the business to distinguish what was described, what was accepted and what still needs attention before a revised assignment is represented as ready.
| Submission subject | Information for review |
|---|---|
| Business | Legal operator advertiser and agency roles |
| Aircraft | Ownership values configuration and intended use |
| People | Pilots ground crew and employment arrangements |
| Season | Bases locations planned dates and expected work |
| Contracts | Client insurance provisions leases and subcontracting |
| Property | Aircraft banners detached equipment and storage |
Identify the aircraft and any towing equipment
Supply the make, model, registration, ownership and proposed aircraft value requested by the insurer. Explain the aircraft’s intended advertising use and identify relevant towing equipment or configuration information for review. Aircraft suitability, installation approvals and maintenance decisions require qualified technical review. An insurer receiving an equipment description should not be mistaken for an engineer or maintenance professional approving the installation or determining the airplane’s operating capability.
Distinguish equipment attached to an aircraft from banners, spare components, handling equipment and other property stored separately. Explain who owns each significant item and where it is kept. A hull value is not an automatic inventory of everything the business uses. Ask how the actual contract treats attached equipment, detached items and separately owned property instead of assuming that any item associated with an aircraft belongs within the same coverage description.
Separate the aircraft schedule from the banner inventory. For a fictional campaign, the airplane may be owned by one company, the reusable banner frames by another and the printed message material by the advertiser. Record the real owners and relevant values in the actual submission. An advertising fee or the replacement cost of a complete campaign is not automatically the insured value of any one item.
Review pilots and substitutions before the busy season
Identify the pilots expected to perform the work and provide the experience information the insurer requests. Present total time, relevant aircraft experience and proposed roles accurately without substituting a marketing biography for the application questions. Ask how the issued policy addresses authorized pilots and any conditions that apply. An operator’s approval of a pilot does not independently establish compliance with every insurance requirement.
Plan how a substitution will be reviewed if the regular pilot becomes unavailable. A customer deadline is not evidence that another pilot is acceptable under the policy. Keep the proposed substitute’s information with the relevant response and any required documentation. The purpose is to avoid treating a general discussion from the beginning of the season as permission for every later combination of pilot, airplane and assignment.
Include the ground crew and their employment arrangements
Describe the people who prepare, handle or supervise the ground portions of the operation. State whether they are employees, business owners, contractors or personnel supplied by another organization. The insurance discussion needs their actual responsibilities, not simply a headcount. Qualified advisers should establish the employment and operational arrangements; a label such as independent contractor should not be used to decide insurance obligations by itself.
Ask the appropriate insurance professionals which policies address the employer’s interests and the different activities disclosed. Aircraft liability should not be assumed to replace every workplace or business policy. If an airport, customer or other party provides personnel, give the relevant agreement to the reviewers. Keep responsibilities understandable so that someone helping with one stage is not casually described as covered by another organization’s insurance without supporting terms.
Separate aircraft damage from liability to other people
Review proposed physical damage coverage using the actual aircraft value, deductibles, covered states and relevant limitations. Ask how the policy addresses the disclosed banner operation rather than assuming an aircraft is treated identically during every activity. A broad statement that hull coverage is included does not explain all exclusions, conditions or deductibles. Use the issued wording and endorsements when comparing the response with the operation.
Liability questions concern different interests, including allegations involving people or property outside the aircraft. Ask about the relevant limits, insured parties and restrictions for the submitted work. A large headline limit does not establish that every contractual obligation or business activity is included. Keep the aircraft’s own damage question separate from third-party allegations so the business does not mistake one part of the proposal for a complete answer to both.
Read the advertiser agreement before promising insurance evidence
Obtain the customer’s actual insurance provisions early in the booking process. Identify the legal names, requested limits, evidence recipients, dates and activities. An advertising agency may pass along requirements written for several types of vendors, and not every provision will fit an aircraft operation in the same way. Send the wording for review before stating that the business can meet it or adding insurance commitments to a sales proposal.
If additional insured status or another policy change is requested, ask whether it is available for the actual relationship and on what terms. A certificate reports supported information; it does not independently expand the policy or create a requested endorsement. Give the customer the evidence that corresponds to the insurer’s response. If a requirement remains unresolved, keep it visible rather than using a familiar certificate format as a substitute for an answer.
Examine cancellation promises and advertising performance obligations
Advertising contracts may discuss scheduled dates, weather interruptions, substitutions, refunds or the promised service. Have qualified counsel explain the business’s commitments and give relevant insurance provisions to BWI. A duty to refund a customer or repeat an assignment should not automatically be treated as an insured aircraft loss. The contract and the insurance agreement serve different purposes and should be compared using their actual language.
Avoid describing every customer complaint as liability arising from an aircraft accident. A disagreement about the message, timing, visibility or completed service can raise different questions from physical injury or property damage. This guide does not promise protection for advertising performance or lost revenue. The useful step is to identify those obligations before pricing the job, then understand which responsibilities the business retains under the offered arrangements.
Explain airport access and temporary ground locations
Identify the airports and other proposed ground locations through the appropriate project channels. Provide relevant leases, access agreements and insurance requirements for review. Permission to store an aircraft at an airport may not explain every activity the business intends to conduct there. Qualified airport and aviation professionals should establish the permitted arrangements, operating areas and responsibilities without relying on an insurance certificate as site authorization.
If the business moves to a temporary base, explain aircraft storage, equipment custody and any services supplied by another party. Ask what information is needed before treating the new arrangement as equivalent to the original base. A short assignment can still involve a different agreement or property interest. Maintain the final site documents alongside the insurance response so later staff can see the facts on which the review was based.
Account for equipment transport and off season storage
Banners and related business equipment may spend time in a vehicle, trailer, workshop or storage building. Describe ownership, values and custody when asking which insurance arrangements may be relevant. An aircraft policy should not be assumed to insure a road vehicle or every item carried in it. Likewise, a general business property description may leave questions about aviation equipment or property away from a listed location.
During the off season, explain where aircraft and equipment remain and whether any flying or business activity continues. Do not assume reduced bookings automatically change the policy or eliminate all exposures. Ask about the actual options and conditions before requesting a change, and understand what is needed before the next season starts. Preserve the response so a later employee does not restart work based only on last year’s operating pattern.
Review leased aircraft and subcontracted flights accurately
If another owner supplies the airplane, identify the lease or other arrangement and the parties’ insurance responsibilities. Explain who maintains custody, who provides pilots and who contracts with the advertiser. A lease provision requiring insurance does not prove the required coverage has been issued. Obtain the actual evidence and have the relevant terms compared with the agreement, including any outstanding conditions or exclusions affecting the disclosed operation.
When another operator performs part of a campaign, clarify who is selling the service and who is conducting the flight. Do not treat the subcontractor’s certificate as a complete answer to your company’s own interests. Each party’s activities and commitments need appropriate review. If the arrangement changes from referral to subcontracting or from one aircraft to several, return that difference before assuming the original response still describes the project.
Compare quotes against one consistent operation description
Compare terms using the same operator, aircraft, pilots, locations, values, limits and advertising activity. Read the conditions alongside the premium and identify outstanding requirements. A quote for personal flying is not an equivalent alternative for paid banner work. BWI’s sample policy resources are educational references; the actual offered wording and issued documents establish the insurance arrangement.
Work through a fictional summer advertising campaign
Imagine a fictional advertiser, Harbor Foods, buying a July campaign through Lake Agency. The agency contracts with Field Advertising LLC, which operates the airplane. These invented names illustrate distinct roles; no BWI customer or accepted arrangement is described. The booking identifies the advertiser as the message buyer, the agency as the contracting intermediary and Field as the flying business. The insurance inquiry uses those actual relationships rather than listing everyone as the operator.
The agency later asks Field to add August dates and use a second aircraft provider for part of the work. Field identifies whether it is merely referring the customer or accepting the campaign while subcontracting flights. It supplies the proposed provider, aircraft, pilots and agreement for review. Qualified aviation advisers address operating authority; legal advisers address the commercial promises. The second provider’s certificate is retained as its evidence, separate from the response concerning Field’s own duties.
When the agency requests revised insurance evidence, Field sends the complete provision, legal names, dates and relationship. An earlier certificate for the original airplane does not confirm the expanded campaign. If a requested status or promise cannot be supported, it remains unresolved before evidence is issued. A refund for an unperformed advertising date is considered separately from an allegation of aircraft damage; the business does not promise either outcome will be reimbursed.
Keep booking changes and incident records usable
If an incident, allegation or potentially reportable concern occurs, follow the policy’s requirements and obtain guidance from the appropriate insurer. Preserve facts and relevant records without guessing about fault or promising reimbursement. An initial customer conversation should not settle the insurance outcome. Keep the claims process distinct from routine service recovery while ensuring that potentially relevant information reaches the proper parties through their established channels.
Frequently asked questions
Can a personal aircraft policy be used for paid banner towing
Do not assume it can. Describe the proposed aerial advertising work and ask how the actual policy addresses it. The aircraft use, pilots, business entity and relevant conditions need review before the business relies on the arrangement or promises insurance evidence to a customer.
Does an FAA waiver prove that the operation is insured
No. Operating authority and insurance terms answer different questions. Establish the current operating requirements through the FAA and qualified professionals, then provide the confirmed proposal to the insurance team. Read the issued policy response separately from the operating documents.
Are banners and ground equipment automatically included in hull coverage
Do not assume every business asset is part of the insured aircraft. Identify equipment, ownership, values and custody, including items stored or transported separately. Ask how the actual policies define the property and which arrangements may address the disclosed interests.
Does a certificate satisfy every advertiser insurance requirement
A certificate does not independently expand coverage or create a policy endorsement. Supply the actual requirements, legal names and dates for review. Use evidence supported by the issued arrangement and identify unresolved provisions before the customer relies on it.
Will insurance reimburse a canceled advertising booking
A cancellation or refund obligation is not automatically an insured aircraft loss. Have the agreement and relevant circumstances reviewed. Ask about the actual wording rather than treating a flight-related business expense or performance dispute as a guaranteed insurance payment.
Request a banner towing insurance review from BWI
Bring BWI your business description, aircraft and ownership information, pilots, seasonal plans, locations and customer insurance requirements. Include relevant leasing, subcontracting and ground arrangements. Explain which operating facts are confirmed and which remain proposed so the inquiry follows the real business rather than a broad advertising label.
Request a commercial aviation insurance review and quote from BWI before committing to a campaign on an unsupported coverage assumption. Compare the response with the final operation and issued documents, then return material changes for review. A clear submission gives your business a useful record from the first customer discussion through the season’s changing aircraft, people and contracts.
Continue Reading


