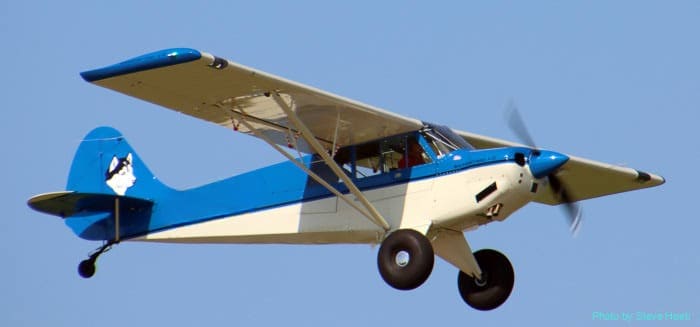
The Aviat Husky occupies a unique place in general aviation.
It combines exceptional short-field performance, rugged utility, modern construction, and backcountry capability into one of the most respected tailwheel aircraft flying today.
Whether operating from a paved runway, a mountain strip in Idaho, a ranch in Wyoming, or a gravel bar in Alaska, the Husky has become a favorite among pilots who value capability and adventure.
From an insurance perspective, the Husky is equally unique.
Because of its tailwheel configuration, frequent backcountry use, and often high aircraft values, insurance companies evaluate Huskies differently than most conventional aircraft.
The good news for qualified operators is that today’s insurance market remains competitive.
Insurance companies continue to actively pursue experienced tailwheel pilots with strong training records and clean claims histories.
Understanding what drives underwriting decisions can help owners secure stronger coverage options and potentially improve long-term insurance costs.
Get Your Aircraft Insurance Quote With BWI>>
Why The Husky Remains Attractive To Insurance Companies
Insurance companies generally like predictability.
The Husky offers several characteristics that create underwriting confidence.
The aircraft provides:
- Proven operating history
- Strong safety record
- Excellent backcountry capability
- Modern construction
- Strong owner community
- Extensive maintenance support
- Exceptional utility
Insurance carriers have decades of operational data available.
That familiarity helps reduce uncertainty.
And reduced uncertainty generally creates stronger competition among carriers.
The Husky Models Included In Today’s Market
Common Husky aircraft include:
- A-1
- A-1A
- A-1B
- A-1C
- A-1C-180
- A-1C-200
Many aircraft also include:
- Bushwheel installations
- Float conversions
- Amphibious floats
- Ski installations
- STOL modifications
- Avionics upgrades
While these aircraft share the same heritage, insurance companies do not necessarily evaluate them identically.
Factors such as aircraft value, modifications, pilot experience, and operational profile can significantly influence underwriting outcomes.
Aircraft Value Continues To Drive Premium Changes
One of the largest factors affecting insurance premiums today is aircraft value.
Consider the difference between:
- An older Husky valued at $150,000
- A well-equipped Husky valued at $300,000
- A newer Husky valued at $500,000+
- A highly customized Husky valued at $700,000+
The insurance company’s exposure changes dramatically.
As hull values increase, premiums generally increase as well.
This explains why two operators with similar qualifications may receive very different insurance quotes.
Tailwheel Experience Remains Critical
Few underwriting factors carry more weight than tailwheel experience.
Insurance companies carefully evaluate:
- Total tailwheel time
- Recent tailwheel activity
- Husky experience
- Annual training history
Consider these two pilots.
Pilot A:
- 2,000 hours total time
- 1,000 hours tailwheel
- 300 hours Husky time
Pilot B:
- 2,000 hours total time
- 25 hours tailwheel
- 10 hours Husky time
The insurance company often views those risks very differently.
For many owners, tailwheel experience remains one of the most important drivers of insurance pricing.
Backcountry Operations Continue To Influence Underwriting
One of the most important underwriting considerations within the Husky market involves operational environment.
Insurance companies evaluate:
- Grass strips
- Gravel bars
- Ranch strips
- Mountain strips
- Remote airstrips
- Off-airport operations
The more demanding the operating environment, the more emphasis underwriters often place on pilot qualifications and experience.
Alaska Flying Receives Additional Attention
Many Huskies operate in Alaska.
Insurance companies often evaluate:
- Alaska flying experience
- Remote operations
- Seasonal usage
- Float experience
- Ski experience
Qualified Alaska operators continue to enjoy strong carrier interest.
However, underwriting requirements often differ from similar aircraft operating in the lower 48 states.
Float Operations Create Additional Considerations
Many Huskies operate on floats.
Insurance companies frequently evaluate:
- Float time
- Amphibious experience
- Water operations history
- Float training
Pilots with documented float experience generally receive stronger underwriting consideration than those transitioning into float operations.
Get Your Aviat Husky Insurance Quote With BWI>>
Ski Operations Continue To Grow
Many Husky owners utilize skis during winter operations.
Insurance companies often evaluate:
- Ski experience
- Winter operations
- Mountain flying
- Seasonal activity
As with float operations, ski flying often involves unique underwriting considerations.
Recent Flight Activity Matters
Insurance companies understand that proficiency is perishable.
A pilot who regularly flies tailwheel aircraft often receives stronger underwriting consideration than a pilot with limited recent activity.
Underwriters frequently review:
- Hours flown in the past 12 months
- Recent tailwheel activity
- Recent Husky experience
- Overall recency of flight activity
Consistent flying creates confidence.
And confidence creates competition among insurance carriers.
Claims History Remains One Of The Largest Factors
Nothing consistently impacts insurance pricing more than claims history.
Insurance companies carefully evaluate:
- Previous claims
- Loss severity
- Claim frequency
- Recent losses
Pilots with clean records often benefit from:
- Better pricing
- More carrier options
- Increased underwriting flexibility
Regardless of aircraft type, maintaining a clean claims history remains one of the most valuable long-term insurance strategies available.
Which Insurance Companies Are Most Active In The Husky Market?
Several major aviation insurance carriers actively insure tailwheel and backcountry aircraft.
These include:
- Global Aerospace
- AIG
- Old Republic
- Starr
- USSIC
- IAT
- AIM
- Beacon
Each carrier evaluates risk differently.
One company may be highly competitive for recreational tailwheel pilots.
Another may focus on experienced backcountry operators.
A third may specialize in float-equipped aircraft.
This is one reason comparing multiple insurance options remains important.
How Husky Owners Can Improve Their Insurance Profile
There are several actions owners can take to improve underwriting outcomes.
- Build tailwheel experience
- Build Husky experience
- Complete transition training
- Participate in recurrent training
- Maintain recent flight activity
- Keep accurate logbooks
- Maintain a clean claims history
- Review hull value annually
Insurance companies consistently reward operators who demonstrate professionalism and commitment to safe operations.
What We Expect For The Rest Of 2026
Based on current market activity, conditions remain favorable for qualified Husky owners.
Insurance companies continue to show strong interest in experienced tailwheel pilots with strong operational records.
While individual renewals will vary based on aircraft value, pilot qualifications, training, and claims history, the market remains healthy and competitive.
For many operators, that competition creates opportunities to secure improved coverage and pricing at renewal.
Why Aircraft Owners Trust BWI
BWI Aviation Insurance helps aircraft owners compare coverage options from leading aviation insurance carriers.
Our team understands the underwriting considerations that influence pricing and carrier appetite for backcountry aircraft.
We help aircraft owners evaluate options based on their specific aircraft, experience level, and mission profile.
Final Thoughts
The Aviat Husky remains one of the most respected backcountry aircraft in aviation.
Its combination of performance, utility, reliability, and adventure capability continues to make it attractive to both operators and insurance companies.
While premiums are influenced by aircraft value, tailwheel experience, training, and claims history, today’s market remains favorable for qualified operators.
Whether you’re flying Idaho mountain strips, Alaska gravel bars, or your local grass runway, understanding how insurance companies evaluate risk can help you secure the most competitive coverage available and protect one of your most valuable aviation assets.
Continue Reading