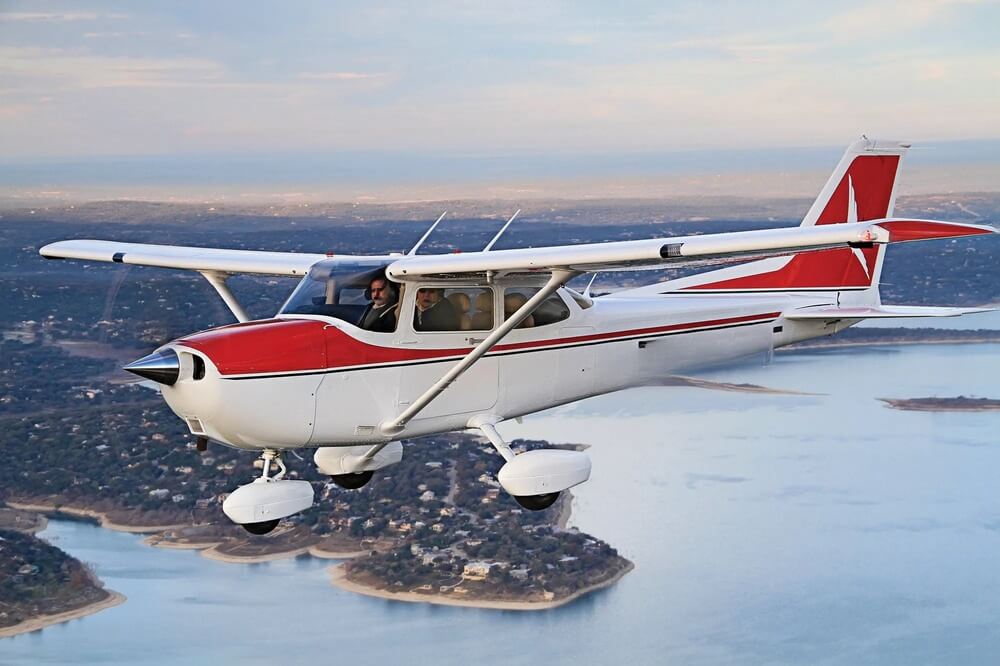
The Cessna 172 is one of the most insurable aircraft in general aviation.
That surprises many aircraft owners.
After all, the Skyhawk is used for everything from primary flight training and weekend flying to serious cross-country transportation, instrument flying, business travel, and family vacations.
The aircraft itself is incredibly versatile.
So why can one Cessna 172 owner receive multiple competitive insurance quotes while another owner struggles to find favorable options?
The answer is simple.
Insurance companies are not just evaluating the airplane.
They are evaluating the entire risk.
At BWI Aviation Insurance, we work with thousands of Cessna owners nationwide and help aircraft owners compare coverage through the leading aviation insurance carriers.
After reviewing thousands of aircraft insurance submissions over the years, one thing becomes very clear:
The pilot often matters more than the airplane.
Ask insurers what they need to assess your risk. Clear facts about your aircraft and flying can help you compare the available terms.
The First Thing Underwriters Evaluate Is The Pilot
The insurer reviews both the aircraft and the people who will fly it.
In reality, underwriters often spend significantly more time evaluating the pilot.
Consider these two examples.
Pilot A owns a Cessna 172S.
He has:
- 2,500 hours total time
- Instrument rating
- 600 hours in Cessna 172s
- Annual recurrent training
- No claims
- 100 hours flown last year
Pilot B owns the same aircraft.
He has:
- 250 hours total time
- No instrument rating
- 10 hours in type
- No recurrent training
- Limited recent flight activity
Those pilots represent very different risks.
The airplane didn’t change.
The pilot did.
That difference often has a greater impact on insurance pricing than the aircraft itself.
Total Flight Time Still Matters
One of the first numbers underwriters review is total flight time.
There is no magic number.
However, experience matters.
Insurance companies understand that experienced pilots have generally encountered:
- More weather situations
- More operational challenges
- More aircraft system issues
- More real-world decision making
A pilot with 2,000 hours generally presents a different risk profile than a pilot with 200 hours.
This does not mean lower-time pilots cannot get excellent coverage.
It simply means additional underwriting scrutiny may occur.
Time In Make And Model
After reviewing total flight time, many underwriters immediately focus on time in make and model.
For Skyhawk owners, this can be a major factor.
Aircraft commonly evaluated include:
- 172M
- 172N
- 172P
- 172R
- 172S
Insurance companies know aircraft-specific experience matters.
A pilot with hundreds of hours in a Cessna 172 generally presents a different risk than someone transitioning into the aircraft for the first time.
Ask about the insurer’s requirements before moving to a new aircraft type.
Instrument Ratings Carry Significant Weight
One of the most valuable qualifications a Skyhawk owner can possess is an instrument rating.
Insurance companies consistently favor instrument-rated pilots.
Why?
Because the rating shows:
- Additional training
- Better weather decision making
- Greater proficiency
- Stronger commitment to aviation safety
The Cessna 172 remains one of the most common IFR training and transportation aircraft in the world.
Many owners routinely fly:
- Business trips
- Family vacations
- Long cross-country flights
- Multi-state travel
Insurance companies know this.
Include your instrument rating and recent experience. Ask which pilot requirements apply to the proposed flights.
Get Your Cessna 172 Aircraft Insurance Quote With BWI Today>>
Recent Flight Activity Matters More Than Many Pilots Realize
One of the biggest surprises for aircraft owners is how much underwriters care about recent activity.
Insurance companies understand that proficiency is perishable.
A pilot who has:
- 3,000 total hours
but only flew:
- 5 hours last year
may create more concern than a pilot with:
- 1,000 total hours
who flew:
- 100 hours last year
Underwriters often review:
- Hours flown in the past 12 months
- Recent flight reviews
- Recent instrument experience
- Recent Cessna 172 experience
- Overall recency of activity
Consistent flying creates confidence.
And confidence creates competition among insurance carriers.
Claims History Is Still King
Nothing influences underwriting decisions more consistently than claims history.
Insurance companies carefully review:
- Previous claims
- Loss frequency
- Loss severity
- Recency of losses
Pilots with clean records often benefit from:
- Better pricing
- More carrier options
- Greater underwriting flexibility
A claim does not automatically make insurance difficult.
However, it often generates additional questions and underwriting scrutiny.
Insurance companies view prior losses as one of the strongest predictors of future outcomes.
Aircraft Value Has Become Increasingly Important
One of the biggest trends affecting Skyhawk owners today is rising aircraft values.
Consider the range of values currently seen within the Cessna 172 market.
An older 172M may be insured for:
- $60,000
- $75,000
- $100,000
A highly upgraded 172N may be insured for:
- $150,000
- $200,000
- $250,000
A newer 172S may be insured for:
- $300,000
- $400,000
- $500,000+
The insurance company’s exposure changes dramatically as aircraft value increases.
As a result, premiums often increase even when the pilot remains exactly the same.
Modern Avionics Can Influence Underwriting
Today’s Skyhawks often include sophisticated avionics systems.
Popular upgrades include:
- Garmin GTN navigators
- Garmin G3X Touch displays
- Garmin GI 275 instruments
- Garmin autopilots
- ADS-B systems
- Engine monitoring equipment
These upgrades often improve both safety and aircraft value.
List your avionics and relevant training. Ask whether they affect the insurer’s review.
However, increased hull value may also increase premium.
Training Creates Confidence
Few things create underwriting confidence like training.
Insurance companies consistently reward pilots who participate in:
- Flight reviews
- Recurrent training
- FAAST programs
- Safety seminars
- Simulator training
- Transition training
Training reduces uncertainty.
And underwriters dislike uncertainty.
Tell your agent about recent training and practice. Ask how the insurer will assess that experience.
Aircraft Usage Matters
Insurance companies also evaluate how the aircraft is used.
Common underwriting questions include:
- Personal use?
- Business use?
- Flight instruction?
- Rental operations?
- Instrument flying?
- Long cross-country travel?
Different missions create different risk profiles.
Explain how you use the aircraft so the insurer can assess the risk.
What The Best Cessna 172 Risks Have In Common
After reviewing thousands of Skyhawk insurance applications, certain patterns consistently emerge.
The strongest insurance risks often have:
- Instrument ratings
- Significant Cessna 172 experience
- Clean claims histories
- Annual recurrent training
- Strong recent flight activity
- Accurate logbooks
- Stable ownership histories
These characteristics create confidence among insurance companies.
And confidence often leads to better insurance outcomes.
Why The Cessna 172 Remains One Of The Most Insurable Aircraft In Aviation
Insurance companies generally like Skyhawks.
The aircraft offers:
- Predictable handling
- Extensive operating history
- Strong safety record
- Large owner base
- Excellent training resources
Combined with experienced pilots, those characteristics create attractive insurance risks.
This is one reason the Cessna 172 remains one of the most popular aircraft in general aviation.
Why Thousands Of Cessna Owners Trust BWI
BWI Aviation Insurance has helped thousands of Cessna owners secure coverage for their aircraft.
Whether you fly a 172M, 172N, 172P, 172R, or 172S, our team understands the underwriting factors that influence pricing and carrier appetite.
We help you compare insurance options for your aircraft, flying experience and planned use.
Final Thoughts
Many Cessna 172 owners assume insurance pricing is based primarily on the airplane.
The reality is very different.
Underwriters spend much of their time evaluating the pilot.
Experience, training, instrument proficiency, recent flight activity, claims history, aircraft value, and operational discipline all play major roles.
The good news is that many of those factors are within your control.
Ask how your flying history affects the terms you are offered. Review your options again when your training, aircraft or use changes.
And in today’s competitive aviation insurance market, that knowledge can be extremely valuable.
bwifly.com / 800-666-4359
Continue Reading