

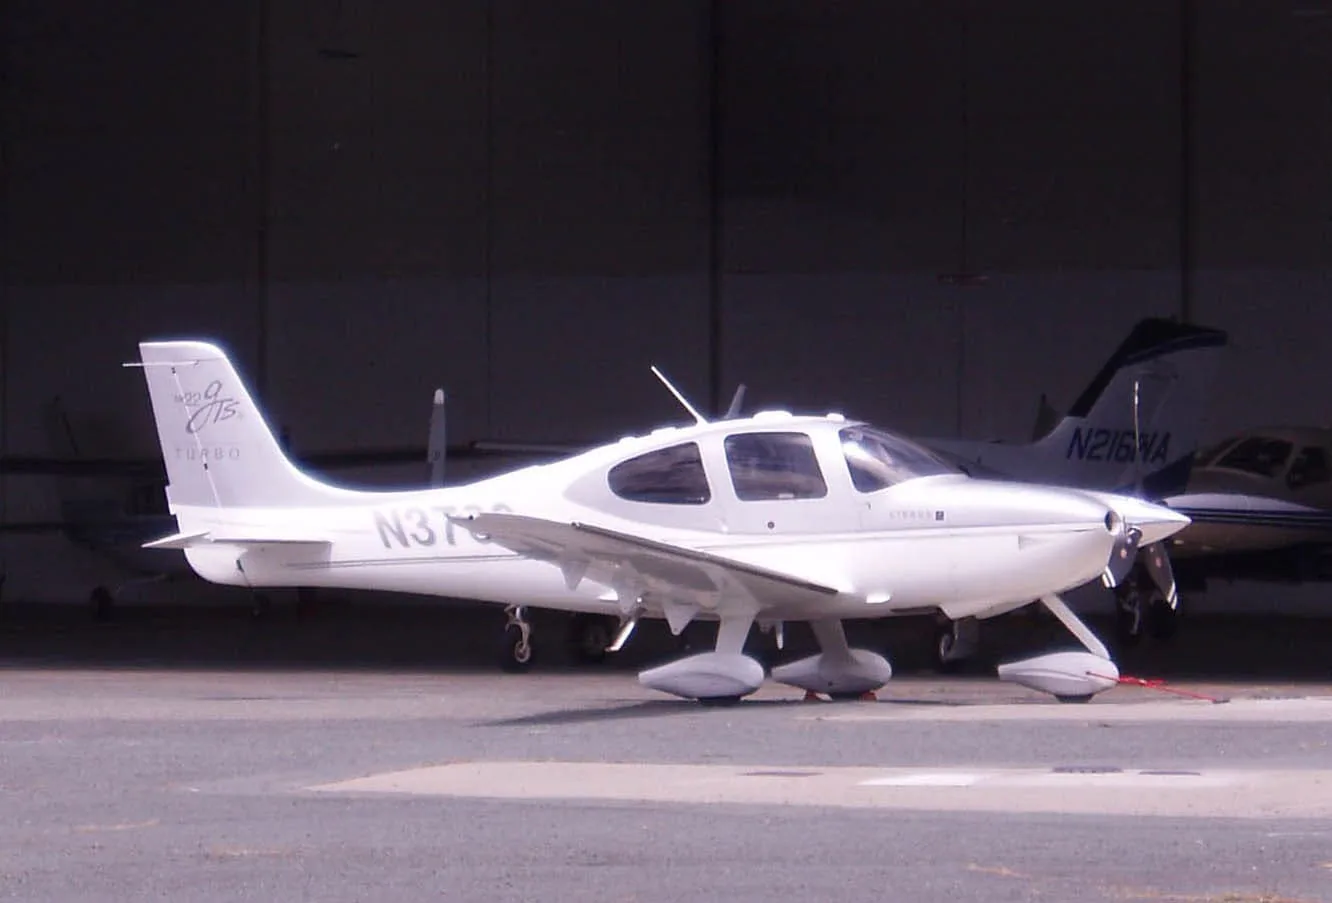
Sharing the flying in your Cirrus starts with a clear insurance review for the person joining you. A spouse, adult child, business partner or friend may have permission to use the aircraft without yet satisfying the pilot provisions in its policy. Before scheduling that person’s first flight in the proposed role, ask BWI to review the actual aircraft, experience, training plan and policy wording.
The useful question is more specific than whether you can add another name. Explain whether the person will receive instruction, fly independently, act as a safety pilot or participate in a shared-ownership arrangement. Those are different situations to describe. The insurance response should address the activity you are planning, not a simpler version of it.
This guide covers adding a spouse or second pilot to an SR20, SR22 or SR22T insurance arrangement. It helps you prepare the request, understand an insurer’s conditions and keep the records current as the pilot progresses. There is no universal extra premium or training requirement for every Cirrus second pilot. The answer comes from a submission based on your circumstances.
Define the second pilot role first
Write down what the person will actually do in the aircraft. A spouse beginning lessons with an instructor has a different plan from an experienced Cirrus pilot joining the roster for independent travel. A person riding along as a passenger should not be described as a pilot merely because a pilot certificate is held. Describe intended participation accurately.
If the plan will develop in stages, identify those stages. You might request review for dual instruction now and a later discussion of independent flying. Do not assume acceptance of the first stage includes the second. Ask which change requires another submission, what information will be needed and how acceptance will be confirmed.
Clarify whether the person will fly only with you or will use the aircraft without you. That distinction helps prevent a casual family conversation from becoming an inaccurate application answer. Include the locations and use expected when another pilot takes the aircraft on a trip. The same Cirrus can have a different operating pattern once access expands.
Collect current information for the person being added
Prepare the pilot information BWI and the proposed insurer request. It may include certificates and ratings, total time, time in the relevant aircraft, recent flying, training and loss history. Use current records and identify estimates honestly. A resume or an old application can be a useful starting point without answering every present underwriting question.
Separate the person’s experience from yours. A highly experienced primary pilot does not make a spouse’s hours or training history identical. Likewise, a second pilot’s strong background should be presented accurately rather than reduced to the statement that the person is qualified. The insurer needs the information relevant to its review, including any gaps requiring explanation.
Identify the aircraft correctly. SR20 experience is not automatically the same information as SR22T experience, and a move between generations may involve a different configuration. Provide the model, year and relevant equipment description requested for the submission. Ask BWI to clarify how the insurer wants experience reported rather than deciding which time counts as equivalent yourself.
Explain the current policy arrangement
Send BWI the policy information needed to review the change. Include the declarations, pilot provisions and relevant endorsements, not only a certificate or premium invoice. If the aircraft is already insured through BWI, ask what updated documents or application answers are needed. A request should refer to the current policy period and actual insured aircraft.
Ask whether the proposed person needs to be individually named or may qualify under a permitted-pilot provision already in the policy. BWI’s SR20 open-pilot article explains the general concept, but its examples should not be substituted for your own terms. The wording governing your aircraft must establish what is required.
Record any uncertainty as an open item. For example, an owner may not know whether a provision applies to instruction or independent use. Send the question with the intended arrangement. Resolving that detail before a flight is more useful than trying to interpret a short quotation summary after plans have already been made.
Distinguish a pilot entry from ownership and insured status
Adding a spouse as a pilot does not necessarily change who owns the aircraft or which entity is the named insured. If the aircraft belongs to an LLC, identify the LLC and explain the spouse’s relationship to the operation. A family relationship should not be used as a substitute for checking the policy definitions and requested status.
If ownership will change at the same time, say so explicitly. A person becoming a co-owner, acquiring an LLC interest or taking title jointly creates an additional review beyond the pilot request. Ask BWI how the proposed policy and endorsements should reflect the change. Qualified legal and tax advisers should address the ownership decision itself.
Ask how the individual is treated under the liability coverage as well as under the pilot provisions. Permission to operate the aircraft and protection as an insured party are related questions that may have different answers. The owner’s policy and any separate insurance held by the second pilot should be reviewed according to their actual terms.
Make the instructor part of a training request
When the person being added will receive instruction, identify the instructor and describe the planned training. Include the aircraft to be used, the student’s intended role and the information requested about the instructor. Do not assume an instructor is accepted simply because the instructor is experienced or is recommended by another Cirrus owner.
Cirrus describes a training network and continuing-education resources. Those resources can help you find relevant instruction and understand available programs. Insurer acceptance still needs to be confirmed for the actual proposal. A course name, booking confirmation or manufacturer relationship should not be treated as evidence that every policy condition has been satisfied.
Ask how the aircraft policy and instructor’s own insurance should be coordinated. An instructor may have separate coverage serving a different purpose. A certificate showing that separate insurance exists does not answer every question about the owner’s aircraft, the instructor’s status or a potential recovery claim. Provide the relevant requests and agreements for review.
Read training conditions as a sequence of decisions
| Proposed stage | Confirmation to request |
|---|---|
| Pilot request submitted | What is under review and which records are outstanding |
| Instruction proposed | Accepted person, instructor, activity and conditions |
| Training completed | Required evidence and remaining insurer requirements |
| Independent flying proposed | Confirmation that the new role is accepted |
| Ownership or use changes | Separate review of entities, use and policy terms |
An insurer’s response may contain conditions involving instruction, experience, records or the proposed use. Read the actual response and ask BWI to explain unclear language. Avoid turning a general conversation about training into a fixed number of hours that has not been offered for your risk. Another owner’s requirement is not your endorsement.
For each condition, identify who must do what and when it must be completed. Distinguish a condition that affects coverage from a recommendation or a future review item. Ask which evidence confirms completion and whether further written acceptance is required. A short tracking sheet can prevent a condition being lost among scheduling emails.
Update the insurance team when training is complete or the operating plan changes. A completion document may be needed, but sending it should not be assumed to settle unrelated conditions. Ask what remains outstanding for the next proposed stage. The person planning an independent trip should receive the current written response rather than an earlier training-only discussion.
Work through a family ownership example
Consider a fictional SR22 owner whose spouse wants to begin flight training in the family aircraft. The owner plans to keep the aircraft in the same LLC, while the spouse first flies with an instructor and later hopes to travel independently. This is an illustration of a planning process, not a description of an accepted policy or a BWI customer.
The initial submission should identify the LLC, aircraft, spouse’s current experience, proposed instructor and training arrangement. It should also explain the later goal of independent flying. The owner can then ask which terms are available for the immediate activity and what would need review before the later activity begins. Each answer should be recorded against the relevant stage.
If the spouse completes training, the next step is to supply the required evidence and confirm the insurance position for the new role. The family should also report any associated ownership or use changes. This keeps a progression from instruction to independent use from being treated as one blanket approval issued at the start.
The same method works for an experienced second pilot, but the information and conditions may differ. Begin with the proposed role, obtain the insurer’s actual response and keep the next decision visible. There is no reason to invent a standard family-pilot package when the useful answer is a documented arrangement for the people flying your aircraft.
Send a request that identifies the next decision
A useful message to BWI names the aircraft, current policy and person being proposed, then states the role and intended start date. Explain what has already been completed and what is still planned. Attach or arrange to provide the requested pilot records through the appropriate channel. This gives the team a concrete request to review instead of an instruction to add someone without an operating description.
If the response is conditional, repeat the outstanding items in your planning record and identify the next confirmation needed. Both pilots should be able to tell whether the request is still under review, accepted for instruction or accepted for the proposed independent use. Clear status labels prevent a pending request from being mistaken for a completed policy change.
Ask how the change affects the whole proposal
Discuss the premium, limits, deductibles and conditions together. An additional pilot request can require underwriting review, but it does not come with a universal surcharge. Ask whether the proposed change affects the current policy and whether other terms would change. A price without an explanation of the accompanying conditions provides an incomplete comparison.
Keep the facts consistent if alternative proposals are considered. Compare the same aircraft value, use, pilots and requested coverage. Otherwise, a lower premium may reflect a different submission rather than an advantage for the arrangement you want. Ask BWI to identify any difference that would affect the family’s intended flying.
Be specific about the effective date. A request sent today should not be treated as acceptance effective today unless that has been confirmed. Tell BWI about the intended first training session or trip without assuming a particular processing time. Build the schedule around the actual response and obtain confirmation before relying on changed terms.
Review passenger liability and the family travel plan
When more than one family member can fly, discuss the passenger arrangements as well as pilot acceptance. Ask BWI to explain the offered liability limits and any passenger limitations or other relevant restrictions. The headline limit does not convey every condition, and a second pilot’s addition does not by itself establish a different liability structure.
Explain whether the aircraft will be used for family travel, company trips or a mixture of activities. If the spouse will carry colleagues or participate in another organization’s travel, include that information. Do not assume a family-owned aircraft has only one possible use. The submission should describe the actual plans of the people using it.
If the family relies on other personal or business liability insurance, ask the appropriate advisers how it interacts with aviation. A personal umbrella should not be presumed to fill every aircraft-policy limitation. Coordinate the policies while keeping the aviation terms visible. Ownership planning and broad wealth protection do not replace an aircraft-specific coverage review.
Treat safety pilot and occasional access requests carefully
An owner may want a spouse or friend available for occasional flying rather than regular independent use. Explain the intended role accurately, including any proposed safety-pilot activity. Ask the relevant instructor or qualified adviser about operational and regulatory requirements, and ask BWI separately about the insurance position. Insurance acceptance alone does not establish legal authority for a role.
Avoid the shortcut that another certificated pilot in the cockpit necessarily resolves every issue. The policy may distinguish among permitted pilots or impose conditions relevant to the operation. State who will act in which role and request clarification. The actual arrangement matters more than the informal phrase flying together.
Review changes before extending access further. A person initially considered for occasional participation may later want to reposition the aircraft or take it away for a weekend. That can be a different proposed activity. Confirm whether the existing acceptance addresses it and keep any revised instructions with the insurance records available to both pilots.
Keep the pilot roster current after approval
Once the change is arranged, store the final documents and identify any continuing conditions. Keep a record of accepted roles, relevant training dates and items requiring another review. This administrative record should point back to the policy rather than attempt to replace it. Both pilots should know where to find the current information.
Tell BWI about material changes involving experience, use, ownership, instructors or the aircraft. A roster can become outdated when training pauses, a pilot returns after a long break or the family upgrades from an SR20 to an SR22T. Ask what the policy requires and seek review before assuming the earlier terms fit the changed situation.
At renewal, review the roster instead of copying it automatically. Confirm who still flies, what each person does and whether the submission remains accurate. Remove ambiguity about a pilot who was discussed but never accepted or a training plan that never began. Clear records make it easier to compare the next policy period on reliable facts.
Frequently asked questions
Is my spouse automatically allowed to fly my Cirrus
Do not assume automatic permission under the insurance policy because you are married or share aircraft expenses. Review the permitted-pilot wording and any relevant conditions. Explain the intended role to BWI and obtain the required confirmation. The owner’s consent and the pilot’s legal qualifications also need their respective consideration.
Does adding a second pilot always raise the premium
There is no single price outcome for every submission. Ask for the insurer’s response to the proposed pilot and review any change in premium alongside limits, deductibles and conditions. A forum example or a quote for another aircraft cannot establish the cost for your policy. Supply current pilot information so the review is based on the actual request.
Can my spouse train before being approved for independent flight
Ask BWI to review the specific instruction arrangement and identify the terms available for that activity. Training with an instructor and flying independently should not be assumed to have the same acceptance. Confirm the position before either activity begins, and obtain any additional review required as training progresses.
Does a named pilot automatically become a coowner
No. Ownership is established through the relevant legal arrangements and records. Pilot permission and insured status require review under the policy. If ownership is also changing, tell BWI so both matters can be addressed. Do not rely on a pilot entry to update title, an LLC relationship or a lender’s requirements.
Can I use an open pilot provision instead of requesting a name change
The actual policy determines whether the proposed pilot and activity qualify. Ask BWI to review the wording and required evidence rather than assuming the provision applies. An open-pilot clause also should not be read as proof of every person’s insured status or as permission to disregard other policy conditions.
Review your second pilot plan with BWI
Send BWI the aircraft details, current insurance, proposed pilot information and the role you want reviewed. Include the instructor when training is planned and explain any ownership or business-use changes. A request organized around the actual flying helps the team discuss the relevant options and outstanding conditions.
Start through BWI’s Cirrus insurance quote request or call 800-666-4359. Ask for confirmation of the accepted arrangement, effective date and any steps needed before the pilot’s role changes. Keep the written response with your policy. Sharing a Cirrus can be an enjoyable part of ownership when both pilots understand the plan supporting it.
Sources and related resources
BWI SR20 open pilot explanation
Continue Reading


